

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 5.85% CAGR for Worldwide External Power Supplies Market (2026–2032) Amid Robust Asia Pacific Demand

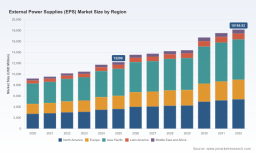
Worldwide External Power Supplies (EPS) Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting’s latest market study on Worldwide External Power Supplies (EPS) synthesizes five years of historical performance (2020–2025) and a seven‑year forecast (2026–2032) into a pragmatic roadmap for commercial, product and policy decisions in 2026. With the EPS market estimated at USD 12,200 Million in the base year (2025) and projected to expand at a compound annual growth rate (CAGR) of 5.85% through 2032—reaching just over USD 18.16 Billion—our analysis pairs quantitative modelling with hands‑on commercial playbooks. This press briefing highlights why the research is strategically essential for boardrooms, procurement teams, product planners, and M&A specialists, while preserving the report’s proprietary subsegment tables and granular datapoints for subscribers.
Worldwide External Power Supplies (EPS) Market
Why this report matters in 2026
- Macro clarity in an uncertain year: The EPS market has rebounded materially since 2020 and is on a multi‑year growth trajectory. That trajectory is uneven across channels and applications, and navigating it requires more than headline growth rates—it requires operational scenarios, component risk scoring, and supplier capability maps that our report provides.
- Regulatory inflection points: New and updated energy‑efficiency and ecodesign requirements in major jurisdictions are changing product compliance roadmaps. Our work translates regulatory timelines into product release and inventory decisions to avoid market access disruptions.
- Actionable vendor intelligence: With a moderately fragmented supplier landscape (CR3 ≈ 28.5%; CR5 ≈ 38.2%), selecting partners or acquisition targets depends on a nuanced understanding of technological differentiation, certification breadth, and manufacturing footprint—precisely the dimensions the report benchmarks.
Market trajectory and what is driving growth
At the aggregate level, the EPS market demonstrates steady expansion: the 2025 market size (USD 12,200 Million) is projected to rise to roughly USD 13,546 Million in 2026 and to exceed USD 18.16 Billion by 2032 under our central case. The 5.85% CAGR through the forecast window masks several structural forces that are shaping opportunity and risk.
Worldwide External Power Supplies (EPS) Market
- Efficiency and standards: Global energy‑efficiency standards remain a primary demand driver. Compliance with established DOE requirements and recently adopted EU ecodesign rules is prompting OEMs to accelerate design upgrades and certification programs.
- Product complexity and new topologies: Adoption of GaN and other advanced power semiconductors is enabling higher power density and lower system losses, shifting design win dynamics toward suppliers who can commercialize these technologies at scale.
- Channel and application shifts: Demand patterns are evolving across consumer, networking, medical and industrial end markets. Each channel has distinct purchasing cadences, warranty expectations and certification burdens that change supplier selection criteria.
- Supply chain and geopolitics: Component lead times and allocation volatility persist, and geopolitical tensions continue to inject uncertainty into sourcing strategies—making dual‑sourcing, regional buffer inventory, and inventory hedging operational imperatives.
Regulatory and policy developments that change the playbook
- United States: In April 2026, the U.S. Department of Energy issued revisions that relax certain reporting requirements for exempt consumer EPS under the EPS Service Parts Act. Although the change simplifies compliance burden for specific legacy product categories, DOE energy‑efficiency standards remain binding for most modern EPS designs. Manufacturers and OEM purchasers must reconcile reporting simplifications with continuing efficiency obligations.
- European Union: The EU’s Regulation 2025/2052, adopted in late 2025 and coming into force in December 2028, tightens ecodesign requirements for external power supplies and portable chargers. Firms targeting EU markets should calibrate product roadmaps and certification timelines now to avoid costly redesigns or delayed listings in Q4 2028 and beyond.
Strategic implications for 2026 — what boards and functional leaders should do now
- Product and R&D leaders: Prioritize modular architectures and semiconductor roadmaps that allow platform upgrades for efficiency and safety certifications without full redesigns. Use the report’s technology adoption curves and certification lead‑time models to schedule development sprints that align with EU and DOE deadlines.
- Procurement and supply chain: Translate the report’s supplier capability maps into dual‑source strategies for critical components, and implement dynamic safety stock models based on our component risk scoring. Shorten lead‑time exposure by qualifying local assembly partners in priority markets where trade tensions may affect logistics.
- Commercial and pricing: Reassess product portfolios for margin dilution risks from higher certification and compliance costs. Our report includes price elasticity scenarios and channel mix sensitivity analysis that help pinpoint where premium pricing for efficient EPS is acceptable and where cost absorption is unavoidable.
- M&A and partnerships: Given the market’s moderate concentration, acquisitions and strategic alliances remain viable routes to obtaining technology or capacity quickly. Use our proprietary target screening framework to prioritize candidates by certification portfolio, GaN capability, and regional manufacturing resilience.
Competitive landscape — who matters and why
The market is characterized by a mix of global OEMs, niche specialists, and vertically integrated suppliers. Our competitive analysis benchmarks companies on product breadth, certification reach, advanced topology adoption, manufacturing footprint and channel strength. Highlights from the vendor universe include:
Worldwide External Power Supplies (EPS) Market
- Delta Electronics (Taiwan): A broad global manufacturer with strengths in high‑efficiency AC‑DC EPS for IT, industrial and medical applications. Delta’s emphasis on DOE Level VI and EU ecodesign compliance positions it strongly where regulatory requirements are most exacting.
- Lite‑On Technology (Taiwan): Known for compact, high‑efficiency designs that serve computing and communications markets; Lite‑On’s engineering focus on density and thermal performance is a competitive differentiator where space and weight matter.
- Mean Well Enterprises (Taiwan): A specialist in switching power supplies, with an extensive EPS portfolio for industrial and medical segments; Mean Well’s depth in open‑frame and enclosed adapters makes it a go‑to for project engineering teams.
- XP Power (UK): Focused on medical and industrial high‑reliability EPS; recent product introductions in 2026 (new PGW/PGD series) underline XP Power’s strategy of targeted product launches to capture high‑margin subsegments.
- CUI Inc. (US), Phihong (Taiwan), Chicony, Acbel, Salcomp, TDK‑Lambda (Japan), Artesyn (Emerson), FSP Group, Adapter Technology, and UNIFIVE (Japan): Each brings complementary strengths—global certification networks, PoE and networking‑focused EPS, mobile charger expertise, and emerging GaN implementations. Adapter Technology’s explicit work on GaN and high‑density designs is notable for customers seeking next‑generation solutions.
Collectively, these suppliers form a landscape where specialization and certification depth often win design‑ins, rather than scale alone. That dynamic is reflected in the market’s concentration metrics: while a number of large players exist, a significant portion of demand is served by smaller or specialized vendors—creating avenues for targeted partnerships or bolt‑on acquisitions.
What’s inside the full PW Consulting report (practical deliverables)
Beyond the headline growth figures, the report delivers operational tools and datasets designed for immediate action:
- Market model and scenarios: A transparent spreadsheet model covering base, upside and downside cases for 2026–2032, sensitive to price, component availability and regulatory shocks.
- Supplier scorecards: Comparative matrices that grade manufacturers by certification portfolio, GaN readiness, production flexibility and lead‑time performance.
- Regulatory timeline and gap analysis: Practical checklists and Gantt charts for compliance programs tied to DOE and EU implementation dates.
- Channel and pricing playbooks: Recommended commercial strategies for consumer, networking, medical and industrial routes‑to‑market with sample P&L impacts under different pricing strategies.
- Component risk register: Prioritized list of critical components, alternate sources, and suggested inventory buffers to mitigate allocation risks.
- M&A screening and valuation templates: Criteria and valuation sensitivities tailored to EPS targets and technology acquisitions.
- Executive presentations and board‑ready one‑pagers: Condensed decision materials to accelerate approval processes and resource allocation.
How senior leaders should use this intelligence in 2026
- Turn growth into strategically aligned investments: Use the market model to allocate R&D budget toward platforms that will remain compliant and competitive through 2028–2030 regulatory windows.
- Mitigate supply risk proactively: Implement the report’s dual‑sourcing and inventory playbooks to maintain production continuity amid component allocation volatility and geopolitical pressure.
- Prioritize certification-leading suppliers: Wherever market access and safety liability matter—medical, industrial and networking—choose partners with demonstrable certification pipelines and testing capacity.
- Use targeted M&A to acquire capability fast: For companies missing GaN expertise or specialized medical compliance, an acquisition can compress time‑to‑market; our M&A toolkit shows how to size and value such deals.
Trailer principle — what we’re not publishing here
This briefing intentionally refrains from publishing the report’s granular subsegment tables—regional splits, output‑power band revenues, and application‑level figures are omitted to preserve the proprietary value of the dataset and to encourage informed engagement. The full report contains detailed time‑series for each subsegment, scenario spreadsheets, and supplier transaction histories that are essential for transaction diligence and product roadmap planning.
Next steps and how to obtain the full analysis
For executive teams preparing budgets, procurement cycles or M&A agendas in 2026, this study is designed to convert market insight into actionable decisions. PW Consulting offers tailored briefings, supplier workshops, and scenario modelling sessions based on the report. To access the complete dataset, proprietary subsegment breakdowns, and the operational toolkits described above, please visit our report page or contact our advisory team to schedule a strategy session.
PW Consulting remains available to support boards, product leaders and deal teams in converting EPS market growth—estimated at a 5.85% CAGR through 2032—into defensible, revenue‑generating decisions while managing the compliance, technology and supply‑chain risks that define the next phase of industry competition.
For detailed analysis of this topic, please visit the official page: Worldwide External Power Supplies (EPS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com