

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Classified Circuit Breaker Market Poised to Expand at a 6.0% CAGR, New Insights Reveal

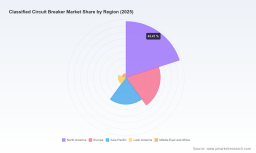
Worldwide Classified Circuit Breaker Market: Strategic Outlook for 2026 Decision-Makers
PW Consulting’s new market study—base year 2025, forecasting 2026–2032—delivers a pragmatic, decision-focused assessment of the classified circuit breaker market designed to inform procurement, product strategy, and M&A choices in 2026. The market has evolved from roughly USD 410.5 Million in 2020 to USD 540.0 Million in 2025, with our proprietary modeling projecting continued expansion to approximately USD 578.6 Million in 2026 and reaching about USD 812.0 Million by 2032. This trajectory reflects a compound annual growth rate (CAGR) of 6.0% over the forecast horizon and underscores structural demand drivers that will shape supplier and buyer behavior in the next strategic planning cycle.
Worldwide Classified Circuit Breaker Market
Why this report matters for 2026 planning
-
Timing. With grid modernization projects, renewable integration, and retrofitting cycles accelerating, 2026 is when many corporates and utilities will need to convert strategic intent into procurement and capex allocations. Our report turns market momentum into executable choices.
Worldwide Classified Circuit Breaker Market -
Risk-aware growth. The study combines top‑down market sizing with bottom‑up supplier and channel analysis so executives can prioritize investments that balance growth potential with supply‑chain and regulatory risk.
Worldwide Classified Circuit Breaker Market -
Competitive clarity without spoilers. We provide a forward-looking view of competitive positioning and capability gaps while reserving detailed subsegment tables for licensed subscribers—ideal for organizations that want the blueprint but need to keep tactical numbers under NDA.
Market trajectory and what the headline numbers hide
The headline growth—from roughly USD 540.0 Million in 2025 to an estimated USD 578.6 Million in 2026—signals steady demand, but beneath this aggregate expansion are differentiated dynamics: substitution of legacy units, increased uptake of digitally enabled breakers, and regional modernization rhythms tied to distribution network reinvestment. Our forecast to 2032 captures nonlinear inflections driven by technology certification cycles and supply chain localization initiatives. Practically, this means procurement officers and product leaders should expect steady topline growth while preparing for episodic shifts in sourcing and product specs as smart and classified‑compatible options gain share.
Key dynamics shaping supplier and buyer strategy
-
Interchangeability and standards. UL‑classification remains a central enabler of third‑party replacement markets: compliance allows compatibility across multiple OEM loadcenters and creates a resilient aftermarket channel. For suppliers, investing in classification testing is table stakes; for buyers, it opens the opportunity to optimize total cost of ownership through validated third‑party options.
-
Product innovation and digitalization. The migration toward smart breakers with remote monitoring, trip analytics, and integration into building energy management systems is creating a premium tier of demand. Certification timelines for digitally enabled products mean that entrants who can expedite approvals will capture early adopter budgets.
-
Supply‑chain localization. Manufacturers are increasingly announcing local assembly and regional capacity expansion to reduce lead times and tariff exposure. This reduces logistics risk for large retrofit programs but raises the bar on local regulatory and quality assurance capabilities.
-
Raw‑material pressure. Copper, steel and engineering plastics remain key inputs; material cost volatility and availability affect both pricing and lead times for molded case and miniature breakers. Procurement strategies must therefore include hedging, multi‑sourcing and supplier performance metrics tied to material security.
Competitive landscape — capabilities and battlegrounds
The market displays moderate concentration: our analysis shows the top three vendors control just over half the market, while the top five approach seven in ten. That structure produces a two‑speed competitive environment—large global incumbents competing on breadth and channel access, and specialized suppliers competing on compatibility, form factor and aftermarket services.
-
Eaton Corporation (Dublin, Ireland) — Broad product line of UL‑classified breakers and deep compatibility claims across hundreds of legacy loadcenters. Eaton’s strength is its cross‑portfolio presence (arc‑fault, ground‑fault, surge, thermal magnetic) and marginal advantage in channel familiarity with electrical contractors.
-
Connecticut Electric (United States) — Niche expertise in classified replacements for residential and light commercial panels. The company’s focus on interchangeability and aftermarket reliability makes it a go‑to for retrofit projects where minimizing panel rework is critical.
-
Siemens (Munich, Germany) — Global engineering footprint and a full spectrum of breakers. Siemens leverages scale and global certification experience, making it a preferred supplier in projects that demand integrated solutions beyond single‑panel replacements.
-
ABB Ltd (Zurich, Switzerland) — Strong industrial and utility lineage, with a portfolio spanning low to high voltage. ABB competes where industrial robustness and integration into power distribution systems are decisive.
-
Schneider Electric (Rueil‑Malmaison, France) — Market influence via branded loadcenters and partner channels. Schneider’s ecosystem advantage influences compatibility dynamics and aftermarket replacement pathways.
-
GE Vernova (United States) — Legacy OEM credibility in residential and commercial panels, with product lines that accept classified replacements; this duality shapes OEM aftermarket strategies.
-
CHINT Group (China) — Rapidly expanding global footprint and recent announcements around local assembly for air circuit breakers indicate an aggressive localization play that aims to shorten lead times and compete on price for regionally scaled projects.
-
Mitsubishi Electric, LS Electric, Fuji Electric — Representing the broader pool of established global suppliers, each brings distinct strengths in molded case and industrial breakers; their competitive role is often tied to regional projects and system integration requirements.
Recent market signals that will influence 2026 decisions
-
Regional assembly initiatives. Announcements of local assembly operations for air circuit breakers underscore a deliberate shift toward on‑shoring and near‑shoring to de‑risk long lead times for large retrofit and utility programs.
-
Trade shows as innovation accelerators. Prototypes of digitally enabled breakers surfaced at leading industry exhibitions, indicating that certification and go‑to‑market timing for smart products will be a critical gating factor in 2026 purchasing windows.
-
Smart device proliferation. Increased presence of intelligent breakers at major industrial shows signals accelerating integration into factory automation and energy management stacks—buyers should factor integration and data licensing into procurement specifications.
What the PW Consulting report contains — practical, transaction‑grade deliverables
Our study is structured to be immediately usable by strategy, procurement, and product teams. It includes:
-
Proprietary market model and demand scenarios calibrated to 2020–2025 historicals and extended through 2032, with sensitivity runs for material price shocks and accelerated smart‑breaker adoption.
-
Supplier scorecards that evaluate certification breadth, form‑factor coverage, channel access, and aftermarket service capabilities to support vendor selection and sourcing consolidation.
-
Go‑to‑market playbooks for entrants and incumbents, including pricing frameworks, distributor incentive structures, and retrofit program engagement templates.
-
M&A and partnership heatmap identifying strategic targets across capability gaps (digital, local assembly, certification breadth) and geographic presence.
-
Regulatory and standards tracker focused on interchangeability and UL classification developments, plus a compliance checklist for product managers.
-
Supply‑chain risk matrix and mitigation strategies addressing raw material constraints, lead time variability and localization trade‑offs.
Note: to preserve the utility of this briefing and in line with our "trailer" approach, detailed subsegment-level tables (regional splits, application‑level shares, and price/volume matrices) are available exclusively in the licensed document. These granular datasets enable precise tender-level budgeting and competitive benchmarking—requests for bespoke extracts are supported under subscription.
Strategic recommendations for 2026
-
For buyers and system integrators: prioritize classified‑compliant products with proven interoperability and insist on data integration capabilities to future‑proof asset management.
-
For suppliers: accelerate classification testing and target regional assembly partnerships to shorten delivery times for retrofit projects; concurrently, develop software and services around breaker data to capture higher gross margins.
-
For investors and M&A teams: focus on targets that combine certification breadth with digital capabilities or local assembly footprints—these attributes unlock premium valuations as buyers internalize total cost and reliability concerns.
Concluding perspective
The classified circuit breaker market is neither a simple replacement market nor purely a high‑growth, high‑margin technology race—it is a hybrid arena where standards, physical interchangeability and emerging digital capabilities intersect. The market’s steady compound growth—anchored by clear structural drivers—creates multiple levers for value creation: supply‑chain resilience, certification leadership, and digital monetization. PW Consulting’s report converts these levers into prioritized actions, practical vendor scorecards, and transaction-ready intelligence that will be essential for corporate decisions in 2026.
Accessing the full intelligence
For procurement teams, strategy leads, and investors seeking the full dataset, including detailed regional and application splits, price/volume matrices, and bespoke modelling, the complete report and licensed data extracts are available through PW Consulting. Contact our market research team to schedule a briefing and receive sample extract options tailored to your decision agenda.
For detailed analysis of this topic, please visit the official page: Worldwide Classified Circuit Breaker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com