

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Palatal Expander Market Poised to Reach USD 1.29 Billion by 2032, Driven by an 8.15% CAGR

Worldwide Palatal Expander Market — 2026 Strategic Preview
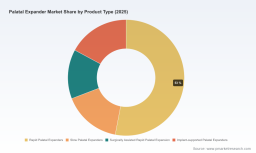
As palatal expansion transitions from a largely analog, appliance-driven therapy to a digitally enabled, multi-modal clinical pathway, executive teams must recalibrate product roadmaps, commercial models, and regulatory playbooks for 2026 and beyond. PW Consulting’s new market study (base year 2025; historical window 2020–2025; forecast 2026–2032) quantifies this transition and translates it into decision-grade guidance. At the macro level, the global palatal expander market is estimated at USD 745.5 Million in 2025 and is projected to reach approximately USD 1,290.13 Million by 2032, growing at a compound annual growth rate (CAGR) of 8.15% over the forecast period. These headline figures reflect accelerating adoption of digital workflows, emergence of removable 3D‑printed expanders, and expanding indications across age cohorts.
Worldwide Palatal Expander Market
Why this report matters for 2026 corporate decisions
-
Prioritize R&D investments with confidence — our scenario-driven forecasts identify where incremental product innovation (e.g., removable 3D-printed devices, miniscrew-assisted solutions, hybrid implant-supported systems) will deliver outsized commercial returns versus incremental engineering effort.
Worldwide Palatal Expander Market -
Shape regulatory and market-entry sequencing — by mapping country-level approval timelines and class determinations, the report helps firms time filings, clinical studies, and pilot launches while minimizing time-to-revenue risk.
Worldwide Palatal Expander Market -
Refine commercialization and channel strategy — we evaluate direct-to-clinic, lab-enabled, and distributor models against product types and practitioner preferences to guide salesforce sizing and partner selection for 2026 rollouts.
-
Design reimbursement and coding strategies — the study synthesizes billing pathways and CDT coding implications that materially affect adoption economics for orthodontists and payers.
-
Underpin M&A and investment decisions — a transparent market-concentration analysis, competitive mapping, and identified target archetypes enable rapid screening of acquisition candidates and bolt-on opportunities.
What the PW Consulting study contains (practical, executable content)
-
Market sizing and trajectory: an audited topline from 2020–2025 with a 2026–2032 forecast, sensitivity cases (conservative, base, accelerated) and embedded breakouts by product architecture, clinical workflow, and end-user cohort.
-
Competitive intelligence dossier: strategic profiles for major OEMs, labs, and digital entrants including product roadmaps, manufacturing footprints, channel footprints, and patent/clearing activity.
-
Regulatory playbooks: country-specific submission strategies, classification risk matrices, and pre-submission checklists designed to shorten regulatory cycles while safeguarding claims and labeling.
-
Reimbursement & economic models: practice-level cost/benefit models, payer negotiation outlines, and coding pathways (including how orthodontic appliance services are commonly billed under CDT frameworks) to accelerate uptake.
-
Go-to-market toolkits: package-level pricing playbooks, lab partnership term sheets, pilot design templates for clinical validation, and salesforce deployment models calibrated to different market scenarios.
-
M&A & partnership playbooks: valuation benchmarks, earn-out structuring options, integration checklists for digital dentistry assets, and prioritized target lists by strategic archetype.
Key dynamics shaping 2026 adoption
-
Digital disruption: the migration to intraoral scanning, CAD/CAM and direct 3D printing is not theoretical — it is now a commercial reality. New removable 3D‑printed expanders, integrated with scanner-enabled workflows and aligner treatment streams, are shifting clinical preference away from exclusively screw-centered fixed devices in certain patient segments.
-
Regulatory inflection points: recent device clearances and certifications are reducing regulatory friction for digitally manufactured expanders and modular systems. Notably, devices of this class are being handled under established orthodontic device classifications in mature markets; manufacturers should expect dossier requirements to emphasize biocompatibility, mechanical performance and, increasingly, software validation for CAD/CAM processes.
-
Clinical paradigm expansion: miniscrew-assisted solutions and hybrid implant‑supported approaches are enabling treatment of older adolescent and adult skeletal constriction cases with improved skeletal effects, changing both indication sets and average procedure economics.
-
Economics & reimbursement: billing pathways for expansion therapy are well established within orthodontic coding frameworks, but reimbursement variability across payers and geographies materially impacts case acceptance and pricing strategies — practices factor these dynamics into treatment planning and supplier choice.
-
Fragmentation with consolidation signals: while a substantial portion of the market remains distributed among regional suppliers and labs, leading manufacturers are leveraging platform advantages and regulatory clearances to consolidate share. Our concentration metrics confirm a market that is consolidating but not yet highly concentrated, implying continued white-space for focused innovators.
Competitive panorama — strategic takeaways
The competitive set is diverse: traditional orthodontic device manufacturers, specialized labs, and digitally native platform players each bring distinct strengths and go-to-market implications.
-
Align Technology — strategic implication: the commercialization of removable 3D‑printed palatal expanders integrated with intraoral scanners and aligner ecosystems changes the adoption calculus for clinicians who already use digital aligner workflows. Firms competing with or partnering to complement this model must demonstrate seamless digital integration and clear clinical differentiators.
-
Leone S.p.A. and Dentaurum — strategic implication: deep mechanical expertise and MARPE-capable components position these firms as go-to suppliers for clinicians prioritizing screw-based strength and modularity. Opportunity exists for collaboration on hybrid systems combining mechanical robustness with digital manufacturing efficiencies.
-
Regional OEMs and labs (DynaFlex, Forestadent, Ortho Technology, Great Lakes, ODL, RMO, American Orthodontics, Lancer, Ormco) — strategic implication: many established suppliers retain strong lab and clinician relationships. Their strengths in custom fabrication and distribution represent acquisition targets for digital entrants seeking scale or for OEMs seeking a service-enabled distribution layer.
-
Market structure note: our concentration analysis shows the top three players capture a mid-single-digit share concentration while the top five approach a near-majority influence in certain product niches. This configuration favors entrants that can rapidly scale partner networks or control differentiated IP.
Implications for core stakeholders
-
Manufacturers — prioritize modular product architectures that allow incremental feature upgrades (e.g., digital fittings, implant anchorage compatibility), and prepare global regulatory strategies that de-risk three market entry paths: EU/MDR, China (NMPA), and the U.S. FDA.
-
Investors & PE — the mid-market shows attractive tuck-in opportunities: diagnostics-to-therapy platform plays, digital lab networks, and component specialists with defensible supply relationships. Use the report’s valuation range bands and go/no-go triggers to expedite diligence.
-
Orthodontic labs — invest in ISO‑certified digital workflows to stay relevant as clinicians demand faster turnaround and digitally integrated appliances. Labs that combine precision fabrication with clinical services (trial fittings, hybrid solutions) capture higher per-case value.
-
Payers & health systems — the growing clinical differentiation among expansion modalities warrants targeted medical policy updates and pilot payment programs to capture long-term benefits where skeletal outcomes are demonstrably improved.
-
Clinicians — treatment planning must now balance mechanical efficacy, patient comfort, treatment duration, and billing pathways. Early adoption of digitally integrated expanders can improve workflow efficiency and patient experience where reimbursement aligns.
How to use this intelligence in 90/180/365-day plans
-
90 days: validate product claims and complete gap analysis against recognized regulatory predicates; initiate payer engagement in target geographies and finalize digital integration partners.
-
180 days: pilot in selected clinics using the report’s clinical trial templates; refine pricing and contractual terms with labs and distributors; prioritize capital allocation to manufacturing upgrades or strategic acquisitions.
-
365 days: scale commercialization in line with forecast scenarios; execute on M&A or partnership moves identified in the report; align global regulatory submissions to the sequenced launch plan that maximizes near-term revenue while protecting IP and clinical differentiation.
Next steps & how to access full intelligence
This executive preview outlines the strategic value of the full PW Consulting Worldwide Palatal Expander Market report for decisions you will make in 2026. The complete study contains granular segmentations, country-level regulatory timelines, product-level unit economics, and an actionable M&A pipeline tailored to different strategic objectives. For teams evaluating launches, acquisitions, or clinical partnerships, the full report functions as both a quantitative roadmap and a practical execution guide. Visit PW Consulting’s report page to access the full dataset, appendices, and downloadable toolkits that convert insight into repeatable action.
For detailed analysis of this topic, please visit the official page: Worldwide Palatal Expander Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com