

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Fencing Lame Market Forecast to Reach USD 69.37 Million by 2032, Expanding at a 4.15% CAGR

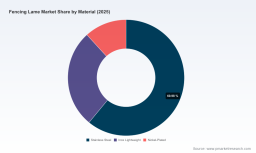
Worldwide Fencing Lame Market: Strategic Imperatives for 2026 — PW Consulting Preview
PW Consulting today releases a strategic preview of our forthcoming Worldwide Fencing Lame Market report, designed to equip manufacturers, brands, federations, distributors and private equity investors with the decision-grade intelligence they need for 2026. Drawing on a proprietary synthesis of historical sales trajectories, material- and standards-driven dynamics, supplier registration regimes, and a concentrated competitive landscape, this preview highlights the levers that will determine winners and laggards without disclosing the full, granular segmentation tables reserved for the full report.
Worldwide Fencing Lame Market
Why this market matters in 2026
The fencing lame market has moved from a niche, equipment-focused category toward a regulated, performance-sensitive and brand-differentiated segment. Our analysis shows the total market increasing from approximately USD 42 million in 2020 to just over USD 52 million in the 2025 base year, with a projected compound annual growth rate (CAGR) of about 4.15% over the 2026–2032 forecast window. By 2032 the market is forecast to approach roughly USD 69 million under the baseline scenario.
Worldwide Fencing Lame Market
These headline metrics mask important structural shifts that will drive strategic choices in 2026: rising homologation and labeling costs, tougher material and safety thresholds for international competition, an industry concentration that favors a small set of established manufacturers and suppliers, and evolving supply-chain realities for conductive fabrics and technical assembly.
Worldwide Fencing Lame Market
What’s changed since 2024 — regulation, materials and supplier economics
- Regulatory tightening: Recent Fédération Internationale d'Escrime (FIE) actions — including updated material rules, new mask and uniform drawing guidance, and a supplier registration regime — are re-shaping product compliance economics. New supplier registration and labeling requirements introduce recurring per-supplier and per-item costs that will change the cost base for homologated lames and integrated jackets.
- Higher technical standards: FIE material and safety rules now emphasize conductive thread density and electrical performance (measured under standardized conditions), alongside a stricter perforation resistance threshold for competition-grade clothing. These standards raise the bar for R&D, quality control and third-party testing.
- Materials supply pressure: Conductive fabrics (silver-based or copper/tin composites) remain the critical input. Performance expectations such as balanced warp-and-weft conductivity and low electrical resistance compel specialized textile processing. Where material supply tightness appears, manufacturers face lead-time and cost risk.
Competitive landscape — concentrated, quality-driven, globally distributed
The global competitive fabric of the lame market is relatively concentrated: the top three firms account for a substantial share of the market, and the top five dominate an even larger share. This concentration creates strategic implications for pricing power, homologation influence and channel relationships.
Key players that the full report profiles in depth include heritage European manufacturers known for premium stainless INOX and silver-fiber technologies, long-established Western retailers and distributors that combine brand partnerships with broad market access, and Asian manufacturers that provide scale and competitive pricing through verticalized production of conductive fabrics and jackets. Each archetype presents a distinct risk-reward profile for 2026:
- Premium European manufacturers: strong brand equity, tight performance specs, favored by top-level athletes and federations — but higher cost bases and the need to defend technical leadership.
- Specialist Western distributors/retailers: deep channel reach and service-level advantages for clubs and schools, but dependent on supplier relationships and inventory strategies.
- Asian manufacturers: cost and scale advantages plus growing technical capabilities (including conductive fabric production) — yet exposed to regulatory credentialing and quality perception risks in key markets.
The report includes company profiles, competitor benchmarking and scenario-driven supplier-selection matrices that reflect these trade-offs without publishing proprietary revenue splits in this preview.
What the full PW Consulting report delivers — practical, ready-to-use tools
The full report is structured to enable operational decision-making across procurement, product, channel and corporate strategy. Highlights include:
- Executive playbooks for 12–24 month roadmaps: prioritized initiatives for product homologation, cost-to-serve optimization, inventory hedging and targeted channel expansion.
- Supplier assessment framework: a weighted scorecard to evaluate potential partners on technical compliance, capacity, lead times, quality systems, homologation track record and total landed cost.
- FIE compliance checklist and cost impact module: stepwise guidance on meeting material and safety standards, anticipated testing cadence and modeled cost implications of supplier registration and per-item labeling economics.
- Product development briefs: specification templates (e.g., conductive thread architecture, resistance parameters, washability, weight targets) tailored to competitive foil and sabre offerings and consistent with international rules.
- Commercial scenarios and pricing sensitivity tools: demand- and price-elasticity scenarios, channel margin models for clubs/schools versus retail/distributor routes, and promotional strategies optimized by customer segment.
- M&A and partnership playbook: due-diligence checklists, value-creation levers for consolidation, integration templates focused on manufacturing synergies and homologation asset transfer.
- Raw data appendices and modeling workbook: historical time series, baseline and alternate forecasts, and downloadable model files for custom scenario planning.
Strategic implications for 2026 decision-makers
Stakeholders must translate macro signals into concrete moves in the coming 12 months. Our analysis identifies five priority actions:
- Operationalize compliance early: Treat FIE material and labeling changes as a supply-chain and product-development issue, not just a certification checkbox. Early investment in testing infrastructure or select accredited test partners minimizes time-to-market risk for competition-grade products.
- Reprice with regulatory cost visibility: Factor supplier registration and per-item labeling fees into margin models and commercial negotiations now. These are predictable, recurring cost elements that can be allocated or passed through depending on channel and customer sophistication.
- Diversify conductive fabric sourcing: Given the technical specificity of conductive textiles, pursue a dual-sourcing strategy: retain proven specialty suppliers for high-performance SKUs while developing validated secondary suppliers to protect against lead-time shocks.
- Differentiate through product-service bundles: For clubs, schools and regional federations, combine durable lames with service offerings (fittings, wash-and-repair programs, training modules) to raise switching costs and rebalance margin mix away from low-price commoditized SKUs.
- Prioritize targeted consolidation and partnerships: Use M&A, joint ventures or exclusive distribution agreements to capture scale advantages in manufacturing or access to homologated certification pathways — particularly where top-tier competitors command market share concentrations.
Risk matrix — what could derail the baseline outlook
- Regulatory shock: Further tightening of material rules or more burdensome homologation processes could compress margins and raise product-development timelines.
- Material supply disruption: Scarcity in conductive fabrics or price spikes in silver-based threads would shift competitive advantage toward vertically integrated producers.
- Market-channel frictions: Rapid shifts in participation rates at clubs and schools, or reductions in funding from federations, could re-weight demand across product tiers and channels.
How PW Consulting’s analysis complements your 2026 planning
Our approach combines quantitative growth modeling with the qualitative judgment necessary where regulation and technical performance matter. The full report delivers the calibrated demand forecasts, cost impact analyses and supplier scorecards you will use to prioritize investments and negotiate with partners in 2026 — while preserving the commercial confidentiality of segment-level revenue and regional breakdowns.
Next steps — access the full intelligence
This editorial preview frames the strategic choices the fencing lame market will present in 2026. For procurement directors, product heads and strategic investors seeking the full datasets, proprietary segment tables, company revenue benchmarks, and downloadable scenario models, PW Consulting’s full Worldwide Fencing Lame Market report contains the operational detail required to act decisively.
Contact PW Consulting to receive the complete report, including: the full forecast model through 2032, granular segmentation and regional analyses, supplier rankings and the ready-to-use playbooks described above. Our team can also arrange a tailored briefing to apply the findings to your organization’s specific risk profile and strategic horizon.
For detailed analysis of this topic, please visit the official page: Worldwide Fencing Lame Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com