

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Polylactic Acid Straw Market Set to Surge at a 12% CAGR as Sustainability Fuels Rapid Expansion

Worldwide Polylactic Acid (PLA) Straw Market — Strategic Preview for 2026 Decision-Makers
As Senior Strategy Consultant and Chief Industry Analyst at PW Consulting, I am pleased to present a forward-looking executive preview of our new Worldwide Polylactic Acid (PLA) Straw Market report. The overview that follows synthesizes the report’s most consequential insights for corporate leaders planning capital, procurement, product and regulatory strategies in 2026. We anchor our analysis in the market’s demonstrated momentum — from roughly half a billion USD in 2020 to approximately USD 1.15 billion in 2025 — and a robust mid-teens expansion trajectory, with a projected compound annual growth rate of 12% through the 2026–2032 forecast window.
Worldwide Polylactic Acid Straw Market
Why 2026 Is a Pivotal Year
-
Regulatory acceleration. Policy instruments that restrict single-use plastics have moved from novelty to mainstream. Enforcement and certification regimes in major jurisdictions have raised the bar for compostability and end-of-life claims, increasing the value of certified PLA formulations and creating barriers for commodity entrants that cannot demonstrate compliance.
Worldwide Polylactic Acid Straw Market -
Supply-side evolution. Producers of PLA resin are scaling capacity and launching grades optimized for straw extrusion. These moves materially alter supply negotiation dynamics — where previously buyers could treat PLA as a commodity, they must now evaluate grade-specific performance (clarity, tensile strength, heat resistance) and secure long-term supply pathways aligned with product specs.
Worldwide Polylactic Acid Straw Market -
Commodity volatility and feedstock risk. Agricultural feedstock and intermediate inputs for PLA have shown meaningful price swings in recent periods. This volatility constrains margin predictability for manufacturers and elevates the strategic importance of feedstock hedging, vertical integration and supplier risk management.
-
Trade and tariff friction. Import duties and trade remedies on PLA-origin inputs and finished goods are reshaping sourcing calculus for global buyers, prompting many to reassess nearshoring, regional manufacturing footprints and tariff engineering opportunities.
What the Report Delivers — Practical, Executable Outputs
PW Consulting’s report was designed as a decision tool for executives, not an academic exercise. Its deliverables are oriented around executable choices and include:
-
A validated market-sizing model and forward-looking projections (top-line and scenario-based) that translate macro demand into volume and revenue implications across realistic adoption pathways.
-
Actionable supplier and resin-sourcing playbooks, including a benchmarked supplier risk matrix and contract structures that lock desirable resin grades while mitigating price exposure.
-
Product development and manufacturing checklists covering extrusion parameters, grade selection, compostability certification, and testing protocols for foodservice and retail applications.
-
Regulatory compliance roadmaps for key jurisdictions, with a prioritized checklist of certification steps and consumer-claims guidance to avoid greenwashing risks.
-
Commercial go-to-market strategies and pricing sensitivity models that map margin impacts under alternative feedstock and tariff assumptions.
-
M&A and partnership screening criteria, together with a short-list of strategic moves for incumbents and new entrants (JV templates, licensing approaches, and contract-manufacturing options).
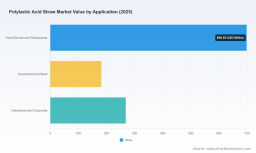
To preserve the strategic value of the report for our clients, detailed regional and application-level splits are published only in the full report and the accompanying Excel model. This preview highlights the analytical thrust and decision levers without reproducing the fine-grained data tables.
Competitive Landscape — How Leading Players Are Shaping the Market
The PLA straw ecosystem is characterized by an upstream layer of resin producers and a downstream layer of converters, brand owners and foodservice suppliers. Several players warrant close attention for the strategic signals they send to the market:
-
TotalEnergies Corbion — With Luminy PLA grades tailored for straw extrusion, the company is pushing performance differentiation (improved clarity and strength). The strategic implication: buyers will increasingly source by grade characteristics, not just by supplier name, creating opportunities for long-term grade-specific supply agreements.
-
NatureWorks — Capacity expansion initiatives (notably at its North American sites) signal confidence in sustained demand for compostable products. For buyers, timing of offtake contracts and access to expanded capacity will be a negotiation lever in 2026.
-
Biome Bioplastics , Biopac India , Ecor Products , Green Straw and Vegware — These converters and branded suppliers emphasize certification, end-use performance, and route-to-market specialization (foodservice vs retail). Their presence underscores an increasingly bifurcated market: one axis focused on performance/industrial compostability, the other on cost-led, mass-market alternatives.
Our competitive analysis shows a market where no single group dominates; instead, competitive advantage is earned through grade ownership, certification credentials, and integrated supply solutions. In practice, this means consolidation pressure in the middle of the value chain and strategic partnerships between resin makers and converters to deliver end-to-end validated product claims.
Strategic Implications for 2026
-
Procurement and hedging: Firms should move from spot-buying to multi-year offtakes with performance clauses. Consider feedstock-linked pricing or blended purchasing to smooth volatility and protect margins.
-
Product differentiation: Invest in grades that deliver clear advantages in mechanical performance and thermal stability. For foodservice customers, certification to recognized industrial composting standards is table stakes; for retail, durability and sensory parity with legacy plastic are differentiators.
-
Manufacturing footprint strategy: Reassess regional footprints in light of tariffs and logistics. Where duties materially raise landed costs, nearshoring or regional tolling arrangements can preserve competitiveness.
-
Regulatory posture and claims: Establish an audit-ready certification pipeline to avoid consumer and regulator pushback. Transparent labelling, third-party verification and conservative environmental claims reduce litigation and reputation risks.
-
M&A and partnerships: Buyers should prioritize deals that secure grade access, proprietary formulations or certified supply chains. Conversely, investors should prefer targets with validated performance claims and diversified end markets.
Scenario Framework — Preparing for Three Plausible Paths
For pragmatic planning, our model uses three scenarios driven by policy enforcement intensity, feedstock price trajectories and adoption rates among foodservice/retail customers. Under the base scenario — consistent with the 12% CAGR outlook — the market supports sustained premiumization of high-performance grades and a widening gap between certified suppliers and low-cost commodity peers. In an upside regulatory acceleration scenario, premium certified grades capture an outsized share of demand and vertical integration becomes a priority. Under a downside scenario with slower policy enforcement and prolonged feedstock inflation, cost competition intensifies and nearterm consolidation among converters accelerates.
Each scenario in the full report is paired with trigger points and recommended strategic moves (e.g., when to sign long-term resin contracts, when to accelerate CAPEX, when to pursue partnerships vs M&A). This enables leaders to convert observables (policy announcements, feedstock price inflection, capacity online dates) into actionable decisions.
How to Use the Full Report to Execute in 2026
-
Run the included Excel model in-house with your procurement and finance teams to stress-test price and volume assumptions against your product mix.
-
Use our supplier scorecard to shortlist partners for strategic offtakes and co-development projects; the scorecard ranks suppliers on grade availability, capacity timelines, certification footprint and contractual flexibility.
-
Adopt the compliance playbook to align product claims, packaging and end-of-life instructions with jurisdictional requirements, minimizing market access friction.
-
Leverage our M&A screening criteria to evaluate targets that provide immediate access to differentiated grades or certification credentials.
Note: the full PW Consulting report contains the granular regional and application-level splits, price-sensitivity worksheets, supplier-level benchmarking and downloadable decision dashboards that underpin the recommendations summarized here. We intentionally reserve those detailed tables for the full publication to preserve their strategic utility for subscribers and clients.
Concluding Recommendation
2026 will be a year of execution for firms in the PLA straw value chain. Companies that lock access to performance-differentiated grades, adopt robust feedstock risk mitigations, and align certification and claims with evolving regulatory expectations will secure durable competitive advantage. The market’s projected mid-term growth trajectory provides attractive value for investors and incumbents who move decisively — but success will hinge on the quality of execution, not simply on participation.
For decision-makers seeking to convert insight into action, PW Consulting’s full report supplies the quantitative models, supplier analytics and tactical playbooks necessary to set 2026 strategy with confidence. Visit our report page to download the complete study and receive the companion Excel model and implementation guide.
For detailed analysis of this topic, please visit the official page: Worldwide Polylactic Acid Straw Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com