

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Parallel Weld Heads Market (Base Year 2025) to Hit USD 294.06 Million by 2032 at 6.24% CAGR — Asia Pacific Tops with USD 82.56M as Air‑Actuated Heads and Battery Tab Welding Drive Growth

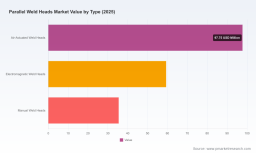
Worldwide Parallel Weld Heads Market: Strategic Insights for 2026 Decision-Making
Executive summary
As manufacturers accelerate electrification, miniaturization, and high-volume micro-joining, parallel weld heads have moved from a niche engineering convenience to a strategic component in modern assembly lines. PW Consulting’s latest market study—anchored on a 2025 base year and a 2026–2032 forecast horizon—quantifies this shift. The global market for parallel weld heads was valued at approximately USD 192.5 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 6.24% through 2032, reaching a market size in the high hundreds of millions by the end of the forecast period.
Worldwide Parallel Weld Heads Market
This release is intended as a concise executive primer for C-suite leaders, supply chain managers, and product strategy teams evaluating capex, sourcing, and M&A choices in 2026. It outlines why parallel weld heads matter strategically, the near-term risks that will shape procurement and design decisions, and the operational levers companies should prioritize. To maintain the report’s role as a commercial research product, detailed segment-level tables and granular regional/application splits are intentionally withheld in this preview—interested parties will find the full datasets and interactive models on the report landing page.
Worldwide Parallel Weld Heads Market
Why parallel weld heads are a 2026 strategic priority
-
Enabler of electrification and micro-joining: Parallel weld heads are central to battery tab welding, micro resistance spot welding, and assemblies where single-sided access or tight geometry constraints exist. As battery pack production scales and sensor/electronics assemblies proliferate, investment in parallel welding capability becomes a competitive necessity rather than a specialty option.
Worldwide Parallel Weld Heads Market -
Productivity and repeatability imperatives: High-throughput operations require weld heads that deliver consistency across millions of cycles. Suppliers who pair mechanical design with control firmware and fixture integration provide measurable yield improvement—an increasingly important bargaining chip in supplier selection.
-
Installed-base service economics: Aftermarket support (spares, electrodes, calibration) is a significant and growing margin pool. Firms that architect for serviceability and instrumented diagnostics can convert capital sales into annuity-style revenue streams.
-
Supply chain sensitivity: The industry’s exposure to copper and alloy price volatility, longer lead times for specialty alloys, and consumable shortages means procurement strategies (safety stock, hedging, multi-sourcing) directly affect production continuity and unit costs.
What PW Consulting’s report delivers (practical, executable content)
-
Value-driven market model: A transparent topo-down and bottom-up model with 2020–2025 historical calibration and 2026–2032 scenario outputs. The model is parameterized for alternative demand trajectories and raw-material-price shock scenarios so decision-makers can stress-test capital plans.
-
Supplier scorecards and technology maps: Comparative assessments of the leading OEMs and specialist distributors across product families (pneumatic, electromagnetic, motorized, manual) that highlight differentiation in precision, force range, integration support, and service footprint.
-
Operational playbooks and checklists: Integration templates for cell design, electrode lifecycle management, and process qualification tailored to battery pack, medical device, and microelectronics workflows—aimed at shortening time-to-volume and improving first-pass yield.
-
Procurement and risk tools: Recommended contract structures, a supplier shortlisting framework, and inventory hedging protocols addressing raw-material volatility and critical-lead-time items (electrodes, actuator assemblies, specialty cabling).
-
Go-to-market and M&A guidance: Prioritized white-space maps (qualitative by region and application), partnership archetypes, and transaction frameworks for strategic acquisitions that capture aftermarket and systems-integration value.
Competitive landscape — who matters and why
The parallel weld head ecosystem features a mix of specialized OEMs, integrators, and distributors. Our analysis identifies several strategically important players—each representing different routes to market and capability stacks that buyers should evaluate through both technical and commercial lenses.
-
Sunstone Welders — a design-focused OEM with product lines optimized for micro resistance spot welding and battery tab workflows. Sunstone’s emphasis on same-side electrode access and compact mechanical packaging makes it a frequent first choice for battery module OEMs and laboratories transitioning to production. Recent product comparisons and bench-testing content indicate Sunstone is actively framing its products within complete micro-welding workflows.
-
AMADA WELD TECH — a broad-line resistance welding supplier with deep application engineering resources. AMADA’s portfolio spans pneumatic to motorized and servo-actuated solutions, making it attractive to Tier-1 integrators requiring standardized, scalable systems. Their strength lies in configuration breadth and cross-application credibility across electronics, medical, and automotive sectors.
-
TJ Snow — operates as a key distributor and integrator for specialist parallel weld head lines, positioning itself as a systems enabler for battery pack manufacturing. For buyers prioritizing turnkey readiness and local support, channel partners like TJ Snow reduce technical integration risk.
-
Advanced Integrated Technologies (A‑I‑T) — focuses on ultra-low-force electromagnetic micro weld heads that are purpose-built for precision micro-joining. Their offerings are relevant to customers prioritizing delicate assemblies, such as medical sensors and fine-wire interconnects, where control over contact force and repeatability is paramount.
-
C‑Welding — a distributor network that extends OEM reach into aerospace, automotive, electronics, and medical device manufacturing. Distributors like C‑Welding are often the bridge for small-to-mid-size manufacturers who need local testing, spares, and rapid on-site response.
Strategic takeaways: the vendor landscape is characterized by product specialization combined with distribution partnerships. Buyers will need to weigh OEM innovation against integrator service capabilities, and prioritize suppliers that can demonstrate measurable uptime and electrode lifecycle economics.
Market dynamics, risks, and 2026 tactical responses
-
Raw material volatility: Copper and specialty alloy price swings have impacted procurement and cost forecasting across the resistance welding value chain. For 2026, manufacturers should incorporate raw-material sensitivity bands into capital budgeting, pursue dual sourcing for critical consumables, and evaluate strategic inventory policies for electrodes and contact caps.
-
Lead time and supply constraints: Extended lead times for specialty components and coating processes are already influencing project schedules. Tactical responses include qualifying alternate electrode coatings, modularizing actuator assemblies to simplify repairs, and locking long-lead items earlier in the project lifecycle.
-
Precision and regulatory demands: Automotive, aerospace, and medical customers increasingly demand documented repeatability and process traceability. Weld heads that integrate sensing for force, displacement, and energy delivery—plus digital logging—provide competitive differentiation for suppliers and risk mitigation for OEMs.
-
Application-driven technological choices: Parallel gap (series) welding remains the technique of choice where single-sided access is required. Strategic product decisions should therefore be grounded in a clear mapping from part geometry and materials to weld head actuation technology (pneumatic vs. electromagnetic vs. servo/motorized).
How enterprises should use this research in 2026
-
Capital planning: Time capex to coincide with the maturation of suppliers’ field-proven designs and to capture favorable procurement windows when raw-material price volatility stabilizes.
-
Supplier selection: Use a bifurcated approach—partner with an OEM for technology roadmap alignment and a local integrator/distributor for rapid deployment and aftermarket support.
-
Design for assembly: Incorporate welding constraints early in product design cycles (electrode access, fixturing provision, heat management) to avoid late-stage rework and qualification delays.
-
Service and aftermarket strategy: Capture higher lifetime value by investing in remote diagnostics, consumable subscription models, and structured training for in-house maintenance teams.
-
M&A and partnerships: Consider bolt-on acquisitions that deliver field service capability, consumable manufacturing, or regional distribution networks to accelerate go-to-market and aftermarket capture.
Conclusion and next steps
Parallel weld heads are transitioning from specialist tooling to a strategic enabler in high-growth industrial segments. PW Consulting’s analysis shows a stable growth trajectory with mid-single-digit CAGR through the end of the forecast period, underpinned by electrification and micro-joining demand. For executive teams planning 2026 investments, the core recommendation is to treat welding capability as a systems decision—one that combines mechanical design, control strategy, consumables sourcing, and aftermarket economics.
For readers ready to operationalize these insights, the full report contains detailed segment tables, scenario-model downloads, supplier scorecards, and integration playbooks. These resources are designed to turn market intelligence into executable choices—from tender design and supplier contracts to M&A screening and capex phasing. Visit our report page to access the complete dataset, interactive models, and a downloadable executive briefing tailored to your sector.
For detailed analysis of this topic, please visit the official page: Worldwide Parallel Weld Heads Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com