

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Multi‑Gigabit Switches Market to Grow from USD 7,280 Million in 2025 at 18.52% CAGR, Reaching USD 23,915.12 Million by 2032

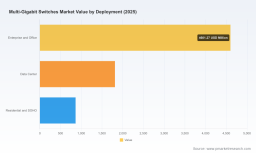
Worldwide Multi-Gigabit Switches Market: Strategic Imperatives for 2026 — PW Consulting Preview
PW Consulting’s latest market research — the Worldwide Multi-Gigabit Switches Market report — provides a forward-looking playbook designed to inform high-stakes infrastructure and sourcing decisions in 2026. Built on a 2025 base and a 2026–2032 forecast horizon, the study models demand across enterprise, edge, and data center environments and quantifies a clear growth runway: the market rises from USD 7,280.0 Million in 2025 to an anticipated USD 23,915.12 Million by 2032, reflecting a compound annual growth rate (CAGR) of 18.52%. This preview highlights the report’s strategic value without publishing the granular segment-level datapoints reserved for subscribers.
Worldwide Multi-Gigabit Switches Market
Why 2026 is an inflection year for multi-gigabit networking
-
Converging technology trends are accelerating multi-gig adoption. Wi‑Fi 7, higher-power PoE++ for AI-driven surveillance and access points, and persistent demand for low-latency uplinks in hybrid work models are moving organizations away from legacy 1GbE boundaries.
Worldwide Multi-Gigabit Switches Market -
Infrastructure economics are shifting. Data center shell-and-core construction costs are edging higher, and electricity is a dominant portion of operating expense; these dynamics force buyers to weigh CAPEX upgrades against long-term OPEX implications when choosing switch platforms and architectures.
Worldwide Multi-Gigabit Switches Market -
Supply-chain and regulatory volatility matter. Raw-material and fiber deployment cost outlooks indicate renewed pressure on rollout economics in 2026, while recent changes in U.S. net neutrality policy create asymmetric opportunities and risks for service providers and large enterprise networking buyers.
High-level findings every CIO and VP of Infrastructure should bookmark
-
Market trajectory: Robust expansion through 2032 — the multi-gigabit switches market is on a sustained growth path that will reshape refresh cycles, vendor roadmaps, and procurement cadence.
-
Concentration and competitive posture: Market concentration metrics show the top three and five vendors account for a majority share, signaling both entrenched incumbency and meaningful opportunities for specialist and regional players to capture niche use cases.
-
Product mix is shifting: Buyers are increasingly prioritizing multi-speed flexibility, integrated PoE power budgets for AI/IoT endpoints, and uplink bandwidth options that align with edge-to-cloud topologies.
-
Cost of ownership is the new battleground: Energy consumption, cooling, and lifecycle modularity (upgradability of optics and line cards) are as decisive in vendor selection as raw per-port pricing.
Competitive landscape — capabilities and strategic implications
-
Cisco Systems — Enterprise-grade breadth and long-term platform roadmaps make it the default choice for large campus and blended campus/datacenter deployments. Strategy for buyers: leverage Cisco’s ecosystem for integration benefits, but pressure vendors on modular upgrade economics and advanced telemetry licensing.
-
Arista Networks — Strength in high-performance 10G+ switching for cloud and hyperscale environments positions Arista as a primary option for spine/leaf and performance-sensitive fabrics. Strategy: evaluate Arista where low-latency and programmability justify premium pricing.
-
Juniper Networks — A balanced play across carrier and enterprise verticals with routing/switching integration advantages. Strategy: consider Juniper for unified control-plane scenarios and where MPLS/segment-routing interoperability is required.
-
Hewlett Packard Enterprise (Aruba) — Strong campus orientation with Aruba CX series emphasizes manageability and wireless-wireline convergence; attractive for organizations prioritizing a single-vendor experience for wireless and wired infrastructure.
-
Ubiquiti, NETGEAR, TP‑Link, QNAP, D‑Link — These vendors drive price-performance at the SMB/prosumer and edge tiers. Recent product rollouts from QNAP and D‑Link illustrate how lower-cost 2.5G/5G/10G options are blurring the lines of capability between consumer-grade and commercial switches. Strategy: use these suppliers for rapid, low-cost edge refreshes but validate management and lifecycle support for larger rollouts.
-
Specialists and industrial vendors (TRENDnet, Omnitron, Lantronix, PLANET, Zyxel, EnGenius) — Focused portfolios deliver hardened designs, extended temperature ranges, and higher PoE budgets for industrial, surveillance, and transportation deployments. EnGenius’s 2025 launch of a Layer 2+ multi-gig PoE++ product illustrates the intersection of Wi‑Fi 7 readiness and AI surveillance requirements.
Recent market activity that matters to procurement calendars
-
Product introductions targeting Wi‑Fi 7 and PoE++ workloads have proliferated among both mainstream and specialist suppliers — expect refreshed product lines and aggressive mid-cycle pricing through 2026.
-
Vendors are increasingly segmenting firmware and management features into tiered offerings; buyers should map feature entitlements to multi-year TCO rather than initial sticker price.
What the PW Consulting report gives you — practical, actionable deliverables
-
Decision frameworks and procurement playbooks: A step-by-step buyer’s guide for vendor shortlisting, RFP construction, PoE power budgeting, port-speed planning, and migration windows optimized for 2026 capital cycles.
-
Dynamic TCO models: Configurable templates that incorporate CAPEX, energy/OPEX, cooling impacts, and optics refresh schedules so you can stress-test scenarios under different electricity cost and data center build-cost assumptions.
-
Vendor benchmarking and negotiation cushions: Comparative profiles and negotiation levers aligned with feature sets, warranty terms, and lifecycle upgrade paths — designed to reduce procurement friction and manage total lifecycle spend.
-
Risk and compliance register: Practical mitigations for raw-material inflation, fiber deployment cost spikes, and regulatory shifts affecting service providers and large enterprise buyers.
-
Use-case playbooks: Ready-to-execute architectures for campus Wi‑Fi 7 rollouts, AI surveillance and PoE++ deployments, SMB edge refreshes, and spine-leaf data center designs — each with configuration checklists and staging considerations.
Deployment scenarios — how to translate the forecast into rollout decisions
-
Campus and Enterprise: Prioritize modular switches that scale uplink capacity without full-chassis replacement; map PoE budgets to anticipated AI/IoT growth rather than current device counts.
-
Edge and SMB: Favor low-cost multi-gig variants with simplified management for rapid deployment, but include a support-path clause in procurement to preserve future scalability.
-
Data Center: For spine/leaf fabrics, ensure vendor roadmaps accommodate 10G+ uplink aggregation and optics standardization to avoid stranded investments as traffic profiles evolve.
-
Industrial/OT: Validate hardware-level robustness and PoE temperature derating. Specialist providers offer hardened options that justify premium in non-office environments.
Decision framework for executives in 2026 — five immediate actions
-
Run a demand heatmap: Identify which business units will require increased uplink or PoE capacity in the next 12–24 months and align procurement cycles accordingly.
-
Incorporate energy sensitivity into vendor evaluations: Use the report’s TCO templates to simulate electricity-driven OPEX scenarios given current industry data on data center power spending.
-
Negotiate modular options and trade-in paths: Secure contractual language that reduces refresh risk and clarifies optics/line-card upgrade pricing.
-
Assess regulatory exposure: For service providers and large campus operators, model business-impact scenarios stemming from recent regulatory shifts.
-
Plan staged rollouts to capture price declines: Use pilot deployments to validate vendor claims and reserve budget for accelerated deployments if fiber and equipment costs stabilize.
Why PW Consulting’s report is indispensable for 2026 strategy
This report combines a robust historical base (2020–2025), a clearly stated base year (2025), and a granular forecast period (2026–2032) with proprietary demand models, vendor scorecards, and scenario stress-testing tools. It synthesizes market sizing, competitive concentration metrics, and forward-looking trend analysis into operational guidance for CIOs, procurement leads, and infrastructure architects. While this preview summarizes the strategic implications, the full report contains the detailed segment-level intelligence, vendor scorecards, downloadable TCO models, and executable RFP language that teams need to move from planning to procurement.
Next steps
For organizations preparing capital and operational plans in 2026, the right time to act is now: align budgets to anticipated growth vectors, stress-test energy and build-cost sensitivity assumptions, and engage vendors with a clear roadmap for modular upgrades. PW Consulting’s full Worldwide Multi‑Gigabit Switches Market report delivers the datasets, scenario models, and commercial playbooks that translate forecasted market momentum into defensible sourcing decisions. Access the full report to obtain the granular segmentation, vendor worksheets, and downloadable tools referenced in this preview.
For detailed analysis of this topic, please visit the official page: Worldwide Multi-Gigabit Switches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com