

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Picrorhiza Extract Market Set to Reach USD 80.6 Million by 2032, Expanding at a 6.42% CAGR (2026–2032)
By pmarketresearch, 2026-07-15
Worldwide Picrorhiza Extract Market — Strategic Outlook for 2026
PW Consulting’s latest market brief on the Worldwide Picrorhiza Extract Market provides senior executives, procurement leads, R&D heads and investors with a purpose-built strategic compass for 2026. Drawing on a multi‑year historical series, forward-looking scenario modeling and direct supplier intelligence, the report converts a technically complex specialty botanicals market into high‑conviction actions — while reserving full granularity to our published study to preserve commercial value.
Worldwide Picrorhiza Extract Market
Market trajectory at a glance
The Picrorhiza extract market has moved from niche to a structurally growing specialty segment. Our base-year series shows the global market expanding from USD 34.62 Million in 2020 to USD 48.65 Million in 2025, with a projected market value of USD 52.93 Million in 2026. Under the report’s central forecast, the market grows at a compound annual growth rate (CAGR) of 6.42% through the 2026–2032 horizon, reaching roughly USD 80.6 Million by 2032.
Worldwide Picrorhiza Extract Market
These topline dynamics reflect a combination of demand-side uplift (renewed interest in herbal actives across nutraceutical, pharmaceutical and personal care applications) and constrained supply driven by geography, regulation and raw‑material pressure. For decision-makers, the headline numbers are an early indicator: the market is sufficiently large to justify strategic engagement but remains concentrated enough to reward targeted sourcing and premiumization strategies.
Worldwide Picrorhiza Extract Market
Why 2026 is an inflection point for corporate planning
- Regulatory pressure and conservation constraints: Picrorhiza kurroa has been regulated internationally for decades and remains subject to trade restrictions and national controls designed to protect wild populations. These constraints are reshaping supply chains and accelerating demand for cultivated, certified feedstocks.
- Supply gap and sourcing scarcity: Historical industry reporting shows that annual raw‑material demand has outstripped sustainable supply, creating a structural supply deficit that is catalyzing organized cultivation and upstream investments.
- Scientific momentum: Recent publications (including a January 2026 preprint identifying Picrorhiza kurroa as a potential prebiotic when combined with Lactobacillus fermentum) are expanding application avenues and value‑capture opportunities beyond traditional uses.
For executives, 2026 is when strategic choices made today — secure offtake agreements, cultivation investments, or product innovation partnerships — will materially influence market position for the remainder of the decade.
What the PW Consulting report delivers — practical, decision‑ready content
- Transparent market sizing and validated growth scenarios (historic 2020–2025 series and 2026–2032 forecasts).
- Supply‑chain heatmaps and risk scoring for sourcing geographies, processing nodes and logistical pinch points.
- Regulatory and conservation compliance matrices, including trade control impacts and actionable mitigation steps.
- Go‑to‑market playbooks for product teams: formulation windows, claim substantiation pathways and prioritization of pipeline opportunities.
- Vendor intelligence with operational profiles, capability assessments and commercial negotiation levers.
- M&A and partnership screening framework: valuation levers, integration risks and sample term structures for offtake/anchor investments.
Each deliverable is focused on implementation: checklists, template term sheets and scenario‑driven recommendations that procurement, R&D and corporate strategy teams can apply in Q1–Q3 2026.
Competitive landscape — tactical implications from supplier intelligence
The Picrorhiza extract supply base is regionally concentrated among specialist botanical firms, with a meaningful presence of India‑ and China‑origin producers. Our vendor map identifies several active commercial suppliers and their operational profiles, including manufacturers and exporters emphasizing organic standards, bulk B2B supply, and standardization capabilities.
- Established Indian producers are differentiated by export scale, organic and conventional supply lines, and experience in serving nutraceutical value chains. Their strengths include bulk manufacturing, compliance to international buyer expectations, and familiarity with the Himalayan sourcing environment.
- Chinese producers provide complementary supply options, typically serving formulators with cost‑competitive offerings and regional logistics advantages for Asian buyers.
- Smaller specialists and contract exporters often occupy niches (industrial powders, specific packaging formats, short lead‑time lots) and can be attractive partners for flexible sourcing and toll manufacturing.
Market concentration metrics highlight a fragmented market: the top three and top five suppliers together account for a minority share, which means there is room for new entrants and for buyers to diversify. This fragmentation, paired with material supply constraints, creates a window for commercial arbitrage — premium pricing for certified, traceable supply and consolidation opportunities for strategic acquirers.
Supply chain and sourcing risks — what to watch and act on now
- High‑altitude sourcing constraints: Picrorhiza is a high‑altitude species whose primary economic parts are roots and rhizomes harvested in sensitive Himalayan ecosystems. Transport, batch traceability and seasonality are non‑trivial operational risks.
- Wild‑collection regulation: International and national controls — including long‑standing listings designed to curb overharvest — increase compliance cost and can limit volumes unless cultivated sources are developed and certified.
- Quality and standardization variability: Differences in raw material handling, extraction methods and standardization mean that ingredient quality can vary significantly between suppliers. Buyers face the choice between locking in premium, certified supply or managing a broader, lower‑cost supplier pool with more quality gating.
Mitigants for 2026: build multi‑tier supply strategies (short‑term spot, medium‑term offtake, long‑term cultivation partnerships), insist on chain‑of‑custody documentation, and prioritize suppliers that can scale cultivated output in line with conservation policies.
Product and R&D opportunities
Recent scientific developments are the most actionable signal for product teams. Independent research demonstrating prebiotic potential when Picrorhiza is formulated with specific probiotic strains opens a new product class — synbiotic herbal formulations — that can attract premium positioning in dietary supplements and specialized clinical nutrition. Alongside this, ongoing cultivation research demonstrates pathways for scaling sustainable feedstock that meet both conservation and commercial needs.
Recommended R&D moves for 2026:
- Prioritize bioactivity and formulation work that validates target claims (e.g., prebiotic, hepatoprotective adjunctions) under realistic processing conditions.
- Design clinical or pilot human studies to convert novel mechanistic findings into branded health claims acceptable in key regulatory jurisdictions.
- Explore co‑development partnerships with suppliers who can guarantee traceable, standardized extract batches for reproducible studies.
Regulatory and sustainability playbook
Regulatory realities are not a distant compliance exercise; they are a commercial lever. Picrorhiza’s listing under international trade control mechanisms and national restrictions in source countries both raise the bar for documentation and create a de‑risking premium for certified cultivated material. Corporates should:
- Develop a compliance matrix for each target market, mapping required documentation, permitted claims and labeling constraints.
- Create a sustainability procurement policy that balances conservation commitments with secure supply, including community benefit agreements and traceability audits.
- Use certification and third‑party stewardship as differentiation in B2B negotiations: certified cultivated supply can command better commercial terms and faster regulatory acceptance.
Investment, M&A and partnership signals
For 2026, the most attractive corporate moves are pragmatic and risk‑calibrated:
- Secure midstream exposure through offtake agreements and minority investments with option‑to‑acquire clauses tied to cultivation scalability.
- Consider bolt‑on acquisitions of extraction capabilities or packaging specialists to reduce time‑to‑market for new formulations.
- Enter strategic partnerships with farmer cooperatives or upstream cultivators to create exclusive supply corridors that align with sustainability commitments.
These choices preserve optionality while capturing upside as demand validates premium positioning and new applications mature.
How PW Consulting’s report supports 2026 decisions
Our report combines rigorous market modeling (historic 2020–2025 series and 2026–2032 scenario outputs) with operational vendor intelligence, regulatory de‑risking playbooks and transaction frameworks. It is structured to be directly usable by procurement RFPs, M&A diligence and product development roadmaps. To respect the “teaser” principle integral to corporate research, we present the full methodology, all model outputs and subsegment breakouts in the subscription report available on our site — these include the granular regional and application splits, supplier scorecards and downloadable commercial templates that informed the strategic recommendations summarized here.
Next steps — where to focus in Q1–Q3 2026
- Run parallel supply scenarios: secure short‑term cover with vetted suppliers while negotiating medium‑term cultivated offtake.
- Begin targeted formulation pilots leveraging the latest prebiotic data and lock in small, traceable batches for reproducible testing.
- Embed sustainability clauses in procurement contracts and pilot community‑based cultivation projects to de‑risk regulatory exposure.
- Use competitive fragmentation to negotiate favorable commercial terms with specialist suppliers, while monitoring consolidation opportunities for strategic acquisition.
Picrorhiza extract is an example of a specialty botanical where scientific novelty, ecological scarcity and regulatory complexity intersect to create both risk and differentiated commercial value. PW Consulting’s market brief equips leaders with the analytic lens and practical tools needed to convert this dynamic into defensible market positioning in 2026 and beyond. For the full dataset, supplier dossiers, and downloadable templates that underpin the recommendations above, please consult the full report on our website.
For detailed analysis of this topic, please visit the official page: Worldwide Picrorhiza Extract Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dragon Blood Market Poised to Top USD 379.39 Million by 2032, Growing at a 5.64% CAGR
By pmarketresearch, 2026-07-15
Dragon Blood Market 2026 Strategic Preview — What Corporate Leaders Must Know Now
PW Consulting’s Dragon Blood Market research is the definitive strategic briefing for executives preparing commercial, procurement, and R&D decisions in 2026. This preview summarizes why Dragon Blood (botanical resins and extracts commonly marketed as “Dragon’s Blood”) will be an active battleground for product differentiation, supply-chain resilience, and regulatory positioning over the next planning cycle — and how our full report turns those macro realities into executable priorities. The analysis below highlights high-level findings and operationally oriented recommendations while intentionally withholding the granular segment tables and proprietary split data included in the paid report.
Dragon Blood Market
Market at a glance
Dragon Blood is no longer a boutique ingredient: the total market expanded steadily during the 2020–2025 baseline and reached USD 258.4 Million in our 2025 base year (USD, Million). Our forecasts — underpinned by demand growth in personal care actives, wound-care formulations, and select food & beverage niches — project a compound annual growth rate (CAGR) of 5.64% across the 2026–2032 horizon, taking total market size toward the high hundreds of millions by 2032.
Dragon Blood Market
Two technical implications for decision-makers follow immediately. First, predictable overall expansion creates capacity for new product launches and for upstream investments in standardized extract technologies. Second, growth is uneven across use-cases, regulatory regimes, and sourcing geographies — a fragmentation that rewards targeted strategic initiatives rather than one-size-fits-all plays.
Dragon Blood Market
Why 2026 is an inflection year
-
Regulatory momentum: Recent approvals and regulatory clarifications — including a notable FDA approval for a standardized Dragon Blood wound-care formulation — are accelerating clinical and therapeutic use cases. At the same time, U.S. regulatory categorization remains fragmented (cosmetic, supplement, or medical product), constraining the exploitable market for some players and elevating the value of clear regulatory pathways.
-
Sourcing constraints and price volatility: Raw resin extraction remains manual and dependent on slow-growing species across Amazonian and Asian supply basins. Spot price volatility is material — our sector analysis shows annualized variations that require procurement hedging strategies and dynamic pricing approaches.
-
Sustainability premiums: Certified-organic and ethically sourced Dragon Blood capture meaningful price premiums in the market when tied to harvester welfare and agroforestry yields. Investments in supplier development projects have demonstrated sizable yield improvements in pilot geographies, increasing both supply reliability and commercial value.
-
Market structure: Concentration metrics reveal a market with established incumbents but clear white space. The leading few firms hold meaningful share, yet the breadth of suppliers — from high-volume resin merchants to specialized standardized-extract manufacturers — creates strategic pathways for new entrants and vertical consolidations.
What the PW Consulting Dragon Blood Market Report delivers (practical, operational content)
Our full report is designed as a tactical playbook for 2026 decision windows. It contains:
-
Actionable market-sizing and demand-forecast models with downloadable sheets (TAM / SAM / SOM scenarios) calibrated to product category and regulatory pathway.
-
Supply-chain mapping and a sourcing-risk matrix that identifies single-point-of-failure suppliers, seasonality windows, and climate/agroforestry exposure.
-
Supplier scorecards and contract term templates (including suggested clauses for traceability, yield-sharing, and sustainability premiums).
-
Regulatory playbooks by jurisdiction covering likely classification, dossier requirements, and clinical pathways for therapeutic claims.
-
Commercial tools: price-sensitivity ladders, private-label vs. ingredient positioning decision trees, and product-development roadmaps (formulation, sensory optimization, and stability testing protocols).
-
M&A and partnership screening frameworks: a prioritized heatmap of targets and integration risks for value-accretive consolidation.
-
Scenario planning modules that stress-test supply shocks, certification roll-outs, and demand pivots across cosmetics, pharmaceuticals, and specialty food applications.
These elements are paired with practical templates and checklists so that teams can move from insight to pilot in weeks, not quarters.
Competitive landscape — what incumbents are doing
The market shows clear strategic archetypes among active players:
-
Ingredient specialists (e.g., established cosmetic actives suppliers) are packaging Dragon Blood as performance actives for antimicrobial and skin-repair claims, offering standardized extracts with INCI-labelled formulations tailored for formulators.
-
Botanical-extract manufacturers emphasize hydro-glycolic and glycerite formats optimized for sensory profiles and emollience — important for personal care adoption.
-
Bulk resin merchants in supplier-dense geographies continue to control raw material flows, providing scale but limited product differentiation.
-
Emerging standardized-extract producers and pharmaceutical-grade suppliers are pursuing clinical pathways and regulatory approvals that can unlock higher-margin therapeutic markets.
Representative players span that spectrum: established cosmetic ingredient houses focused on formulation-ready actives; experienced botanical extract firms with long heritage in hydro-glycolic processes; wholesale specialists exporting wild-harvested resin and private-label options; and regionally dominant suppliers scaling pharmaceutical-grade standardization. Notably, one regional manufacturer has obtained regulatory clearance for a wound-care product built on standardized Dragon Blood — a development that will recalibrate therapeutic demand assumptions and raise the bar for quality and traceability across the value chain.
Market concentration metrics indicate a moderate level of consolidation among the top firms, leaving space for mid-market scale-ups and targeted acquisitions to reshape share dynamics over the next 24 months.
Strategic imperatives for 2026 decision-makers
-
Procurement: Move from spot-buying to a blended strategy of multi-year supply agreements, seasonal call-off contracts, and spot exposure limits. Build a supplier development fund focused on yield improvement and traceability; these investments often deliver outsized supply security and can justify certified-organic premiums.
-
Product strategy: Prioritize two parallel product tracks — (1) sensory-driven personal care actives optimized for formulators (emollience, texture, preservation synergy); and (2) clinical-grade standardized extracts targeted at wound-care and therapeutic claims where regulatory clarity is improving.
-
Regulatory and quality: Establish a regulatory roadmap for each intended use-case early. For medical claims, invest in standardized extract platforms and clinical partnerships; for cosmetic claims, ensure robust safety dossiers and traceability that support claims without triggering medical classification.
-
Sustainability as differentiation: Integrate community-level sourcing partnerships and agroforestry projects into supplier contracts. Certified organic and ethical-sourcing narratives command meaningful premiums and reduce reputational risks.
-
Commercial go-to-market: Use tiered pricing that internalizes raw-material volatility. Co-develop exclusives or semi-exclusives with key formulators to lock in early adoption and justify premium pricing.
-
M&A and alliances: Target bolt-on acquisitions that deliver either standardized-extract capability or secure upstream supply. Consider revenue-sharing JV models with high-quality harvest cooperatives to control both cost and CSR outcomes.
90-day playbook — from insight to pilot
-
Days 1–14: Executive alignment workshop using the report’s scenario modules and supplier scorecards. Select priority use-cases and acceptable regulatory risk profiles.
-
Days 15–45: Rapid supplier audits and negotiation of pilot contracts, with conditional clauses for certification upgrades and yield-improvement milestones.
-
Days 46–90: Launch two product pilots (one cosmetic active, one clinical-grade prototype), finalize regulatory pathway mapping, and present a commercial pilot pricing schedule for channel testing.
Concluding perspective
For companies allocating budgets and attention in 2026, Dragon Blood represents an intersection of science, culture, and supply-chain complexity. The ingredient will reward organizations that combine disciplined procurement, regulatory foresight, and a sustainability-first approach to sourcing. PW Consulting’s full Dragon Blood Market report provides the granular segmentation, supplier-level data, and downloadable tools necessary to operationalize the recommendations summarized here — including the proprietary split tables and supplier evaluations that underpin bidding and M&A decisions.
To access the complete dataset, supplier scorecards, and the ready-to-run 90-day implementation templates, visit the PW Consulting Dragon Blood Market report page and request the enterprise version of the study — designed specifically for executive teams ready to convert market momentum into defensible advantage in 2026.
For detailed analysis of this topic, please visit the official page: Dragon Blood Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Nefopam Hydrochloride Market Poised to Reach USD 374.44 Million by 2032, Growing at a 5.5% CAGR
By pmarketresearch, 2026-07-15
Worldwide Nefopam Hydrochloride Market — Strategic Imperatives for 2026
Executive summary
PW Consulting’s latest Worldwide Nefopam Hydrochloride Market report (base year 2025, historical 2020–2025, forecast 2026–2032) synthesizes commercial, clinical and regulatory intelligence into an actionable roadmap for executives planning their 2026 strategies. The market has expanded from roughly USD 198 million in 2020 to about USD 257 million in 2025, and our modelling projects continued expansion through the forecast window with a compound annual growth rate (CAGR) of approximately 5.5%, reaching the low hundreds of millions by the early 2030s. These headline numbers understate important structural shifts—shifts this report teases and unpacks for boardrooms, corporate development teams and commercial leaders without divulging every granular split in this summary.
Worldwide Nefopam Hydrochloride Market
Why this report matters for 2026 decision-makers
- Timing and optionality: 2026 will be a pivotal year for companies seeking to convert clinical momentum into sustainable commercial access. A small number of supply and filing advantages will determine who captures premium value.
- Regulatory frontiers: Divergent regulatory pathways across geographies create selective market openings. The absence of an approved US marketing authorisation remains a strategic barrier for global expansion, while established authorisations and national formularies across Europe and other markets create differentiated access corridors.
- Concentration and sourcing risk: With a moderately concentrated supplier base (CR3 ~58.4%; CR5 ~74.2%), downstream manufacturers and formulation specialists must prioritise supply security and qualification of alternate API sources to avoid production disruption and pricing pressure.
- Clinical evidence is shifting positioning: Emerging randomized data and formulation patents are reshaping the value proposition versus opioid and multimodal analgesic regimens—presenting both commercial upside and regulatory complexity.
Market dynamics and near-term catalytic events
The market’s steady growth is being driven by three interacting vectors: clinical evidence evolution, formulation and IP activity, and payor positioning. Recent developments illustrate this dynamic:
Worldwide Nefopam Hydrochloride Market
- IP and formulation innovation: In February 2025, a new patent was granted for an optimized nefopam hydrochloride formulation intended for acute and chronic pain, with the patent-holder signalling plans for Phase 2 studies. Such assets change the competitive calculus by enabling differentiated dossiers and lifecycle strategies.
- Clinical outcomes informing use-cases: A randomized, placebo-controlled, double-blind trial published mid-2025 evaluated nefopam for analgesia after cardiac surgery—evidence that can expand perioperative use-cases if results are favourable to efficacy and safety endpoints.
- Formulary assessments and cost-positioning: National formulary updates in 2025 demonstrate how local cost- and positioning-decisions influence uptake, particularly where an authorised alternative analgesic class exists.
- Regulatory contours: Nefopam is not approved for marketing in the United States, a long-standing constraint on volume expansion in that market. Conversely, several European national authorisations and past EMA decisions (including regulatory waivers for paediatric investigations in defined combinations) create a patchwork that rewards targeted go-to-market plans.
- Opioid-sparing narrative: Meta-analyses and reviews report a meaningful opioid-sparing signal for nefopam when used in multimodal regimens—an important commercial message as health systems pursue opioid stewardship.
Competitive landscape — who matters and why
Competition in the nefopam value chain spans API producers, integrated generic manufacturers and specialty formulation players. The market’s measured concentration (CR3 ~58.4%; CR5 ~74.2%) indicates that a few players exert significant influence over price and availability. Key participants covered in the report include:
Worldwide Nefopam Hydrochloride Market
- Polpharma (Poland) — A certified API producer with GMP and dossier capabilities; a strategically positioned European supplier for companies seeking EU-compliant API sourcing.
- Global Calcium (India) — Export-oriented manufacturer of nefopam API serving both domestic and international buyers; a price-competitive option for formulators outside Europe.
- PMC Isochem (France) — Offers API with European-centric regulatory filings (CEP/COS, JDMF) and a portfolio attractive to companies prioritising continental compliance.
- Emcure, Micro Labs, Maiden Group (India) — Integrated manufacturers with formulation and commercial capabilities; positioned to convert API supply into branded and generic finished products, often with regional commercial networks.
- CF Pharma, PRG Pharma, Guangzhou Green Cross — Listed suppliers and regional producers that represent capacity diversity and incremental supply options.
- Taj Pharma (India) — Notable for finished-dose formulations in both injection and tablet forms, representing downstream commercialization and immediate market presence.
Strategic takeaways:
- Buyers and OEMs should prioritise dual-sourcing and supplier qualification protocols to mitigate concentration risk.
- Manufacturers with regulatory dossiers covering multiple jurisdictions hold disproportionate negotiating power; securing or partnering for these dossiers accelerates market entry.
- Filers with access to differentiated formulations or IP (patents, proprietary delivery systems) can defend premium pricing and create barriers to generic substitution.
What the report contains — practical, transaction-ready intelligence
Designed for immediate commercial and corporate-development use, the report combines quantitative forecasting with pragmatic tools executives need for 2026 actions. Highlights include:
- Market sizing and forecast models (2020–2032) with scenario analyses and sensitivity testing across price, volume and regulatory outcomes.
- Supply chain and capacity maps: validated list of API manufacturers, regulatory filing coverage (EDMF/ASMF, CEP/COS, JDMF) and capacity indicators, with supplier scorecards covering quality, compliance and commercial terms.
- Regulatory and reimbursement matrix: jurisdiction-level filing status, likely dossier gaps, and payer positioning intelligence to inform market access strategies.
- Clinical and evidence synthesis: trial-by-trial evidence tables, meta-analytic summaries (including analgesic and opioid-sparing endpoints), and implications for label expansion and guideline adoption.
- Commercial playbooks: go-to-market blueprints for branded entrants, generics players and API suppliers, including pricing benchmarks, margin models and tender-play templates.
- M&A and partnership candidate shortlist: valuation frameworks and compatibility matrices for buyers seeking bolt-on assets or upstream integration.
- Risk heatmaps and mitigation templates covering supply disruption, regulatory changes and competitive pricing shocks.
While this press summary outlines the instruments in our toolkit, the report contains the underlying granular segmentation, region-by-region projections and supplier-level intelligence that supports executable deals and market strategies.
Strategic playbook for 2026 — recommended actions by stakeholder
- API suppliers: Invest selectively in regulatory filings (CEP/COS, JDMF) to expand addressable markets; pursue commercial partnerships with downstream formulators to stabilise demand.
- Generic manufacturers / formulators: Lock in multi-year supply agreements and pursue modest formulation differentiation (e.g., injection delivery systems or modified-release tablets) to avoid pure commoditisation.
- Innovator / specialty players: Advance payer-focused evidence generation that pairs the opioid-sparing narrative with pharmacoeconomic models; leverage IP to negotiate premium positions in perioperative formularies.
- Private equity and corporate development: Target consolidation of complementary API capacity and dossier portfolios to capture scale and filing coverage; use scenario models from the report to value optionality related to trial readouts and reimbursement shifts.
- Payers and hospital systems: Sponsor pragmatic comparative-effectiveness studies linked to stewardship programmes; consider conditional contracting that rewards opioid-sparing outcomes.
How executives should use this research in 2026
Use the report as a decision-support engine across four immediate priorities:
- Prioritise supplier qualification and enter multi-year contracts where exposure to concentrated supply is material to production continuity.
- Align evidence-generation investments (post-authorisation trials, real-world studies) with formulary uptake targets and payor requirements specific to priority markets.
- Screen potential M&A targets using our supplier scorecards and concentration data to fast-track integration of dossier-strong assets.
- Run scenario stress tests (included in the report) to understand the financial impact of positive or negative clinical readouts, changes to national formulary positions, and new entrants.
Conclusion — why now
The nefopam hydrochloride market is no longer a static generic niche. Incremental clinical evidence, formulation IP and concentrated supply create both commercial risk and opportunity. For 2026, organisations that combine disciplined supply security, targeted regulatory filings, payer-centred evidence and selective deal-making will capture disproportionate value as the market continues its modest but steady growth at an estimated 5.5% CAGR. PW Consulting’s full report provides the granular segmentations, supplier-level analytics and transactional playbooks required to convert this forecasted growth into profitable, de-risked strategies.
Next steps
PW Consulting has prepared an executive briefing package and client workshops to translate findings into a 90-day action plan. To access the full dataset, supplier scorecards, and scenario models referenced here (including the region and application-level detail intentionally excluded from this summary), please visit our report page or contact your PW Consulting account director for immediate access and a tailored briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Nefopam Hydrochloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Sound Cards Market Valued at USD 517.25 Million in 2025, Poised for 5.88% CAGR to USD 771.6 Million by 2032
By pmarketresearch, 2026-07-15
Worldwide Sound Cards Market 2026 Strategic Outlook: Navigating Growth Amid Supply Chain Realities
PW Consulting’s latest Worldwide Sound Cards Market report — anchored on a 2025 base year and projecting through 2032 — delivers a decision-grade, strategy-first analysis designed for executives planning 2026 investments. The market has moved from a mid-single-hundred million-dollar base in 2020 to a stronger position by 2025, and our model forecasts continued expansion through 2032. Across the 2026–2032 forecast window the market is projected to grow at a compound annual growth rate (CAGR) of 5.88%, with the total market size reaching an estimated USD 771.6 Million by 2032. These headline figures frame a market that is maturing but far from saturated — offering differentiated opportunities for product innovators, channel specialists, and strategic acquirers.
Worldwide Sound Cards Market
Why this report matters to 2026 corporate strategy
- Tactical visibility into growth corridors: Our modeling quantifies a clear, steady expansion path and isolates where incremental revenue and margin expansion are most plausible over a seven-year horizon.
- Supply-chain and policy foresight: The report synthesizes recent shifts in semiconductor export controls, tightening passive component lead times, and tariff uncertainty that will influence sourcing, cost pass-through, and time-to-market in 2026.
- Actionable risk-adjusted scenarios: Beyond a base forecast, we provide downside and upside scenarios that map to realistic procurement and product-development choices for the coming 12–24 months.
- Competitive playbooks for incumbents and entrants: The analysis translates technical product differentiation (DACs/ADCs, DSP stacks, driver ecosystems) into commercial moves — pricing, channel prioritization, and partnership strategies — that generate measurable impact in 2026.
Key market dynamics shaping strategic choices
- Steady, segmented demand: The market’s mid-single-digit CAGR reflects a balance between enduring professional/studio demand and renewed consumer interest driven by gaming, home entertainment, and creator economies. This creates room for premium, mid-market, and value-tier propositions.
- Component and policy friction: U.S. export controls on advanced semiconductors, tighter lead times for passives and discretes late in 2025, and tariff uncertainty into 2026 introduce input-cost volatility and sourcing risk that must be actively managed in supplier contracts and inventory planning.
- Technology-driven differentiation: Ongoing innovation in DAC/ADC performance, integrated DSP platforms, and better driver/firmware ecosystems means hardware alone is no longer sufficient; software and user experience increasingly determine premium positioning.
- Market concentration and competitive balance: The market is moderately concentrated: our concentration metrics indicate that leading firms hold a meaningful but not dominant share, leaving room for nimble challengers and strategic consolidators.
What the report contains — practical components for 2026 execution
- Demand model and scenario suite: A base-case forecast plus stress-tested upside and downside scenarios tied to component pricing, export control severity, and consumer device upgrade cycles.
- Go-to-market playbooks: Segmented strategies for OEM, retail, and direct-to-consumer channels — including recommended channel mixes, promotional levers, and subscription/service tie-ins for different price tiers.
- Product and technology roadmaps: Comparative feature matrices for external vs. internal form factors, high-fidelity vs. budget designs, and latency/DSP trade-off guidance for professional and gaming audiences.
- Supply-chain heatmaps and sourcing playbook: Supplier risk scoring, dual-sourcing templates, and cost-pass-through scenarios to protect margin in a volatile component environment.
- Competitive benchmarking: Strategic profiles for the major players, capabilities mapping, and M&A target screening criteria — designed to accelerate due diligence and integration planning.
- Pricing and margin toolkit: Elasticity experiments, margin optimization simulations, and SKU rationalization recommendations to maximize 2026 profitability without sacrificing growth.
Competitive landscape — strategic implications for core players
Our assessment synthesizes product portfolios, channel footprints, and technology moats across established OEMs, professional-audio specialists, and value-focused entrants. Leading providers exhibit distinct strategic postures that will influence competitive dynamics in 2026:
Worldwide Sound Cards Market
- Creative Technology Ltd. (Singapore): Continues to anchor the consumer/gaming lead with a recognized brand and a steady cadence of product enhancements, most recently with a USB DAC/amp launch and firmware updates aimed at measurable PCM performance gains. Creative’s ability to pair hardware with software ecosystems remains a key advantage — and a blueprint for competitors seeking to monetize post-sale services.
- ASUS (Taiwan): Leverages motherboard and gaming hardware expertise to defend high-fidelity and enthusiast niches. ASUS’s cross-product bundling and software suites create stickiness in gaming ecosystems — a worthwhile avenue for alliances between component suppliers and platform vendors.
- Realtek (Taiwan): As a dominant audio codec and chipset supplier, Realtek’s scale underpins the majority of onboard audio solutions. For strategic buyers and OEMs, Realtek’s roadmap and availability are critical — export controls and onshore capacity expansions are therefore key risk factors to monitor closely in 2026.
- Professional-audio specialists (UK/USA/Germany/Japan): Firms such as Focusrite, Universal Audio, RME, MOTU, PreSonus, and Roland maintain premium positions through superior converters, low-latency drivers, and pro-grade feature sets. These vendors are less price-sensitive but highly sensitive to component quality and driver stability — areas where partnership with specialized chipmakers can yield defensive advantages.
- Value/aftermarket players (USA/Germany/others): Brands like Sabrent and Behringer target volume-oriented segments. Their playbook for 2026 will hinge on cost discipline, supply-chain resilience, and rapid time-to-market for trend-driven SKUs.
- Chip/IC suppliers and niche vendors: C-Media, and other controller suppliers, remain indispensable to aftermarket and OEM sound-card suppliers. Innovations in DAC/ADC silicon from specialized vendors are enabling next-generation products; securing priority supply or co-development agreements will be decisive for companies targeting the professional and high-end consumer spaces.
Strategic moves we recommend for 2026
- De-risk procurement: Move from single-source to prioritized dual-source strategies for critical analog/digital converters and passive components; implement staged inventory buffers tied to scenario triggers from our report’s supply heatmap.
- Monetize software: Where product differentiation narrows, bundle firmware, tuning profiles, and cloud-based presets/subscriptions to extend ARPU and reduce sensitivity to hardware ASP pressure.
- Segment-focused product stacks: Build distinct platforms for pro studios, gamers/creators, and mainstream consumers — standardize modular electronics to shorten product cycles and enable tiered feature activation through firmware licensing.
- Pursue selective verticalization: Consider vertical partnerships or minority investments with converter manufacturers to secure capacity and favorable pricing, or to co-develop next-generation DAC/ADC IP aligned to professional workflows.
- Use M&A as a capability lever: Bolt-on acquisitions can accelerate software, driver, or professional market access. Our M&A playbook evaluates targets by capability gap, integration complexity, and near-term revenue accretion potential.
Risk considerations and mitigation
Key risks for 2026 include regulatory shifts (notably semiconductor export controls), component shortfalls and price spikes, and tariff volatility affecting imported modules. Our report translates these risks into operational thresholds and recommended contract language (e.g., indexation clauses, priority allocation terms) to protect margins and continuity of supply. We also highlight upside catalysts — such as accelerated DAC/ADC adoption in creator hardware and expanded domestic chip capacity — that could compress time-to-profitability for new premium products.
Worldwide Sound Cards Market
How to use this insight
Executives preparing budgets, product roadmaps, supply contracts, or M&A activity for 2026 will find the PW Consulting report especially valuable. It equips teams with a quantified market outlook, scenario-triggered action lists, and vendor-specific playbooks that translate market movement into concrete, testable initiatives. For boards and investors, the report provides a clear view of risk-reward trade-offs across strategic options — from investing in premium R&D to pursuing volume-driven cost leadership.
To access the full dataset, regional and application splits, company-level scorecards, and the decision-ready toolkits referenced here, visit the PW Consulting Worldwide Sound Cards Market report page. The published report contains the detailed segmentation and granular forecasts that underpin the high-level insights presented in this release — essential inputs for any 2026 strategy that seeks to convert forecasted growth into sustained competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Sound Cards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide BARC Market to Rise from USD 962.0 Million in 2025 to USD 1,516.7 Million by 2032 at 6.72% CAGR — Asia Pacific Leads with USD 596.4M; Organic BARC and ArF Lithography Dominate, Top 3 Hold 65.4%
By pmarketresearch, 2026-07-15
Worldwide Bottom Anti-Reflective Coatings (BARC) Market — Strategic Briefing for 2026 Decisions
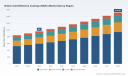
PW Consulting’s latest market study on Worldwide Bottom Anti-Reflective Coatings (BARC) provides a concise, decision-focused synthesis aimed at executives, procurement leads, R&D heads and investors who must take concrete actions in 2026. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the study projects the market to grow at a compound annual growth rate (CAGR) of 6.72% from 2026 through 2032. To give immediate scale context: the industry moved from roughly USD 846 million in 2023 to an estimated USD 962 million in 2025, and under the base forecast the market reaches approximately USD 1,516.7 million by 2032. Market concentration remains meaningful — the top three players control a majority share (CR3 ~65.4%), and the top five increase that coverage further (CR5 ~82.2%) — underscoring that strategic incumbents and a small set of challengers will shape technology adoption and price dynamics going into 2026.
Worldwide Bottom Anti-Reflective Coatings (BARC) Market
Why this matters for 2026 strategy
-
Timing complexity: Qualification cycles for new BARC chemistries (particularly those aimed at EUV and high-NA systems) stretch across quarters. Procurement and process-integration decisions taken in 2026 will materially affect fab readiness for node transitions in 2027–2029.
Worldwide Bottom Anti-Reflective Coatings (BARC) Market -
Margin and cost pressure: Upstream input volatility — exemplified by an ~8% year-on-year increase in key resin monomers — is compressing supplier margins and will be passed through selectively to buyers unless mitigated by sourcing or formulation changes.
Worldwide Bottom Anti-Reflective Coatings (BARC) Market -
Regulatory and trade shocks: New restrictions (REACH Annex XVII) on certain aromatic solvents and an active tariff environment (including a 25% import tariff on BARC imports from China effective after the 2025 review) require geographies and product portfolios to be re-evaluated for compliance and landed cost impact.
-
Logistics friction: Elevated transport surcharges linked to route disruptions (a representative surcharge of USD 0.15/kg has been observed on Asia–Europe chemical shipments) add an often-overlooked incremental cost layer for international supply chains.
What the report delivers — operational intelligence, not theory
-
Proprietary market model: A flexible Excel-based model that allows users to run demand scenarios across 2026–2032, toggle macro assumptions (node adoption curves, lithography mix shifts) and test price elasticity under different raw-material and tariff regimes.
-
Vendor scorecards: Comparative benchmarking of the market’s leading suppliers across technology readiness, product breadth, qualification cycle length, manufacturing footprint and commercial flexibility. (Note: detailed vendor scores and subsegment data are only available in the full report.)
-
Supply-chain mapping: End-to-end supplier and raw-material dependency maps, highlighting single-source risk, geographic concentration and alternative feedstock pathways suitable for fast-track qualification.
-
Scenario playbooks: Three executable strategic paths for suppliers and three for fabs — each with investment triggers, expected payback bands, capex sizing guidance and sample procurement timelines.
-
Technology roadmap & IP heatmap: A practical view of where R&D dollars should flow for next-generation BARC chemistries (EUV-compatible, high-NA-ready, solvent-restricted formulations) and an assessment of patent clustering by incumbent and new entrants.
-
M&A & partnership shortlist: A vetted list of targets and partnership archetypes (manufacturing capacity buys, specialty-resin carve-outs, co-development partnerships) suitable for accelerating route-to-market, together with preliminary valuation heuristics.
-
Risk & compliance dossier: Regulatory and tariff monitoring templates plus modelled cost impacts for EU REACH scenarios and US import tariff cases, to support rapid executive decision cycles in 2026.
Competitive landscape: what incumbents and challengers are doing
The market is dominated by a cluster of experienced specialty-chemical suppliers and a handful of diversified materials groups. Several strategic patterns are clear heading into 2026:
-
Focused product innovation: JSR Corporation has openly targeted the next frontier of lithography by introducing an EUV-compatible BARC for high-NA systems (Oct 2025). This move signals that leading suppliers are prioritizing high-value, high-barrier offerings that align with advanced-node roadmap timing.
-
Capacity and qualification plays: Tokyo Ohka Kogyo expanded production capacity in 2025 to serve very advanced node demand — a defensive and offensive step that shortens lead times for existing customers and raises the bar for new entrants.
-
Quality and standards alignment: Shin-Etsu’s recent certifications emphasize the premium placed on reliability and process integration within fabs; certification and qualification are de facto market access gates in this sector.
-
Consolidation and rebranding: Several historical players have been absorbed into larger chemical platforms (e.g., Dow’s BARC portfolio integration into DuPont; AZ Electronic Materials now operating under Merck KGaA). Consolidation accelerates scale advantages but creates customer concerns about product roadmap continuity.
Strategic implication: buyers will increasingly select suppliers not only on price and chemistry but on their demonstrated ability to support long qualification cycles, localize supply where tariffs or logistics penalties bite, and offer roadmap alignment for EUV/high-NA transitions.
Key market dynamics and immediate risk mitigations
-
Raw-material inflation: The ~8% rise in certain resin monomer prices forces a two-track mitigation: (1) short-term hedging and extended fixed-price contracts with key suppliers; (2) accelerated co-development of lower-cost or more readily available monomer alternatives to reduce cost pass-through risk.
-
Regulatory reformulation: REACH restrictions on aromatic solvents make pre-emptive reformulation a commercial necessity for suppliers targeting EU customers. Buyers should request REACH-compliant formulation roadmaps and qualification timelines as part of procurement negotiations in 2026.
-
Tariff exposure and nearshoring: The 25% tariff on China-origin BARC imports to the US materially shifts landed-cost math. A combination of regional production presence, toll-manufacturing agreements and strategic inventory placement will be required to maintain competitive lead times at acceptable costs.
-
Logistics surcharge contingency: Even seemingly modest surcharges (e.g., USD 0.15/kg) compound when multiplied across volume-heavy annual procurement — include logistics surcharge scenarios in TCO calculations and consider regional buffer inventories for critical SKUs.
Recommended strategic plays for 2026 — who should do what
-
For suppliers: prioritize dual-track R&D — maintain incremental improvements for existing nodes while fast-tracking EUV/high-NA chemistries; shore up regional manufacturing where tariffs and logistics are punitive; and embed long-term supply contracts with key fabs to stabilize demand signaling.
-
For semiconductor fabs and IDM procurement: accelerate vendor qualification sequencing for next-gen lithography BARC now, lock volume-flexible contracts including raw-material cost pass-through terms, and require supplier compliance roadmaps for solvent restrictions and export-control risks.
-
For private-equity and strategic investors: evaluate targets that provide either specialty-resin IP or regional manufacturing bases; prioritize bolt-on acquisitions that shorten qualification timelines or supply chains for target customer segments.
-
For policymakers and trade teams: coordinate with industry to create rapid-compliance channels for reformulated chemistries and explore mitigation for tariff and logistics consequences that risk hollowing domestic production capabilities.
Trailer: what we’ve intentionally withheld and where to get it
In keeping with the “trailer” principle, this briefing highlights strategic value and the actionable levers companies must consider in 2026 — while deliberately omitting core granular subsegment figures and full vendor scorecard metrics that form the premium analytic engine of the study. The full report contains the complete segmentation matrices, downloadable forecast model, supplier benchmarking with scorecards and M&A shortlists that support immediate execution. For teams preparing capex approvals, vendor negotiations, or M&A diligence in 2026, those datasets are practical necessities.
To obtain the full report, the market model and the executable playbooks referenced here, please contact PW Consulting or visit our report page to access the complete Worldwide BARC Market study and supporting materials.
For detailed analysis of this topic, please visit the official page: Worldwide Bottom Anti-Reflective Coatings (BARC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts 7.5% CAGR for Worldwide Breathable Waterproof Fabrics Market, Signaling Strong Growth Prospects
By pmarketresearch, 2026-07-15
Worldwide Breathable Waterproof Fabrics Market — Strategic Preview for 2026 Decision-Makers
Executive summary
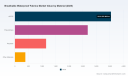
PW Consulting’s new market brief on the Worldwide Breathable Waterproof Fabrics Market (base year 2025, historical 2020–2025, forecast period 2026–2032) translates rich primary and secondary research into an actionable strategic playbook for 2026. With the market expanding at a compound annual growth rate (CAGR) of 7.5% from 2026 through 2032, our forecast traces a trajectory from a 2025 market size of USD 7,760.11 Million (revenue unit: Million USD) to an anticipated USD 12,874.40 Million by 2032. This release is designed as a ‘trailer’: it demonstrates the rigor and depth of our analysis while intentionally withholding detailed regional- and application-level datapoints to encourage engagement with the full report and dataset.
Worldwide Breathable Waterproof Fabrics Market
Why this report matters for 2026 strategy
-
Regulatory inflection points and material-technology shifts are compressing decision cycles. Companies that realign product portfolios and supply chains in 2026 will capture outsized market positions by 2028–2030.
Worldwide Breathable Waterproof Fabrics Market -
Market consolidation signals selective opportunities: our concentration analysis shows the top three players account for a meaningful share of industry revenue (CR3 38.5%) and the top five reach a majority share (CR5 52.2%). Such structure creates both partnership and acquisition opportunities for mid-sized innovators and large strategic buyers.
Worldwide Breathable Waterproof Fabrics Market -
Raw material volatility and alternative membrane technologies are reshaping cost structures and differentiation levers. The report translates these trends into cost-scenario models and sourcing playbooks executives can act on now.
Market trajectory — the headline numbers you need
Using a bottom-up approach aligned to industry revenue reporting conventions, PW Consulting places the 2025 worldwide breathable waterproof fabrics market at USD 7,760.11 Million (Million USD). Our forecast projects immediate momentum into 2026 (USD 8,446.27 Million) and sustained growth at a 7.5% CAGR across the 2026–2032 horizon, culminating in an estimated USD 12,874.40 Million by 2032. These headline numbers reflect demand tailwinds in performance apparel, protective fabrics, and selected technical textiles, combined with supply-side shifts driven by raw material cycles and new membrane technologies.
What’s driving growth and where uncertainty lies
-
End-market pull from active and outdoor performance categories continues to grow, particularly where consumers demand higher durability, lighter weight, and demonstrable sustainability credentials.
-
Regulation and certification frameworks are accelerating substitution away from intentionally added PFAS and toward recyclable or bio-based alternatives. This creates near-term product reengineering costs but establishes medium-term differentiation for first movers.
-
Material-technology innovation — notably advances in nanofiber nonwovens and PFAS-free membrane chemistry — is enabling new combinations of breathability, elasticity, and circularity that were previously trade-offs.
-
Downside risks concentrate in raw-material cost swings (fluoropolymers, polyurethanes), tightening trade controls, and potential downstream softness in industrial and automotive applications that could moderate growth in specific segments.
Regulatory and raw-material dynamics to watch in 2026
-
Regulatory momentum: Several jurisdictions adopted restrictive measures on intentionally added PFAS starting in 2025–2026 and have signaled broader textile restrictions through 2030. These policies are forcing design-for-compliance and creating market access differentials for companies that have already certified PFAS-free alternatives.
-
U.S. TSCA updates and targeted chemical prohibitions introduce equipment and material transition costs for certain supply-chain participants; the compliance horizon in late 2026 should be a board-level agenda item for companies operating in or exporting to the United States.
-
Raw materials: While fluoropolymer pricing softened in certain regions in late 2025, upstream sourcing complexity (e.g., export licensing for fluorspar) has added unpredictable cost pressure for Western converters. Polyurethane pricing softened in Europe toward the end of 2025, easing margin pressure for some laminators but also signaling weaker demand in adjacent end markets.
Competitive landscape — winners, challengers, and technology specialists
Our competitive analysis blends product portfolio assessment, go-to-market positioning, manufacturing footprint, sustainability commitments, and IP posture. The market features a mix of heritage membrane makers, integrated fabric houses, specialty chemical suppliers, and newer membrane innovators. Key profiles we analyzed include:
-
W. L. Gore & Associates — perennial leader in ePTFE-based membranes with a strategic pivot toward PFAS-minimized ePE membranes; core strength: brand, technical leadership, and premium OEM OEM relationships ( https://www.gore.com/).
-
Toray Industries — deep competency in polyurethane/TPU systems for performance and industrial applications, supported by extensive R&D and global manufacturing scale ( https://www.toray.com/).
-
SympaTex Technologies — focused on recyclable polyester-based membranes and licensing models that appeal to brands pursuing circularity ( https://www.sympatex.com/).
-
schoeller Textil — niche premium textiles and treatments tailored to outdoor and workwear performance ( https://www.schoeller-textiles.com/).
-
Polartec and eVent (Clarus Corporation) — laminate and membrane specialists delivering differentiated breathability systems and collaborative product demonstrations with downstream apparel manufacturers ( https://www.polartec.com/, https://eventfabrics.com/).
-
Formosa Taffeta and other large-scale coated/laminated fabric producers — scale players supplying global apparel and technical textile markets ( https://www.ftc.com.tw/).
-
HeiQ, dimpora, and select newcomers — focused on functional treatments, PFAS-free CoreLayer technologies, and circularity-focused membranes, offering partnership and licensing opportunities ( https://heiq.com/, https://dimpora.com/).
-
Regional innovator examples such as ANTA Sports — demonstrating how mass-market brands can industrialize PFAS-free, bio-based membranes at scale ( https://www.anta.com/).
Recent industry moves we tracked—such as a major sports brand launching a mass-produced PFAS-free bio-based membrane in 2025, next-generation product updates from legacy membrane providers, and a nanofiber factory-scale breakthrough in early 2026—underline a fast-evolving technology and commercialization cycle.
What the PW Consulting report contains — practical, transaction-ready outputs
-
Concise market-sizing and confidence intervals by year (2020–2032), with scenario paths under alternative regulatory and raw-material assumptions.
-
Segment-level demand drivers and elasticities (by material type, major end-uses, and channel), presented qualitatively in the preview and numerically in the full dataset.
-
Supplier benchmarking matrix covering technology, capacity footprint, environmental compliance, partnership readiness, and acquisition likelihood.
-
Regulatory risk heatmaps and a compliance-cost estimator tied to geography and product architecture.
-
Technology adoption roadmap that maps when and where nanofiber membranes, ePE variants, bio-based films, and PFAS-free chemistries become commercially compelling.
-
Practical playbooks for: sourcing resilience (multi-sourcing triggers and inventory buffers); product reengineering (retrofit vs. redesign decision trees); commercial positioning (premium vs. value stratification); and M&A screening (financial and strategic criteria).
-
Model-ready annexes: raw-material price sensitivity tables, contract manufacturing cost curves, and unit-economics templates for OEMs and fabric converters.
Strategic implications and recommended 2026 actions
-
Prioritize PFAS-free product roadmaps for any SKU intended for North American or EU markets. Early certification secures shelf space and reduces downstream rework costs.
-
Develop staged supplier diversification plans that explicitly model a 12–24 month window for qualifying non-fluoropolymer membranes and alternative coatings.
-
Invest in co-development agreements with membrane innovators (nanofiber producers, PFAS-free membrane specialists) to accelerate time-to-market and selectivity for premium placements.
-
Reassess pricing strategies: build flexible contracts and margin buffers to absorb episodic raw material cost swings and to fund transition costs associated with regulatory compliance.
-
Consider targeted M&A or JV activity to acquire in-house membrane capabilities or to secure strategic capacity in regions facing export controls or raw-material supply tightness.
How to use this preview and where to get the full intelligence
This article is a strategic preview — it presents the definitive growth trajectory and the essential competitive and regulatory context but intentionally omits the full, transaction-grade segmentation tables (regional and application-level revenue breakdowns, and granular price-volume schedules). Boards, strategy teams, corporate development groups, and product heads should use this preview to prioritize internal initiatives; then license the full PW Consulting report and underlying dataset to operationalize supplier qualification, scenario stress-testing, and M&A screening workflows.
Conclusion
The breathable waterproof fabrics market is entering a period of structural reconfiguration driven by regulation, material innovation, and shifting demand preferences. PW Consulting’s 2026-focused research equips executives with the macro view (market size and growth path), the competitive map, and a practical set of tools to convert uncertainty into strategic advantage. For the full dataset, granular segment economics, and the complete suite of tactical playbooks needed to act decisively in 2026, please refer to the PW Consulting report page and licensing options.
For detailed analysis of this topic, please visit the official page: Worldwide Breathable Waterproof Fabrics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Venetoclax API Market Poised for Robust 12.51% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Venetoclax API Market: Strategic Imperatives for 2026 — PW Consulting Preview
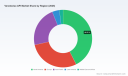
PW Consulting's new Worldwide Venetoclax API Market study (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes commercial, regulatory and technical intelligence into a single, actionable roadmap for executives planning moves in 2026. The market has demonstrated rapid expansion — roughly doubling from the low hundreds of millions in 2020 to more than a quarter-billion USD by 2025 — and our forecasts show sustained high‑teens to low‑teens annual growth thereafter (CAGR 12.51%), driving a multi‑hundred‑million USD opportunity by 2032. This preview highlights the strategic value of the full report for decisions on manufacturing capacity, supply agreements, regulatory positioning and M&A, while deliberately withholding granular segment tables to encourage access to the full dataset and supplier scorecards on our site.
Worldwide Venetoclax API Market
Why 2026 Is a Pivotal Year
-
Confluence of regulatory and commercial inflection points: patent windows and exclusivity timelines are concentrating competitive pressure in the coming years. The current US composition‑of‑matter patent portfolio and associated pediatric exclusivity create a defined runway for branded pricing power followed by phased generic entry. Companies must align 2026 investments to the mid‑ to late‑patent landscape to capture the most value.
Worldwide Venetoclax API Market -
Healthcare payor dynamics are tightening: observed reimbursement benchmarks for branded Venetoclax have set a high reference price in major markets, which will shape generic uptake, formulary access and volume shifts once price competition emerges. Manufacturers and purchasers that model these reimbursement trajectories now will be advantaged in supplier contracting and commercialization planning.
Worldwide Venetoclax API Market -
Supply chain concentration and input risk are already affecting margins and availability. A small set of intermediates—notably specialized indole and pyrazole building blocks—drive disproportionately large cost and lead‑time exposure in small‑batch API manufacturing; our analysis shows these inputs can push unit costs materially higher absent scale or backward integration.
Market Dynamics & Structural Drivers
-
Robust growth trajectory: from a post‑2020 recovery period, the Venetoclax API market accelerated to exceed a quarter‑billion USD by 2025 and is projected to continue expanding through 2032 under multiple clinical and commercial scenarios. The 12.51% CAGR reflects not only rising finished‑dosage demand, but also increased API demand from generic entrants, clinical trials and new label expansions.
-
High market concentration: the top three and top five suppliers account for a dominant share of global supply. This concentration compounds both strategic risk (single‑source dependency) and negotiation leverage for incumbent suppliers — an important input for procurement teams and private equity sponsors considering vertical or horizontal plays.
-
Raw material and cost structure: Venetoclax API chemistry is complex. Specialized intermediates elevate unit production costs in small runs, and procurement teams must factor in steep price sensitivity for non‑standard intermediates. The report includes a cost‑build model and sensitivity analysis that quantify the impact of batch size, yield improvements and intermediate sourcing strategy on API unit economics.
-
Regulatory and trade risk: over two‑thirds of global API capacity is concentrated in India and China. While these regions provide cost advantages, they are also exposed to regulatory volatility — including facility inspections, import alerts and evolving GMP expectations from major regulatory agencies. The full study contains a jurisdictional risk matrix that maps facility inspection outcomes, DMF/CEP coverage and probable lead‑time impacts under multiple regulatory scenarios.
Competitive Landscape — What To Watch
-
MSN Laboratories Pvt. Ltd. (Hyderabad) — A high‑purity API producer with multiple DMFs on file. MSN’s global DMF footprint and recent legal settlements position it as a near‑term supplier to prospective generic finished‑dosage companies. Strategic priority: monitor DMF commercialization timelines and partnership announcements that signal volume commitments beyond captive generics.
-
Hetero Drugs Ltd. (Hyderabad) — Produces Venetoclax at commercial scale and holds CEP certification. Hetero’s strengths lie in integrated supply capabilities for finished‑dosage customers. Strategic priority: evaluate contract structures that balance volume guarantees with quality and supply continuity clauses.
-
Aurobindo Pharma Ltd. (Hyderabad) — Operating US‑approved facilities with an oncology‑API focus. Aurobindo is well‑placed for export markets and has demonstrated the regulatory and scale competencies needed to support large‑volume supply. Strategic priority: consider Aurobindo as a partner or competitor in tender scenarios and assess capacity ramp timing versus your commercialization schedule.
-
Senova Technology Co., Ltd. (Tianjin) — Emphasizes DMF filings and rigorous GMP compliance for international supply. Senova is notable for its technical platform and compliance record. Strategic priority: for sponsors seeking alternative sources, evaluate Senova’s regulatory dossier compatibility with target markets.
-
Recent legal development: a patent settlement announced in late 2022 signaled an accelerated pathway for potential generic API production and finished‑dosage launches after defined dates — a development that has already affected supplier capacity allocation and pricing expectations. Our competitive chapter models how settlement outcomes ripple through supplier capacity, pricing and contract terms into 2026 and beyond.
What the PW Consulting Report Delivers (Practical Content)
-
Granular forecast by scenario (conservative, base, accelerated) across the 2026–2032 horizon, with embedded sensitivity to key variables: launch timing, payor pressure, and clinical expansion.
-
Supplier scorecards that synthesize regulatory filings (DMF/CEP), inspection history, capacity, and commercialization readiness into vendor risk and opportunity ratings.
-
Cost‑build and margin analysis templates — including a liveable model for adjusting yields, batch sizes and intermediate costs — to support make‑vs‑buy decisions and pricing negotiations.
-
Regulatory risk heatmaps and a practical checklist for DMF/CEP strategy, approval timelines and post‑approval supply continuity planning.
-
Commercial playbooks for CMO selection, dual‑sourcing design, and structured offtake agreements that include milestone triggers, quality KPIs and contingency provisions.
-
M&A and partnership screening toolkit that identifies target profiles and valuation levers for upstream API assets, technology platforms (e.g., high‑purity synthesis techniques) and regional manufacturing hubs.
Recommended Strategic Actions for 2026
-
Initiate an immediate supply‑chain assurance audit: map single‑source risks, DMF/CEP coverage and inspection histories for existing suppliers and known alternates. Translate audit findings into tiered contingency plans.
-
Lock conditional capacity early: contract structures that combine capacity reservations with step‑in rights or financial penalties protect against late‑cycle shortages while preserving optionality for demand variance.
-
Hedge critical intermediates and consider backward integration where cost modeling shows durable economic benefit. Small‑batch intermediate scarcity and high per‑kg inputs create outsized margin risk unless actively managed.
-
Accelerate regulatory filings where applicable (DMFs/CEPs) and build cross‑functional alignment between regulatory, quality and commercial teams to compress approval‑to‑supply lead times.
-
Design competitive intelligence streams: monitor settlement outcomes, DMF publications and finished‑dosage licensing announcements. The market’s concentration means that a single large commercial contract can reallocate global supply.
-
Prepare commercial launch scenarios that incorporate payor dynamics and expected price erosion post‑generic entry. Use scenario testing to set tiered pricing, market access and contracting strategies.
How PW Consulting’s Study Accelerates Decision‑Making
The study is structured for direct operational uptake: procurement leaders can extract supplier shortlists and negotiation playbooks; C‑suite teams can align capital allocation to capacity expansion windows; business development teams can prioritize M&A targets with the highest synergy for cost reduction and regulatory defensibility. In short, the report turns complex, multi‑vector market intelligence into executable plans for 2026.
We intentionally keep this preview high level. The full report contains the complete dataset, regional and application sub‑segment forecasts, supplier scorecards and customizable financial models that underpin the scenarios referenced above. Those granular outputs are essential for negotiating supply agreements, sanctioning CAPEX or executing roll‑out plans — and are available on the PW Consulting portal.
Conclusion
Venetoclax API is entering a strategic window in 2026 where regulatory timelines, reimbursement pressures and supplier dynamics intersect to create both risk and upside for manufacturers, CMOs, investors and payors. Executives who align procurement discipline, regulatory preparedness and scenario‑based commercial planning now will capture first‑mover advantages when the market transitions from branded dominance to multi‑actor supply. PW Consulting’s Worldwide Venetoclax API Market study provides the analytical foundation and practical toolsets to make those choices with confidence.
To obtain the full dataset, supplier scorecards and executable playbooks that support 2026 decision‑making, please visit our report page on the PW Consulting website or contact our industry advisory team.
For detailed analysis of this topic, please visit the official page: Worldwide Venetoclax API Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Fabric Flame Retardancy Testers Market Poised to Grow at a 5.45% CAGR During 2026–2032
By pmarketresearch, 2026-07-15
Worldwide Fabric Flame Retardancy Testers Market: A Strategic Preview for 2026 Decision‑Makers
PW Consulting’s latest market study on Worldwide Fabric Flame Retardancy Testers provides a focused, operationally-oriented roadmap for executives, procurement leaders, lab directors and investors positioning themselves for 2026 and beyond. The study synthesizes long‑run demand patterns, standards evolution, supplier capabilities and cost dynamics into practical decision tools. This preview highlights the report’s strategic value while reserving the granular segmentation tables and downloadable financial models for report subscribers.
Worldwide Fabric Flame Retardancy Testers Market
Market trajectory at a glance
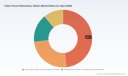
The fabric flame retardancy testers market has shown steady growth through the early 2020s, expanding from the low‑double‑digit millions in 2020 to an estimated USD 115.8 million in 2025 (base year). Our forecast model projects continued expansion into the latter part of the decade: the market is expected to exceed USD 122 million in 2026 and reach the high‑hundreds of millions by the early 2030s, reflecting a compound annual growth rate of approximately 5.45% across the forecast window. That growth is driven by a blend of regulatory tightening, product safety imperatives across textiles and interiors, and replacement/upgrade cycles at independent testing houses and OEM captive labs.
Worldwide Fabric Flame Retardancy Testers Market
Why this matters for 2026 corporate strategy
- Procurement and CAPEX planning: With predictable, mid‑single‑digit CAGR growth, buyers can model replacement versus retrofit decisions for test benches and chambers. The market’s steady expansion supports staged investments (modular upgrades) rather than one‑time, high‑risk outlays.
- Regulatory compliance and product design: Changes to flammability standards and enforcement activity make tester selection a strategic lever for apparel, automotive interiors and building product manufacturers to de‑risk launches and demonstrate compliance.
- Aftermarket and service revenues: As testers age, demand shifts toward calibration, spare parts and upgrade kits. Companies that build service networks and subscription calibration programs can create recurring revenue streams that outpace equipment sales.
- M&A and partnership strategies: The market’s moderate concentration profile creates attractive targets for bolt‑on acquisitions—particularly for vendors seeking geographic reach or standards expertise.
What the full report delivers (practical content)
PW Consulting’s report is structured to move decision‑makers from insight to execution. Key deliverables include:
Worldwide Fabric Flame Retardancy Testers Market
- Proprietary market sizing and a flexible forecasting model (2026–2032) that can be re‑run with client assumptions.
- Demand driver analysis that links regulatory updates, end‑market growth and lab capacity to tester demand.
- A standards matrix mapping test methods (vertical/horizontal/45°/curtain, UL/ASTM/ISO/NFPA/GB/EN/ECE) to equipment features and procurement spec templates.
- Competitive benchmarking with feature‑level scorecards, channel and service footprints, and buyer reference profiles.
- Operational playbooks: lab setup checklists, calibration and traceability templates, total cost of ownership (TCO) models, and maintenance/service contract negotiation guides.
- An M&A screening toolkit with valuation sensitivities, integration risks, and capabilities mapping for potential targets.
Each of these outputs is oriented to be immediately usable by purchasing teams, lab managers and corporate strategists—while the full dataset, including downloadable Excel models and segmented forecasts, is available from the report portal.
Competitive landscape: how to interpret vendor positioning
The vendor field spans global incumbents and regional specialists. A small group of suppliers capture a meaningful share of formal installations, but the market retains fragmentation at the lower tiers. Top suppliers combine standards breadth, automation capability and after‑sales networks to win institutional contracts, while smaller vendors often compete on price and rapid customization.
Representative vendor positioning in the study illustrates common strategic archetypes:
- Comprehensive product line owners who cover vertical, horizontal, 45° and specialty test rigs and who emphasize standards compliance and lifecycle support.
- Specialists focused on specific test methods or end‑markets (e.g., curtain/vertical propagation or automotive interior chambers) that win by superior process control and niche certification experience.
- Automation and digital incumbents who pair mechanical rigs with PLC/optical measurement and reporting suites designed for high‑throughput labs or manufacturing QCs.
- Regional players with cost advantages and rapid local service, particularly in growth markets where localized calibration and spare parts responsiveness are high‑value.
The market concentration metrics in our report indicate a moderate degree of aggregation among the top vendors—enough to support strategic alliances and acquisitions, but with ample opportunity for challengers that can combine standards depth with service excellence.
Standards and regulatory dynamics shaping procurement
Standards evolution is a primary demand shaper for testers. Recent and ongoing items of note include amendments to established national standards and persistent relevance of legacy methods that buyers still require. For example, amendments to the U.S. consumer flammability standard for clothing textiles have been implemented in recent years, expanding permissible equipment models while leaving core flammability class outcomes intact—an important distinction for labs choosing future‑proof equipment. Meanwhile, vertical flame resistance protocols (commonly used for protective clothing) and ISO‑based flame spread procedures remain central reference points for many purchasers.
For equipment buyers, the implication is clear: purchase strategies should prioritize configurability and certifiability across multiple standards, and procurement specifications must explicitly require traceability to the relevant test methods and documented calibration paths.
Supply‑side signals and cost implications
Capital equipment makers operate against a backdrop of raw material cost volatility. Recent trends show steel price stabilization after prior volatility, with futures broadly signalling modest firmness into early 2026; aluminum mill shapes have experienced notable year‑on‑year increases. These dynamics translate into two operational realities for purchasers: lead times and list prices for new rigs can vary meaningfully with metal price cycles, and manufacturers may respond with engineered substitutions or modular designs to manage bill‑of‑materials cost jumps.
Buyers looking to optimize TCO should therefore negotiate price‑adjustment clauses, multi‑year service contracts that lock spare parts pricing, and explore local manufacturing or sourced components to reduce exposure to global metal cycles.
Priority actions for 2026
- Adopt a modular investment strategy: specify platforms that accept incremental sensor and automation upgrades to spread CAPEX over the tester lifecycle.
- Require multi‑standard certification and documented calibration pathways in procurement RFPs to avoid later retrofit costs.
- Build localized calibration and spare parts capacity in high‑use regions to reduce downtime—either via partner networks or controlled distributor agreements.
- Implement TCO and scenario models when assessing supplier bids; ask vendors for service revenue forecasts and spare‑parts life curves.
- Pursue targeted M&A or partnership for service network expansion in markets where in‑country calibration and accreditation create competitive advantage.
- Hedge raw‑material exposure through supplier agreements with price indexation or extended firm‑price windows for critical mechanical parts.
How PW Consulting’s report supports implementation
Beyond diagnostic analysis, the published study provides the tactical instruments that sourcing teams and lab directors need to act: editable forecast models, procurement RFP templates keyed to standards coverage, comparative supplier scorecards, and an execution checklist for establishing accredited test capability. For strategy teams, our M&A screening tools and competitor capability maps reduce discovery time and clarify integration priorities.
This preview lays out the strategic contours for 2026—what matters, why it matters, and what to do next. For readers requiring the full segmented forecasts, downloadable models, and the vendor‑level benchmarking matrices that underpin the recommendations, the complete report and associated toolkits are available from PW Consulting’s report page. Those resources contain the detailed regional and application splits, scenario runs and unit‑level pricing tables needed to finalize procurement budgets, acquisition targets and lab expansion plans.
Contact PW Consulting to access the full Worldwide Fabric Flame Retardancy Testers Market report and obtain client‑only briefings and template bundles tailored to your organization’s 2026 strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Fabric Flame Retardancy Testers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com