

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide High-capacity NFC Chip Market Poised to Expand at a 12.71% CAGR During 2026–2032
By pmarketresearch, 2026-07-15
Worldwide High-capacity NFC Chip Market: Strategic Imperatives for 2026 — PW Consulting Release
PW Consulting today publishes strategic highlights from our forthcoming Worldwide High-capacity NFC Chip Market report (base year 2025, historical 2020–2025, forecast 2026–2032). The market has moved from a niche enabler to a core architectural component in IoT, secure credentials, and consumer engagement. In this briefing we synthesize the macro trajectory, competitive dynamics, supply-side constraints and practical decision levers that senior executives should adopt in 2026. For readers seeking the granular regional and application splits, proprietary scenario models, and vendor-level revenue tables, the full report and datasets are available on our website.
Worldwide High-capacity NFC Chip Market
Why this market matters to enterprise strategy in 2026
-
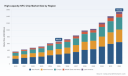
Market momentum: After expanding from roughly USD 365.4 million in 2020 to USD 664.28 million in 2025, the high-capacity NFC chip market is projected to continue rapid expansion, reaching approximately USD 1,534.92 million by 2032. Our forecasted compound annual growth rate for the 2026–2032 period is 12.71%. These dynamics reframe NFC chips from peripheral components to strategic enablers for product differentiation and platform monetization.
Worldwide High-capacity NFC Chip Market -
Structural concentration: The market exhibits meaningful concentration at the top. PW Consulting’s analysis places the three largest suppliers as a dominant block and the top five controlling a substantial majority of industry revenue — a structure that both stabilizes technology roadmaps and creates barriers for new entrants. This concentration elevates the importance of supplier strategy for enterprises that embed NFC functions into devices, packaging, and services.
Worldwide High-capacity NFC Chip Market -
Cross-industry reach: High-capacity NFC is no longer a single-use commodity. It supports secure onboarding (Matter and other frameworks), high-throughput credentialing for transit and payments, anti-counterfeiting for luxury goods, and data-rich cold chain monitoring. Expect procurement, product, and security teams to be primary stakeholders in NFC decisions from 2026 onward.
Report scope and operational value (what’s inside)
-
Market sizing and forecasting: Methodology, base-year reconciliations (2020–2025), and scenario-driven forecasts for 2026–2032 mapped to revenue outcomes under differing adoption and pricing paths.
-
Go-to-market playbooks: Actionable roadmaps for device OEMs, packaging companies, certification bodies and system integrators that convert NFC capabilities into monetizable features.
-
Supplier and technology benchmarking: Comparative evaluation of architectures (EEPROM vs. flash, multi-protocol combos), security primitives, memory density tiers and read-performance trade-offs.
-
Risk models and procurement tactics: Lead-time simulations, price sensitivity analysis, hedging strategies, and contract design templates to mitigate extended lead times and rising average selling prices.
-
M&A and partnership intelligence: Identification of attractive consolidation targets, strategic partnership matrices, and valuation sensitivities given the market’s concentration profile.
-
Primary research: Interview excerpts with system integrators, Tier-1 buyers and device manufacturers, plus an anonymized dataset of supplier lead-times and price movement observed in 2024–2026.
Competitive landscape — players to watch and their strategic postures
-
NXP Semiconductors (Eindhoven) — Positions itself as a performance leader for high-capacity tags with products focused on throughput, RF optimization and IoT-tailored features. Recent product introductions emphasize larger user memory and RF tuning capabilities, making NXP a natural partner for applications that require fast, reliable reads and tamper-aware deployment.
-
STMicroelectronics (Plan-les-Ouates) — Broad portfolio coverage with moves into secure onboarding for smart home ecosystems. Their recent secure-tag announcement targeting Matter 1.5 onboarding signals a strategic push into device commissioning and zero-battery provisioning, a capability that will influence smart-home product architectures and reduce friction in consumer device setup.
-
Infineon Technologies (Neubiberg) — Combines secure non-volatile technologies with multi-protocol flexibility, making it attractive where high-assurance contactless interaction (payments, identity, industrial controls) is required. Their emphasis on secure flash and flexible protocol stacks positions them well for regulated and industrial segments.
-
Broadcom Inc. (Palo Alto) — Plays to integration: combo chips that pair NFC with low-energy Bluetooth and other radios. This approach is compelling for mobile and wearable OEMs aiming to reduce BOM complexity while enabling cross-radio experiences.
-
Samsung Electronics (Suwon) — Focuses on mobile-first optimizations and cryptographic integrations; attractive to OEMs and service providers wanting tight integration between device firmware, secure elements, and NFC I/O.
-
Sony Corporation (Tokyo) — FeliCa-based solutions retain a strong position in transit and payment ecosystems where the standard remains entrenched. Sony’s deep ecosystem relationships mean long-term recurring demand in specific verticals.
Recent developments shaping supplier selection and risk
-
Product launches with security and onboarding features are accelerating supplier differentiation. Notable examples include high-performance HF tag ICs that raise throughput and advanced secure onboarding chips that enable battery-less commissioning. These functional differentiators should be evaluated as part of total cost of ownership, not just unit price.
-
Pricing and cost pressures: Several major vendors have implemented price increases in 2026, citing higher materials, energy and manufacturing costs. Buyers must model these increases into product pricing and negotiate indexation clauses or multi-year agreements to dampen P&L volatility.
-
Supply chain friction: Extended lead times for wafers and substrates — in some cases stretching to 30–40 weeks — have become a persistent constraint for advanced high-capacity variants. This drives a shift in procurement from just-in-time to just-in-case inventory strategies for critical SKUs and spurs interest in local or nearshore packaging partners.
-
Geopolitical and regulatory constraints: Export controls and trade measures affecting semiconductor components introduce execution risk for manufacturers with cross-border operations. Corporates must incorporate regulatory scenarios into sourcing and dual-sourcing plans to maintain production continuity.
Strategic recommendations for 2026 decision-makers
- -
-
Translate NFC capability into differentiated product outcomes: Prioritize features that map to revenue — secure credentialing, frictionless onboarding, anti-counterfeiting — rather than treating NFC as a checkbox. Product managers should quantify the incremental ARPU or cost savings enabled by NFC use cases.
-
-
Re-evaluate procurement architecture: Move from purely transactional sourcing to strategic supplier partnerships. Negotiate priority allocation, capacity reservations, and supply-backed SLAs for high-value programs. Where feasible, stagger purchase commitments across multiple suppliers to mitigate single-vendor disruptions.
-
-
Build variant-aware inventory playbooks: For products relying on higher-capacity NFC variants, create inventory buffers and adopt dynamic allocation logic tied to manufacturing cadence and sales velocity.
-
-
Invest in standards and onboarding ecosystems: Support and adopt interoperable onboarding standards (e.g., Matter-related flows) to reduce customer friction and lower returns. Working with suppliers that provide strong support for modern onboarding paradigms can shorten time-to-market for connected products.
-
-
Pursue targeted R&D and IP plays: Given the market’s concentration, invest in software and integration IP (secure provisioning, OTA management, lifecycle analytics) that capture margins beyond component sales. Consider licensing or co-development deals with dominant IC vendors to lock in technical roadmaps.
-
-
Evaluate M&A and partnership windows: The current market structure and growth profile create opportunities for strategic bolt-ons — from packaging players to authentication-service providers — that can accelerate time-to-revenue and strengthen differentiation.
What PW Consulting recommends as next steps
For C-suite and business unit leaders planning 2026 investments, we recommend a three-step program:
-
Conduct a use-case prioritization workshop to quantify the commercial impact of NFC-enabled features across product lines.
-
Perform a supplier-risk audit that maps current contracts, lead-times and exposure to regulatory constraints; implement immediate sourcing mitigations where single points of failure exist.
-
Commission a pilot that combines high-capacity tags, secure onboarding, and lifecycle telemetry to validate both technical integration and a monetization model (subscription, data licensing, or reduced churn).
Final note — why consult the full report
This briefing distills high-level strategic implications from our full Worldwide High-capacity NFC Chip Market study. The complete report contains the granular, actionable intelligence procurement teams, product leaders and corporate strategists require: detailed scenario models, price and lead-time matrices, supplier scorecards, and primary-interview evidence. In keeping with our “trailer” approach, we have withheld exhaustive segmentation tables and vendor revenue breakdowns here to encourage direct access to the source document and interactive datasets.
To review the full methodologies, obtain vendor-level benchmarking and download the data workbook that underpins our USD-denominated market sizing and the 12.71% CAGR forecast for 2026–2032, please visit the PW Consulting report page or contact our industry team for an executive briefing.
For detailed analysis of this topic, please visit the official page: Worldwide High-capacity NFC Chip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide 3D Automated Optical Inspection Equipment in PCB Market to Expand at 11.2% CAGR During 2026–2032
By pmarketresearch, 2026-07-15
Worldwide 3D Automated Optical Inspection Equipment in PCB Market — Strategic Outlook for 2026 Decision‑Making
PW Consulting’s newest market intelligence brief, “Worldwide 3D Automated Optical Inspection (AOI) Equipment in PCB Market,” synthesizes five years of historical performance and a seven‑year forecast to deliver the decisive context executives need as they make procurement, investment, and M&A choices in 2026. Anchored on a 2025 base year and built from primary vendor interviews, proprietary shipment models and field validation, the study projects the market to grow from USD 1,100.0 Million in 2025 to USD 2,312.74 Million by 2032, implying a compound annual growth rate (CAGR) of 11.2% across the forecast window. The research is designed as a practical playbook: it equips leaders with scenario tools, vendor scorecards and procurement tactics while intentionally withholding granular region- and application-level datapoints from this summary to encourage direct access to the full deliverable.
Worldwide 3D Automated Optical Inspection Equipment in PCB Market
Why 2026 Is a Pivotal Year for AOI Investment
Three convergent forces are reshaping AOI economics and timing decisions for PCB assemblers in 2026:
Worldwide 3D Automated Optical Inspection Equipment in PCB Market
- Technology maturation and regulatory tightening — Standards introduced or updated in 2025 increasingly mandate sub‑micron and tighter height‑measurement tolerances for high‑reliability boards, elevating the bar for inspection performance and certification readiness across supply chains.
- Supply and cost pressure — Component shortages and longer lead times for high‑resolution camera modules have extended procurement cycles; optics and sensor inflation drove a reported average system price increase in 2025, altering total cost of ownership calculus.
- Geopolitical and trade constraints — New export controls and tariff regimes implemented in 2025 have introduced transaction friction for certain cross‑border equipment flows, forcing manufacturers to reconsider sourcing, localization and inventory strategies.
These vectors create a narrow window in 2026 where the right blend of timing, vendor selection and contract structure can materially improve yield, throughput and regulatory compliance while protecting margins from elevated capital costs.
Worldwide 3D Automated Optical Inspection Equipment in PCB Market
What the Report Delivers — Practical, Actionable Content
PW Consulting structures the report to be immediately usable by business leaders, not just descriptive. Key actionable components include:
- Market sizing and methodology: transparent assumptions, sensitivity tests and a replication guide so corporate planners can adapt the base model to their installed base and product mix.
- Seven‑scenario forecasting tool: baseline, upside and downside scenarios that quantify the P&L and CapEx implications of supply disruptions, tariff shocks and accelerated HDI adoption.
- Vendor benchmarking and scorecards: independent assessment across throughput, defect coverage, sensor modularity, analytics maturity and service footprint to support short‑listing and negotiation.
- Procurement and CapEx playbook: timing guidelines for purchase vs. lease, recommended contract clauses to mitigate long lead times, and a decision matrix for retrofit vs. greenfield inspection lines.
- ROI and TCO calculators: tailored templates for build‑versus‑buy, cycle‑time improvements, false‑call reduction and first‑pass yield uplift, enabling finance teams to fast‑track approvals.
- Compliance and certification roadmap: line‑level actions to achieve new standard thresholds and audit readiness across production sites.
- M&A and partnership screen: a prioritized list of strategic attributes to identify acquisitive or partnerable targets and integration playbooks for software and data assets.
Note: the report contains granular regional and end‑use splits, along with per‑technology market shares and unit pricing curves. Those detailed tables and the underlying datasets are reserved for the full report package.
Competitive Landscape — How Leading Vendors Are Shaping 2026 Strategies
The AOI vendor ecosystem remains moderately concentrated, with the top three suppliers commanding a meaningful share of market revenue and the top five accounting for over two‑thirds of measured market sales. That concentration drives faster dissemination of technology paradigms but also intensifies competition around service, analytics and platform extensibility.
- Koh Young Technology (Seoul, South Korea) : A recognized leader in high‑speed true‑3D imaging and AI‑augmented defect detection. Their recent launch of the Zenith Alpha C2+ at productronica in October 2025 underscores continued investment in edge AI and throughput enhancements that target high‑mix SMT lines.
- CyberOptics Corporation (Minneapolis, MN, USA) : Known for robust multi‑reflection suppression and high accuracy in complex packages. The SQ3000+ platform introduced in mid‑2025 extends capability to finer placement classes and 01005 components — a clear signal to OEMs producing miniaturized consumer and medical electronics.
- Viscom AG (Hannover, Germany) : Positioned to serve high‑volume and HDI production with a focus on resolution and process integration. Demonstrations at trade shows in 2025 emphasized incremental resolution gains that improve defect detection on dense interconnect boards.
- Test Research, Inc. (TRI) (Taipei, Taiwan) : Builds on AI‑driven analysis for paste and placement verification; its systems are commonly integrated into feedback loops within SMT lines for closed‑loop correction.
- SAKI Corporation (Tokyo, Japan) : Differentiates via sensor mechanics and compliance focus; recent certification milestones reflect a strategy to win in high‑reliability segments with tight tolerances.
- Mirtec Corporation (Oxford, CT, USA) and Nordson Test & Inspection (Carlsbad, CA, USA) : Both emphasize imaging resolution and hybrid inspection capabilities (AOI + AXI), addressing customers who need consolidated inspection footprints for mixed production runs.
For buyers, vendor selection is increasingly less about headline accuracy claims and more about integration capabilities, data fidelity across the production line, global service coverage and the ability to support compliance updates — attributes that the PW Consulting vendor scorecard quantifies.
Operational Risks and Procurement Considerations
- Supply chain: High‑resolution 3D camera modules faced average lead times of 16–20 weeks in late 2025. This compels planners to adopt long‑lead procurement windows or secure options in multi‑vendor supply cushions.
- Regulation and standards: 2025 updates to industry standards introduced tighter height‑measurement accuracy requirements for critical applications. Inspection systems must be validated for these thresholds as part of acceptance testing.
- Trade and tariffs: Export controls on advanced imaging sensors and new import tariffs in certain geographies altered landed costs and delivery timelines in 2025; companies should model “tariff shock” scenarios within CapEx plans.
- Price dynamics: Reported optics inflation contributed to an average market price increase in 2025, shifting many procurement conversations from sticker price to total lifetime cost, service agreements and upgrade routes.
Strategic Recommendations for 2026 Decision‑Makers
Actions we advise executives to prioritize this year:
- Segment investments by risk and revenue impact: accelerate AOI upgrades on boards that attach the highest warranty and field‑failure risk; defer low‑risk lines where manual inspection remains cost‑effective.
- Negotiate modularity: insist on sensor modularity and software licensing models that permit phased upgrades to manage cashflow and navigate potential export restrictions.
- Lock long‑lead components early: secure critical optics and spare parts via forward‑buy options or vendor consignment to avoid production interruptions.
- Embed inspection data into the digital thread: integrate AOI outputs with MES and SPC systems to create closed‑loop process optimisation, which often delivers faster ROI than hardware upgrades alone.
- Prepare for compliance audits: map product families to the updated measurement standards and run validation protocols during acceptance to avoid expensive retrofits.
- Evaluate service and localization: prioritize vendors with service nodes and spare inventories close to your production sites to reduce downtime risk in constrained markets.
- Leverage the market window for strategic M&A: given the market’s concentration, selectively acquiring sensor, software or analytics capabilities can accelerate differentiation while expanding installed base economics.
How to Use This Report in Your 2026 Planning Cycle
PW Consulting positions the report as both a strategic primer and an operational toolkit for executives, procurement leads and manufacturing engineers. Recommended next steps for organizations that purchase the report:
- Executive briefing: a 90‑minute, PW‑led session to translate forecast scenarios into board‑level decisions on CapEx and risk posture.
- Procurement workshop: use our vendor scorecard and negotiation checklist in vendor RFPs to compress evaluation timelines and reduce negotiation leakage.
- Operational pilot: deploy the ROI calculator and the compliance roadmap to a representative line to quantify first‑year uplift and payback timing.
- M&A screening: apply the strategic attributes checklist to identify acquisition targets or partnership candidates that close capability gaps.
The full report contains the complete datasets (regional and end‑use splits, per‑technology market shares, unit pricing curves, and a detailed vendor benchmarking matrix) that underpin the guidance above. These granular tables and downloadable models are intentionally exclusive to the full delivery to preserve the rigor and reproducibility of our analysis.
To request the full report, schedule an executive briefing, or license the dataset for integration into your CapEx planning systems, visit PW Consulting’s research portal or contact our sales team. PW Consulting’s Worldwide 3D AOI Market brief gives you the scenario frameworks, vendor intelligence and procurement playbooks you need to convert 2026 uncertainty into strategic advantage.
For detailed analysis of this topic, please visit the official page: Worldwide 3D Automated Optical Inspection Equipment in PCB Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Laundry RFID Tags Market Poised to Top USD 1.32B by 2032 at a 12.48% CAGR, Driven by UHF Segment (USD 496.11M)
By pmarketresearch, 2026-07-15
Worldwide Laundry RFID Tags Market — Strategic Imperatives for 2026
PW Consulting’s new market study on the Worldwide Laundry RFID Tags Market provides a pragmatic, decision-focused roadmap for executives preparing procurement, operations and digital-transformation initiatives in 2026. Based on a comprehensive 2020–2025 historical analysis and a 2026–2032 forecast horizon, the market reached USD 580.45 Million in 2025 and is projected to expand at a 12.48% compound annual growth rate (CAGR) through 2032, when it is expected to exceed USD 1.32 billion. These headline figures underscore a market moving beyond early pilots into mainstream capital and operational investments — and they set the scene for the tactical choices organizations must make this year.
Worldwide Laundry RFID Tags Market
Why this report matters to 2026 decision-makers
- Bridge from pilot to scale: The market dynamics and vendor innovations we document show that 2026 is a pivotal year for moving successful pilots into full-scale rollouts. The economics and technology readiness are aligning in ways that materially compress payback windows.
- Procurement timing and negotiation leverage: A clear view of supplier concentration, technology roadmaps and product differentiation enables procurement teams to design contracts that balance price, long-term support and upgrade pathways.
- Risk-aware adoption: The report translates technical certifications (sterilization endurance, medical-safety qualifications, industry wash-cycle tests) into decision rules for regulated buyers — particularly healthcare and medical textile managers — where failure modes have downstream clinical and regulatory consequences.
- Operational uplift and sustainability: We quantify the operational levers (inventory reduction, lifecycle extension, loss prevention) that make the business case for RFID compelling beyond labor savings — and provide a granular playbook for capturing them.
What the PW Consulting report delivers (practical contents)
- Robust market model — historical series (2020–2025), 2026 baseline and scenario-driven forecasts through 2032 with sensitivities and macroeconomic overlays.
- Vendor assessment toolkit — scorecards for supplier capabilities across durability, read-performance, integration flexibility, certifications, manufacturing scale and service footprint.
- Commercial templates — procurement RFP language, contractual SLAs, warranty and lifecycle replacement clauses tailored to laundry tag deployments.
- Implementation blueprints — pilot design templates, test matrices, systems-integration checklists (hardware, middleware, ERP/WMS/IMS integration), and a staged roll-out roadmap to minimize operational disruption.
- Financial models — configurable TCO and ROI calculators reflecting regional labor profiles, linen replacement cycles, expected savings from loss reduction and utilization gains.
- Compliance & risk matrix — mapping of relevant industrial certifications, sterilization and MRI-safety considerations and regulatory implications for hospital and clinical users.
- Primary research and case studies — interviews with leading suppliers and service providers, and anonymized client case studies showing realized savings and pitfalls to avoid.
Competitive landscape — what buyers need to know
The laundry RFID ecosystem is evolving from component vendors to integrated solution providers that combine durable tags, encoding and in-line attachment technologies, read infrastructure and software. Market concentration is meaningful: our analysis shows the top three suppliers currently account for roughly 42% of revenue, while the top five approach 59%, indicating a market with a clear set of market leaders but room for specialized entrants and regional champions.
Worldwide Laundry RFID Tags Market
- Datamars Textile ID (Lamone, Switzerland) — A long-standing leader with a full portfolio of tags, readers and systems. Their global installed base (over 10,000 installations and hundreds of millions of chips in use) gives them a service and scale advantage for large enterprise deployments. Recent product introductions focused on sterilization-hardening (gamma-resistant tags) point to targeted moves into medical textiles and sterilization-sensitive workflows.
- HID Global (United States) — Competes on durability and standards-compliance, offering product lines that emphasize medical certifications and textile-grade form factors. HID’s positioning appeals to regulated buyers who prioritize certifications (e.g., OEKO-TEX) and facilities requiring MRI-safe variants.
- Xerafy (Singapore) — Known for enterprise-grade UHF laundry tags engineered for high-cycle durability and strong bulk-read performance. Their move into print-ready roll formats with next-generation chips signals a push to lower operational friction for manufacturers and high-throughput laundries.
- JYL-Tech (Shanghai) — Focused on automation and volume production, their roll-format tag and production-line insertion capabilities target manufacturers and large linen producers looking to embed traceability at source.
- AXEM Technology (France), Positek RFID (US) and GAO RFID (Canada) — These companies demonstrate the geographic breadth and product specialization in the market, from high-durability European designs to custom tag reuse programs and waterproof/heavily washable HF/UHF solutions.
Together, these supplier moves — product launches for gamma resistance, roll-format tags compatible with GEN2X chips, and automated tag-on-label solutions — signal intensifying competition on three fronts: durability and sterilization resilience; manufacturability and ease-of-integration; and read performance at scale. Each of these vectors has direct procurement and technical implications for 2026 projects.
Worldwide Laundry RFID Tags Market
Key dynamics and risk factors shaping 2026 decisions
- Standards and interoperability: Widespread compliance with EPC Class 1 Gen 2 / ISO 18000-63 and global UHF band interoperability reduces integration risk, but buyers must validate tag-to-reader read performance in their specific processes (sorting tunnels, high-density carts, sterilization cycles).
- Durability vs. cost trade-offs: Passive UHF laundry tags span a price band that materially affects unit economics. Industrial-grade components tested for 200+ wash cycles come at a premium, but the report demonstrates breakeven points where higher upfront tag cost yields lower lifecycle spend through reduced replacements.
- Regulatory and safety constraints: Certifications (OEKO-TEX, EECC endurance testing) and MRI-conditional designations are non-negotiable for healthcare procurement. The emergence of gamma-resistant tags expands lifecycle use cases (sterilized textiles) but requires validation within hospital sterilization protocols.
- Supply chain and component risk: Chip-level supply dynamics, packaging options (rolls, heat-seal, sew-in, pouches) and manufacturing lead times can introduce program delays; procurement teams must bake lead-time and minimum-order risks into contracts.
- Operational change management: Technology alone does not deliver savings — process redesign, staff training and integration into linen lifecycle management are the critical path to realizing the often-cited operational gains (RFID implementations can reduce linen purchasing costs by 15–20% and linen losses by up to 50%).
Actionable recommendations for 2026
- Run fit-for-purpose pilots that mirror scaled operations. Include full lifecycle validation (wash cycles, sterilization, high-pressure dewatering) and measure read rates across the most challenging touchpoints. Use pilot results to codify tag selection criteria.
- Structure procurement for optionality. Negotiate phased purchase commitments with clear volume steps, price ladders, service credits for failure rates and flexible replacement windows to protect against rapid technology iteration.
- Prioritize supplier capabilities beyond price. Evaluate installation support, global service footprint, ability to supply roll-format tags for automated insertion, and demonstrated performance in comparable verticals (hospitality vs. healthcare vs. industrial laundry).
- Embed financial metrics into rollout gating. Tie go/no-go decisions to pre-defined TCO and utilization improvements (not just read-rate targets). Track linen utilization, shrinkage, turnaround times and replacement frequency as primary KPIs.
- Plan for data governance and systems integration early. Define the endpoint data model, retention policies and how tag reads will integrate with laundry management and ERP systems to prevent downstream rework.
- Build a risk register that includes sterilization compatibility, MRI safety where relevant, supplier concentration, chip sourcing, and reverse-logistics for failed tags or recycling programs.
How PW Consulting can accelerate your 2026 program
Our team combines industry-level market intelligence with hands-on deployment experience. For clients preparing 2026 initiatives we offer a modular engagement model: rapid market-readiness assessment, detailed vendor due diligence and scorecarding, pilot program management, and rollout oversight focused on capturing measurable ROI within 12–24 months. The full report includes the proprietary vendor scorecards, regional and use-case baselines, pricing elasticity analysis, and downloadable financial models that procurement and operations teams can use immediately.
Conclusion — why act now
With the market expanding at a double-digit CAGR and suppliers accelerating product innovation — from sterilization-hardened tags to print-ready roll formats and next-generation chip adoption — 2026 is the year to move from selective trials to disciplined, risk-managed scaling. The decisions you make this year about tag selection, supplier contracting, integration architecture and operational governance will determine whether RFID delivers incremental efficiency or a transformational step-change in linen management economics.
For a full breakdown of regional and end-user segmentation, the proprietary vendor scorecards, and the executable playbooks that will guide your 2026 decisions, download the PW Consulting Worldwide Laundry RFID Tags Market report or contact our industry team for a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Laundry RFID Tags Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Glass Fiber Sizing Agent Market Poised to Reach USD 1,059.21 Million by 2032, Expanding at a 6.18% CAGR
By pmarketresearch, 2026-07-15
Worldwide Glass Fiber Sizing Agent Market: Strategic Preview for 2026 Decision-Making
Executive snapshot
PW Consulting’s new market brief on the Worldwide Glass Fiber Sizing Agent Market positions senior executives and deal teams to act confidently in 2026. Our analysis shows a robust recovery and sustained expansion in demand for sizing chemistries and film-formers, with the total market rising from USD 515.42 Million in 2020 to USD 696.12 Million in 2025 and projected to reach USD 1,059.21 Million by 2032. The forecast period (2026–2032) reflects a compound annual growth rate (CAGR) of 6.18% — a trajectory that reshapes supplier strategies, product roadmaps, and investment priorities across the composites ecosystem.
Worldwide Glass Fiber Sizing Agent Market
Why this matters for 2026 strategic choices
-
Timing for capacity and capital allocation: The market’s mid-single-digit CAGR signals opportunity without the runaway risk that demands speculative capacity build-outs. Firms deciding on plant expansions, regional hubs, or toll-manufacturing partnerships in 2026 need to balance steady demand growth against the cost of regulatory compliance and downstream composite cycles.
Worldwide Glass Fiber Sizing Agent Market -
Product and portfolio prioritization: With regulators and OEMs tightening specifications, sizing-formulation differentiation (low-VOC, waterborne systems, silane coupling chemistry tuning) becomes a primary margin lever. R&D and commercialization calendars set in 2026 will determine who wins product placement with major composite fabricators by 2028–2030.
Worldwide Glass Fiber Sizing Agent Market -
M&A and partnership windows: Market concentration metrics indicate moderate consolidation — the top three firms account for roughly 38.5% of market value while the top five approach 56.1%. That concentration creates a structurally attractive environment for bolt-on acquisitions to scale distribution, lock in technology, or secure raw material access.
Market dynamics shaping decisions
-
Regulatory pressure and formulation reformulation: Long-established frameworks such as EU REACH are driving suppliers to reformulate and validate substitutes that maintain composite performance while reducing human and environmental risk. This trend elevates the value of compliance-ready chemistries and shortens windows for legacy-product monetization.
-
Shift to waterborne and low-VOC systems: Waterborne polyurethane dispersions and MAH-grafted polymer film formers are increasingly adopted to meet VOC constraints and, in some cases, food-contact standards. These material shifts impact not only product development but also manufacturing infrastructure (e.g., wastewater treatment, mixing lines) and supplier qualification processes.
-
Raw material and application co-dependencies: Sizing formulations are complex blends — typically combining water, silane coupling agents, film formers, lubricants, and functional additives — and their performance is highly sensitive to changes in resin and fiber manufacturing practices. Decision-makers must therefore consider integrated sourcing strategies and cross-supplier compatibility testing as part of any go-to-market plan.
-
End-market demand drivers: Transportation, wind energy, aerospace, construction and electrical sectors continue to influence sizing requirements, but each segment’s pace of adoption for advanced sizing chemistries differs. That heterogeneity favors suppliers that can provide flexible, application-specific solutions and rapid technical support for composite processors.
Competitive landscape — what to watch in 2026
-
Celanese (United States) — As a benchmark supplier of emulsion polymers (Resyn® and Vinamul®), Celanese continues to anchor premium thermoset reinforcement applications. Its strength is in consistent quality and global supply to major fiber producers; strategic moves to embed closer with composite OEMs will increase switching costs for customers.
-
Michelman (Cincinnati, OH, United States) — Known for Hydrosize® film-forming dispersions and the Hydrolube® lubricant family, Michelman’s product architecture targets both chopped strand and continuous fiber formats. A notable recent development: in February 2026 the company launched Hydrosize® 1202, a single-sizing solution intended to simplify inventory and qualification complexity across fiber types — a potential model for consolidation of SKUs across the industry.
-
Evonik Industries (Germany) — With silane-based DYNASYLAN® chemistries and VPS additives, Evonik focuses on coupling efficiency and high-speed fiber production reliability. Its offerings reduce breakage and optimize interface strength in composites — features that appeal to high-performance and high-throughput manufacturers.
-
BYK (ALTANA Group, Germany) — BYK’s MAH-grafted polymers and low-VOC film formers are positioned to capture demand in polyolefin composite applications where emissions and mechanical performance are critical. BYK’s cross-regional manufacturing footprint strengthens its responsiveness to regional manufacturing shifts.
-
Covestro (Germany) — Baybond® waterborne polyurethane dispersions and crosslinkers emphasize protection, adhesion, and regulatory-compliant grades (including food-contact approved variants). Covestro’s materials are attractive for customers requiring documented regulatory compliance across multiple jurisdictions.
-
Great Eastern Resins Industrial (GRECO, Taiwan) — GRECO’s high-solid aqueous polyurethane dispersions combine low viscosity with chemical and weather resistance, making them relevant to processors seeking high-load formulations without sacrificing handling.
-
Emsland Group (Germany) — Emsland leverages starch-based sizing (Emglass® series) for niche requirements including textile pre-sizing in electronics. Biobased alternatives present differentiated positioning where sustainability or specialized application compatibility are key decision criteria.
What our report delivers — practical components for 2026 action
The full PW Consulting report is structured to support executable strategies rather than abstract forecasts. Key deliverables include:
-
Market sizing and trend maps that span 2020–2032 with annual USD Million reporting and scenario-driven forecasts (base, upside, downside) tailored to different regulatory and raw-material volatility assumptions.
-
Rigorous supplier benchmarking that combines product capability matrices, regional production footprints, and go-to-market models to identify shortlists for partnership, procurement, or acquisition.
-
Technology and regulatory playbooks explaining compliance pathways (e.g., REACH, food-contact) and recommended validation roadmaps to accelerate introductions of reformulated sizings in major end markets.
-
Commercial due-diligence templates for M&A teams, including channel economics, qualification timelines, and integration risk assessments specific to sizing-agent assets and specialty polymer units.
-
Scenario-based investment guidance for capex, including sensitivity testing for raw-material price shocks and adoption curves for waterborne/low-VOC chemistries.
-
Actionable tables of prioritized use-cases, technical checklists for lab-to-production scaling, and a concierge service for bespoke data slices and supplier introductions.
Strategic recommendations for 2026
-
For sizing manufacturers: accelerate validation of waterborne and low-VOC platforms and offer conversion support kits (process parameters, small-batch trials, and technician training) to reduce qualification friction for customers.
-
For composite producers: insist on supplier-signed regulatory dossiers and compatibility studies when qualifying sizing agents; prioritize suppliers who can co-develop application-specific formulations to shorten time-to-qualified part.
-
For investors and acquirers: focus on targets that bring either unique formulation IP, validated low-emission chemistries, or regional manufacturing that closes logistical gaps for major fiber producers — these assets will generate disproportionate strategic value given the market’s moderate concentration.
-
For raw-material suppliers: engage upstream with sizing formulators to secure long-term contracts for specialty monomers and silane chemistries; co-funded development programs are an efficient way to lock preferred supply and accelerate market adoption.
-
For regulators and standards bodies: collaborate with industry groups to establish test protocols that speed cross-border acceptance of low-VOC and waterborne sizings while preserving safety and performance benchmarks.
Next steps — how to use this preview
This briefing is intentionally designed as a strategic “trailer”: it demonstrates the depth of our market modeling, the relevance of recent supplier developments (for example, Michelman’s single-solution launch in February 2026), and the operational imperatives facing leaders in 2026. The full PW Consulting report contains granular segment breakdowns, regional dynamics, and downloadable datasets that power procurement scorecards, M&A underwriting models, and R&D roadmaps.
Contact PW Consulting to access the complete Worldwide Glass Fiber Sizing Agent Market report, request customized scenario modeling, or commission a supplier due-diligence package. Our team will provide the detailed segment-level intelligence and proprietary worksheets that underpin confident capital and product decisions for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Glass Fiber Sizing Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Zinc L‑carnosine Market to Hit USD 205.77 Million by 2032 at a 6.15% CAGR — Asia Pacific Leads with USD 62.08 Million (2025 base year)
By pmarketresearch, 2026-07-15
Zinc L‑carnosine Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
Executive snapshot
The Zinc L‑carnosine market has evolved from a niche therapeutic ingredient into a globally traded API and specialty nutraceutical input. Our PW Consulting Zinc L‑carnosine Market report (base year 2025, historical 2020–2025, forecast 2026–2032) synthesizes primary supplier intelligence, regulatory mapping, and multi‑scenario financial modelling to support executive decision‑making in 2026. Key macro takeaways: the market reached USD 135.5 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 6.15% through the 2026–2032 forecast window, reaching approximately USD 205.8 Million by 2032. Market concentration is meaningful—our analysis shows the top three players account for roughly 42.5% of market supply and the top five for about 58.2%—creating both risk and opportunity for strategic entrants and incumbents.
Zinc L-carnosine Market
Why this report matters for 2026 choices
-
Timing and trajectory: 2026 is the inflection year for several regulatory and commercial vectors. Modest but steady end‑market growth, paired with emerging scientific interest beyond gastroenterology, creates a window for differentiated positioning before the market becomes commoditized.
Zinc L-carnosine Market -
Regulatory strategy shapes commercial access: Zinc L‑carnosine occupies different regulatory categories across jurisdictions—approved drug in some Asian markets, dietary supplement in many Western markets, and an emerging Novel Food dossier in Europe. These classifications determine evidence burden, pricing power, and distribution channels.
Zinc L-carnosine Market -
Supply‑side concentration and certification requirements (USDMF, JDMF, WHO‑GMP, halal/kosher, cGMP) mean supplier qualification and vertical integration choices in 2026 will materially affect cost, launch timelines, and reputational exposure.
-
Intellectual property and branded originators: the presence of an established originator and reference product(s) positions players differently for clinical partnerships, licensing, and generics development—an important consideration for portfolio and M&A teams.
What the PW Consulting report delivers (practical scope)
-
Robust market sizing & forecasting: granular topline trajectory (2020–2032) with sensitivity scenarios and demand drivers modelled across macroeconomic, clinical, and retail trends to stress‑test business plans.
-
Segmented opportunity matrices: demand levers by regulatory channel (pharmaceutical vs nutraceutical), formulation pathway (API vs finished formulations), and customer archetypes—presented in an actionable format for prioritization. Note: the full, detailed split tables and downloadable datasets are restricted to the full report.
-
Competitive intelligence pack: supplier dossiers for originators, established API producers, and emerging entrants—covering certifications, capacity indicators, recent filings, and likely strategic intents.
-
Regulatory and clinical landscaping: jurisdictional treatment of zinc L‑carnosine (from prescription drug status in some Asian markets to dietary supplement categorization in Western markets), recent filings and bioequivalence references, and an evidence roadmap for claim substantiation.
-
Supply chain and procurement toolkit: risk heatmaps, qualification checklists, contract templates, and benchmarking guidance for price and lead‑time negotiations.
-
Commercial playbooks: channel entry options, co‑promotion strategies with gastroenterology outlets, premiumization levers for nutraceutical positioning, and a go‑to‑market decision framework tuned to differing regulatory outcomes.
-
M&A & partnership yardstick: valuation lenses, due diligence checklists specific to zinc L‑carnosine assets, and scenario valuation routines for bolt‑on vs platform acquisitions.
Competitive landscape — profiles and tactical implications
The competitive fabric of this market blends a long‑standing originator with a distributed base of regional API specialists and ingredient suppliers. The landscape is best understood through three archetypes: originator/brand custodians, established API manufacturers with regulatory filings, and high‑volume commodity suppliers.
-
Originator / brand custodians — companies that own the reference branded formulations and associated clinical legacy. They are gatekeepers for clinical comparators and possess the regulatory dossiers that can be leveraged in licensing or co‑development agreements. These firms tend to prioritize scientific evidence and controlled commercialization pathways.
-
Regulatory‑filed API manufacturers — firms that have invested in DMFs/filings (USDMF, JDMF, WHO‑GMP, etc.) and therefore provide higher assurance to multinational pharmaceutical customers. Recent active filings and registration updates indicate a maturation of supply capable of servicing regulated markets.
-
High‑volume commodity suppliers — producers whose value proposition is scale and cost competitiveness, often servicing nutraceutical formulators and regional pharmaceutical manufacturers. These players are pivotal to price dynamics and inventory flexibility.
Recent, adjudicative events that will shape competitive moves in 2026 include: an active USDMF submission from a Chinese API producer (submitted in early 2025), additional Japanese DMF registrations from China‑headquartered suppliers, a bioequivalence reference study leveraging the Japanese reference granule product in 2025, and a 2026 scientific review widening interest in therapeutic applications beyond gastroenterology. These events collectively lower regulatory friction for global pharmaceutical adoption while simultaneously stimulating generic substitution and label expansion activity.
Supply‑side and regulatory dynamics to watch
-
Certification premium: USDMF/JDMF/WHO‑GMP filings materially increase addressable pharmaceutical demand; suppliers without these filings will remain concentrated in supplementary channels.
-
Regulatory bifurcation across markets: treatment as a prescription product in certain Asian markets versus a supplement in many Western markets creates parallel commercialization playbooks—each with different evidence and distribution requirements.
-
Concentration risk: with a meaningful share of supply held by a handful of firms, procurement teams must quantify single‑supplier exposure and plan dual‑sourcing or contract manufacturing strategies accordingly.
-
Scientific momentum: expanding literature that re‑evaluates the zinc‑L‑carnosine combination for broader therapeutic roles has the potential to shift demand composition from supplement to prescription channels over the medium term.
Strategic recommendations for executives in 2026
-
Synchronize regulatory and commercial plans: map regulatory category by target market and align evidence generation (bioequivalence, clinical endpoints) with intended claims and channel strategy before committing to large‑scale supply agreements.
-
De‑risk procurement through staged qualification: prioritize suppliers with active regulatory dossiers for markets where prescription status applies; for nutraceutical channels, secure long‑term contracts with flexible volume clauses to manage spot price volatility.
-
Invest in differentiated clinical evidence: a modest investment in targeted clinical or mechanistic work can unlock higher margin medical channels and protect against rapid commoditization in supplement markets.
-
Consider partnership routes with originator brands: licensing, co‑promotion, or supply arrangements with originator firms accelerate market entry and provide comparative reference products for regulatory filings.
-
Prepare for M&A windows: with supply consolidation and regulatory filings accelerating, 2026 is likely to be fertile ground for bolt‑on acquisitions—use our M&A yardstick and scenario valuations to screen targets.
How to use this preview and next steps
This article is a strategic preview designed to surface the critical decision levers for 2026. The full PW Consulting Zinc L‑carnosine Market report contains the detailed datasets, supplier dossiers, segmented demand tables, price benchmarking, and downloadable financial models that commercial teams, procurement leads, regulatory affairs, and corporate development groups will need to execute with confidence. To access the complete intelligence package—including the granular regional and application splits that underpin tailored go‑to‑market plans—please visit our report page.
For bespoke consulting engagements, scenario runs customized to your product portfolio, or confidential supplier diligence informed by our supplier interviews and primary supply‑chain checks, PW Consulting’s industry team is available to support rapid decisioning throughout 2026.
For detailed analysis of this topic, please visit the official page: Zinc L-carnosine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cephalosporin Intermediates GCLE Market Set to Grow at a 5.4% CAGR, New 2025–2032 Insight Reveals
By pmarketresearch, 2026-07-15
Cephalosporin Intermediates (GCLE) Market — Strategic Preview for 2026 Decision-Making
PW Consulting’s new market research brief on Cephalosporin Intermediates GCLE delivers a focused, practice-oriented view designed to inform executive choices in 2026. The analysis synthesizes historical performance (2020–2025), a base-year diagnostic (2025), and a forward-looking forecast window (2026–2032). This preview highlights the strategic implications — from supply-chain fragility to competitive positioning — that will determine winners and losers as the GCLE landscape evolves. For full datasets, regional splits, and proprietary scorecards, refer to the complete report on our website.
Cephalosporin Intermediates GCLE Market
Executive snapshot — market direction and scale
The GCLE intermediate market has demonstrated resilience through the past half-decade. From a 2020 baseline the industry expanded steadily to reach approximately USD 392.36 Million in 2025. PW Consulting’s scenario-driven forecast models a compound annual growth rate (CAGR) of 5.4% across 2026–2032, producing an estimated market outcome near USD 567.0 Million by 2032 under our central case. These headline figures encapsulate demand tied to cephalosporin active pharmaceutical ingredient (API) production, shifts in grade mix (high-purity vs. standard), and structural supply-side dynamics that are relevant for procurement, capacity investment, and M&A planning in 2026.
Cephalosporin Intermediates GCLE Market
Why this report matters for 2026 corporate strategy
- Actionable signal amid structural concentration: Market concentration metrics indicate meaningful clustering among leading suppliers. That concentration amplifies the strategic value of supplier negotiation, alliance formation, and acquisition tactics in 2026.
- Raw-material dependency risk: Key inputs underpinning GCLE manufacture are sourced from a narrow geographic set of suppliers, creating asymmetric exposure to logistics, trade policy, and quality volatility — a top priority for procurement teams.
- Regulatory arbitrage and export policy: Recent policy windows allow specific import concessions for export-oriented antibiotic production in some jurisdictions. Capturing these regulatory advantages requires precise operational timing and compliance readiness.
- Margin recovery and premiumization: Growth is not uniform across the product-grade spectrum. High-purity grades are a critical driver of margin expansion and contract differentiation.
What’s inside the full PW Consulting report (practical components)
Our report is designed as a toolset for decision-makers, not just a descriptive summary. The deliverables include:
Cephalosporin Intermediates GCLE Market
- Scenario-based demand models (2026–2032) with sensitivity levers for price, capacity outages, and shipment-cost shocks.
- Supplier and asset scorecards combining capacity, quality certifications, geographic exposure, and counterparty risk.
- Regulatory impact map showing how authorization schemes and trade measures alter landed cost across export corridors.
- An operational playbook for raw-material risk mitigation: inventory policy designs, hedging tactics, and recommended contractual clauses.
- Capital deployment guidance: cost-to-build benchmarks for incremental GCLE capacity and payback simulations under conservative and aggressive uptake scenarios.
- Deal flow shortlist and diligence checklist tailored for acquisitive strategies targeting upstream intermediates and logistics nodes.
- Plant-level contamination and quality failure risk matrices with remediation timelines — practical for QA/QC and manufacturing heads.
Each component is supported by our proprietary database and verified market-sourcing interviews; however, detailed subsegment numbers and regional shares are intentionally gated to ensure this preview preserves the full report’s strategic value.
Competitive landscape — who moves markets and why
The GCLE supplier ecosystem reflects a mix of established multinational chemistry houses, specialized intermediate manufacturers, and regional listed players. From a strategic standpoint, three seller archetypes matter:
- IP-backed, scale incumbents: Firms that originated or own key β‑lactam intermediate processes and have integrated manufacturing footprints. They bring predictable quality, backward integration potential, and leverage in premium segments.
- Cost-advantaged regional manufacturers: Producers focused on scale, low-cost feedstocks, and a volume play for standard grades. Their strengths show up in price-sensitive contracts but expose purchasers to quality and concentration risks during supply shocks.
- Emerging contract-focused suppliers: Smaller producers and toll manufacturers that provide flexibility for API houses requiring rapid capacity adjustments or bespoke purity specifications.
Notable market participants profiled in the report include major Japanese specialty-chem players with dedicated β‑lactam lines; a cohort of listed Chinese manufacturers with significant GCLE activity; and focused Indian producers who are active partners in the cefixime and broader cephalosporin export value chain. Our competitive assessment evaluates each on capacity elasticity, geographic diversification, relationship capital with API customers, and exposure to raw-material sourcing constraints.
Supply-chain dynamics and critical risk vectors
Three structural dynamics dominate the GCLE supply picture and should shape 2026 priority decisions:
- Single-sourced raw material exposure: Penicillin‑G is the foundational feedstock for GCLE synthesis and, in practice, remains concentrated in a limited number of suppliers. That sourcing geometry limits rapid re-routing options during capacity disruptions and elevates inventory strategy to a strategic discipline rather than an operational afterthought.
- Export-oriented regulatory windows: Some jurisdictions have implemented advanced authorization measures that temporarily relax minimum import price restrictions for specific export uses. These measures can materially alter landed-cost economics — but exploiting them demands tight coordination between customs, production scheduling, and sales planning.
- Logistics inflation and bottlenecks: High international freight costs and container shortages periodically amplify landed cost and shrink the merit of distant-sourcing strategies. Firms that control or co-invest in logistics solutions secure a durable commercial edge.
Compounding these are technical challenges in several historic synthesis routes — uneven yields, impurity profiles that complicate downstream API synthesis, and quality variance across suppliers. These technical factors directly influence grade mix economics, regulatory approval timelines for APIs, and ultimately patient access chains.
Strategic imperatives for executives in 2026
Based on our assessment, PW Consulting recommends a prioritized set of moves for mid- to large-sized organizations operating in the GCLE value chain:
- Lock in multi-year, conditional supply contracts: Prioritize contracts that combine volume certainty with quality KPIs and clause-based price adjustments tied to documented input-cost indices.
- Invest selectively in high-purity capability: Build or acquire capacity that can deliver above-99% grades. Premiumization in this tier delivers asymmetric margin uplift and customer stickiness.
- De-risk penicillin-G dependence: Explore joint ventures upstream, targeted equity stakes in feedstock producers, or long-term offtake agreements with financial conditioning to secure throughput.
- Operationalize regulatory arbitrage: Align commercial calendars with advanced authorization windows and ensure compliance processes are audit-ready to access import concessions.
- Embed logistics resilience: Negotiate priority container capacity, invest in bonded warehousing closer to primary export ports, and model landed-cost shocks monthly.
- Prioritize bolt-on M&A where concentration creates rent opportunities: Small-to-medium acquisitions can yield integrated margins faster than greenfield builds in constrained supply scenarios.
- Make QA/QC investments non-negotiable: Failure to pass key impurity specification gates imposes multi-month revenue losses; remediation is costly and reputationally harmful.
How PW Consulting’s report supports execution
Our full deliverable translates the high-level imperatives above into executable workstreams: negotiation playbooks with contract text templates, an asset capex decision tree, an M&A due-diligence pack, and an interactive demand-supply model where clients can stress-test scenarios (logistics shocks, feedstock failure, price moves). Importantly, we provide a supplier risk heat map and a prioritized action list that a procurement or corporate development team can operationalize within 90–180 days.
To respect the “trailer” principle, this preview intentionally omits granular regional and application splits, as well as detailed supplier scorecard metrics. The complete report contains those specifics, including validated plant maps, contract examples, and a ranked list of acquisition targets with indicative valuation bands.
Next steps for leaders
If your 2026 strategy hinges on cephalosporin value capture — whether through securing cost-of-goods, enhancing product quality, or executing bolt-on capacity plays — this PW Consulting report provides the scenario-tested playbook you need. Access the full research package for detailed segmentation, supplier-level analytics, and the interactive models that translate market signals into boardroom-ready decisions.
For detailed analysis of this topic, please visit the official page: Cephalosporin Intermediates GCLE Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Taxi and Limousine Services Market Set to Reach USD 572.74 Billion by 2032
By pmarketresearch, 2026-07-15
Worldwide Taxi and Limousine Services Market — Strategic Outlook for 2026 Decision‑Makers
Executive summary
PW Consulting’s newest market study on the Worldwide Taxi and Limousine Services market provides a decision‑grade strategic blueprint for firms, investors, and public authorities preparing for the next major inflection in ground transportation. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the study documents a robust market expansion driven by digital platforms, fleet modernization, and regulatory acceleration. The market grows from an estimated USD 312.45 Billion in 2025 to an anticipated USD 572.74 Billion by 2032, reflecting a compound annual growth rate (CAGR) of 9.04% across the forecast period. That growth rate masks considerable structural shifts—opportunity for incumbents, threat to legacy operators, and an opening for new business models that combine fleet services, software, and regulated mobility.
Worldwide Taxi and Limousine Services Market
Why this report matters for 2026 strategy
- Timing is critical. 2026 is the decision year for many fleet electrification and accessibility programs shaped by regulatory milestones. Operators who align capital deployment with regulatory windows will enjoy lower compliance cost and faster market access.
- Clear playbooks reduce execution risk. The report translates macro forecasts into 18 actionable workstreams—covering EV transition sequencing, airport and corporate channel capture, WAV conversion financing, and dynamic pricing—so leaders can move from ambition to delivery within 12 months.
- Investor signal clarity. The market’s structural concentration is moderate: the top three players account for a material share of global platform volume and the top five widen that position further. This creates differentiated return profiles for platform‑scale business models versus local fleet specialists.
What the report contains — practical tools, not just theory
Designed for boards, corporate strategy teams, city transport planners and PE/Growth investors, the study emphasizes execution. Among the deliverables:
Worldwide Taxi and Limousine Services Market
- Proprietary market modeling calibrated to 2025 base conditions and stress‑tested across regulatory and energy‑price scenarios for 2026–2032.
- Fleet transition playbook including TCO calculators, total operating cost curves for different vehicle pathways (internal combustion, hybrid, battery EV), and recommended phasing by fleet type and route profile.
- Regulatory tracker and compliance roadmap with milestone‑level checklists for jurisdictions enacting zero‑emission mandates and Clean Miles standards.
- Commercial go‑to‑market blueprints for airport concessions, corporate mobility programs, and premium chauffeur services—each with tender readiness templates and KPI scorecards.
- M&A and partnership heatmap highlighting high‑value targets, alliance archetypes, and integration pitfalls based on recent deal flow and capitalization dynamics.
- Operational analytics toolkit: driver retention and incentive designs, utilization optimization algorithms, and sample dynamic pricing matrices aligned to volume and yield levers.
Competitive landscape — where incumbents and challengers stand as 2026 approaches
The global marketplace features platform giants, regional champions, and a dense layer of local operators and chauffeured specialists. Our competitive assessment focuses on strategic posture, competitive advantage, and execution risk for core players:
Worldwide Taxi and Limousine Services Market
- Uber Technologies Inc. — A global platform leader with broad product depth (from economy rides to premium black‑car services). Strengths include scale effects in demand aggregation, payments, and multi‑service bundling. Risks: regulatory scrutiny in major markets and capital lightness in certain regional portfolios.
- Lyft Inc. — North American challenger with strong urban market penetration and enterprise contracts. Its strategic choices in 2026 should emphasize differentiated corporate mobility propositions and cost discipline to defend margins against intensifying EV investments.
- Didi Chuxing — Dominant in China with a growing international footprint. Key advantages are local market intelligence and scale in Asia; risks include geopolitical sensitivity and the need to localize governance models abroad.
- Grab Holdings Inc. — A Southeast Asian super‑app that leverages payments and delivery to drive ride demand. Its opportunity lies in cross‑sell and captive ecosystems, but profitability depends on continued monetization of non‑ride services.
- Bolt, Ola, Cabify and regional platforms — These players compete on pricing, local partnerships, and regulatory agility. Their success in 2026 will hinge on selective market consolidation and strategic alliances (e.g., with vehicle OEMs and local authorities).
- Premium and chauffeured specialists (Gett, Addison Lee, Blacklane, Carey, EmpireCLS) — These operators compete on service quality, corporate procurement relationships, and safety certifications. Demand for security‑focused, professional chauffeur services is rising, offering a high‑margin corridor for expansion.
- Government and municipal fleets (e.g., Dubai Taxi Corporation, Nihon Kotsu) — These operators combine regulatory privilege with public service mandates (e.g., WAV, airport linkages). Their strategic play is to modernize fleets while preserving service reliability and social objectives.
Regulatory and operational dynamics shaping 2026 decisions
Policy forces and operational realities are converging. Key dynamics we track:
- Zero‑emission mandates and Clean Miles standards. Multiple jurisdictions have set 2030–2035 deadlines for zero‑emission fleets or high EV mileage targets, and regulators will expect interim compliance plans in 2026 and 2028. Operators must translate these mandates into capex schedules, charging rollouts, and energy procurement strategies.
- Accessibility requirements. Governments are increasing support for wheelchair‑accessible vehicles (WAV) through grants and subsidies. Capturing these programs lowers conversion costs and opens new customer segments but requires retrofitting and training investments.
- Fleet modernization from municipal programs. Examples such as recent fleet modernization and charging infrastructure expansion initiatives demonstrate how public–private coordination can rapidly accelerate EV adoption and accessibility improvements.
- Premium segment acceleration. Corporate demand for secure, trained chauffeur services is rising. This trend favors operators that can certify driver training, embed advanced safety tech, and deliver consistent SLA‑level service nationally or globally.
Strategic playbook for 2026 — prioritized actions
For leaders who must decide in 2026, PW Consulting recommends a prioritized, three‑tiered plan:
- Immediate (0–12 months) : Complete regulatory gap analysis and build compliance roadmaps; secure pilot partnerships for EV charging at high‑utilization depots; tender for corporate and airport contracts with staged capacity commitments.
- Medium (12–36 months) : Execute fleet transition in cohorts informed by route analytics and TCO modeling; deploy WAV conversion programs leveraging public grants; implement driver retention incentives tied to performance and upskilling.
- Longer term (36–72 months) : Scale premium chauffeured services through white‑label partnerships; pursue targeted M&A to acquire last‑mile electrification capabilities or to consolidate fragmented urban markets; institutionalize carbon and accessibility reporting to capture ESG premiums.
How to use this report in your 2026 planning cycle
This study is structured to move teams from insight to execution: board briefings, a modular strategy playbook, downloadable models and scenario simulators, and a procurement briefing pack for fleet and energy sourcing. The core value is not only the headline market projection, but the diagnostic layers—policy timelines, operating unit economics, and commercial contracting templates—that let you quantify tradeoffs and prioritize capital allocation in 2026.
A final note on the depth of our analysis
To build trust with executive teams, PW Consulting provides transparent methodology and source references while preserving client value through proprietary segmentation and scenario outputs. The public summary here presents the headline growth trajectory and major dynamics. The full report contains granular segment forecasts, regional and service‑type breakdowns, company benchmarks, and downloadable decision‑support tools that are deliberately withheld from this preview to maintain competitive integrity and to offer a reasoned path to engage the full dataset.
Next steps
If your 2026 capital plan, regulatory compliance timetable, or M&A horizon touches taxi or limousine services, PW Consulting’s Worldwide Taxi and Limousine Services Market study is mission‑critical. Access the full report for segment‑level forecasts, detailed competitor scorecards, and the operational toolkits needed to convert the market’s growth into sustained value. For bespoke briefings and scenario workshops tailored to your portfolio, contact PW Consulting’s Mobility Strategy team.
For detailed analysis of this topic, please visit the official page: Worldwide Taxi and Limousine Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Surface Water Measuring Instrument Market to Grow at a 6.72% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Surface Water Measuring Instrument Market: Strategic Primer for 2026 Decision-Makers
Executive summary
As markets re-price risk and resilience following successive extreme-weather years, surface water monitoring has moved from a niche technical discipline to an operational imperative across public utilities, river basin authorities, industrial end-users, and agricultural management systems. PW Consulting’s new Worldwide Surface Water Measuring Instrument Market report — built on a 2020–2025 historical baseline and a 2026–2032 forecast horizon — quantifies that transition: the global market, measured in USD Million, expanded materially through 2025 and is projected to continue on a mid-single-digit compound annual growth trajectory (6.72% CAGR over the forecast period). Our baseline and forecast figures provide a clear demand envelope for capex planning and product roadmaps as companies prepare strategies in 2026 and beyond.
Worldwide Surface Water Measuring Instrument Market
Why this matters for 2026 strategy
2026 is a pivot year for many organizations. Capital programs budgeted in 2025 are entering execution; standards and procurement specifications are being updated to reflect new sensing technologies; and regional agencies are accelerating IoT-enabled deployments for flood warning, water resource optimization, and regulatory compliance. For equipment manufacturers, integrators, and large buyers, the value of market intelligence in 2026 is three-fold:
Worldwide Surface Water Measuring Instrument Market
- It aligns product development timelines with the window of peak procurement activity for multi-year public and utility tenders.
- It guides go-to-market investments — determining where to prioritize channel expansion, telemetry partnerships, and systems integration capabilities.
- It supports M&A and partnership screening by identifying capability gaps (e.g., integrated flood-monitoring platforms, low-maintenance radar sensors, or robust telemetry stacks) versus market demand trajectories.
Market trajectory at a glance
Our analysis shows a clear, sustained expansion from the mid-2020s baseline. The market recorded steady growth through the 2020–2025 period and enters the forecast phase with momentum driven by three structural forces: the migration to non-contact radar sensors for regulatory-compliant surface level measurement, the rise of integrated IoT flood-monitoring systems, and broader digitization of environmental monitoring programs. By 2026 the market continues to grow, with forecast values reflecting both continued public-sector investment in hydrological infrastructure and incremental commercial adoption by industrial and agricultural users.
Worldwide Surface Water Measuring Instrument Market
What the report contains — practical, actionable intelligence
This is not a summary of press releases. PW Consulting’s report is designed for executives who need to act. Key deliverables include:
- Market sizing and multi-scenario forecasts (base, upside, downside) through 2032, with clear assumptions and sensitivity bands to stress-test capex plans.
- A buyer-centric segmentation framework that maps instrument types and solution architectures to procurement decision drivers (accuracy, maintainability, telemetry compatibility, lifecycle cost).
- An evaluation of technology adoption pathways — from legacy pressure transducers to 80 GHz FMCW radar level sensors and integrated IoT platforms — with deployment case studies and failure-mode analysis.
- Vendor capability matrices and decision trees that support shortlisting for RFPs, supplier rationalization, and partner selection.
- Operational-playbook appendices: specification checklists, suggested test protocols to validate supplier claims in the field, and procurement language to ensure long-term data interoperability.
Strategic recommendations for 2026
Organizations that treat this market as a one-off hardware purchase will be disappointed. The levers that create sustained advantage are platform, data, and service. Our report highlights the following near-term actions:
- Shift procurement evaluation to lifecycle metrics. Emphasize mean time between failures, remote calibration capability, and end-to-end telemetry security in 2026 RFPs.
- Prioritize radar and IoT interoperability on critical deployments. Emerging radar technologies deliver lower maintenance and higher uptime; pairing them with open telemetry stacks accelerates actionable analytics.
- Invest in small-scale pilots that test integrated flood-monitoring workflows (sensor → edge device → cloud analytics → alerting). Rapid pilots in 2026 de-risk larger 2027–2028 rollouts.
- Consider horizontal partnerships (software, telco, systems integrators) rather than purely horizontal product expansion — service-led models are increasingly differentiated.
Competitive landscape — what leading firms are doing
The market is composed of established instrumentation specialists, multi-discipline water technology firms, and a growing set of systems integrators embedding sensors into value-added services. Our competitive analysis synthesizes public disclosures, product launches, and strategic transactions to surface where incumbents are consolidating capabilities or pivoting to platform plays.
- Campbell Scientific (Logan, UT) continues to be recognized for rugged, unattended systems and a strong datalogger ecosystem. Its alignment with regulatory accuracy expectations makes it a default choice for conservative hydrological programs.
- Solinst (Georgetown, ON) strengthened its water quality and level offering through an acquisition completed in early 2025, signaling a deliberate move to broaden its multiparameter portfolio and provide tighter integration between probes and dataloggers.
- OTT HydroMet (Kempten, Germany) has been active on the radar and system-integration front, launching next-generation 80 GHz FMCW radar sensors and bundled flood-monitoring systems that illustrate the shift from component sales to monitored-solution offerings.
- Seametrics (TASI Flow Group), Xylem (including YSI/Global Water), Badger Meter, and in-situ firms remain important players in flow, level, and multiparameter sensing — each emphasizing different vertical routes to market (municipal utilities, industrial OEMs, coastal and HAB monitoring).
- Specialist vendors such as Stevens Water Monitoring Systems, Aquaread, KISTERS, Heron Instruments, and others differentiate through long-tail technical features, data acquisition ecosystems, and legacy customer relationships that are valuable in conservative procurement environments.
Taken together, vendor activity reinforces a market dynamic where product innovation (sensors with lower maintenance and higher accuracy), system integration (sensor + edge + cloud), and commercial model innovation (hardware-as-a-service, monitoring-as-a-service) are converging. For 2026 strategists, the question is not whether to engage — it is which capability gaps to close first.
Technology, materials, and regulatory context
Three contextual elements are reshaping procurement and product design:
- Materials engineering: Corrosion-resistant housings (316L stainless steel, titanium in harsher or saline environments) remain design drivers for long-deployment instruments. Decisions on materials impact unit cost and lifecycle maintenance schedules.
- Regulatory alignment: National hydrology offices and standards bodies increasingly reference accuracy requirements for non-contact radar sensors. Procurement teams should explicitly require demonstrated compliance with prevailing accuracy guidelines in vendor statements of compliance.
- IoT and analytics: The proliferation of low-power wide-area networks and edge analytics enables new monitoring architectures — embedded event detection at the edge, combined with cloud analytics for regional situational awareness, reduces data latency and total cost of ownership.
Use cases and sector-specific implications for 2026
Our scenario analyses bring the market to life across four archetypal end-users:
- Public hydrology and flood warning agencies — prioritize accuracy and network resilience; procurement cycles are multi-year and risk-averse.
- Agricultural water managers — seek low-cost, low-maintenance sensors that deliver seasonal irrigation optimization and drought response data.
- Environmental research and protection — value multi-parameter probes and open data architectures that support cross-disciplinary analysis.
- Industrial process and effluent control — require compliance-grade instrumentation that integrates with SCADA and plant control systems.
How to use the full report in 2026 planning
Leaders should use the report as a tactical planning toolkit. Examples of immediate applications:
- Capital budget alignment: Use our scenario outputs to stress-test CAPEX phasing and spare-parts provisioning.
- Supplier strategy: Apply the vendor capability matrices to shortlist for pilot contracts and to negotiate service-level agreements tied to uptime and data quality.
- Product roadmap validation: For OEMs, map R&D investment priorities against the technology adoption curves we provide — prioritize rugged radar sensing, telemetry, and data interoperability.
Concluding perspective and next steps
The surface water measuring instrument market in 2026 is a space where engineering, regulation, and digital transformation intersect. The market’s growth trajectory and procurement dynamics create opportunities for incumbents to expand into integrated services and for new entrants to disrupt through platform-enabled value propositions. PW Consulting’s Worldwide Surface Water Measuring Instrument Market report equips decision-makers with the quantitative baselines, risk-tested scenarios, and actionable playbooks necessary to make informed choices in 2026.
For executives seeking the complete dataset, detailed segmentation, and supplier-level appendices (including full split tables, regional and application segmentation, and a breakdown of market concentration), visit our report landing page to download the full research package and supporting tools. Engage with PW Consulting for tailored briefings or to commission scenario modelling aligned to your organization’s procurement and product-development timelines.
For detailed analysis of this topic, please visit the official page: Worldwide Surface Water Measuring Instrument Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com