

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide High-capacity NFC Chip Market Poised to Expand at a 12.71% CAGR During 2026–2032

Worldwide High-capacity NFC Chip Market: Strategic Imperatives for 2026 — PW Consulting Release
PW Consulting today publishes strategic highlights from our forthcoming Worldwide High-capacity NFC Chip Market report (base year 2025, historical 2020–2025, forecast 2026–2032). The market has moved from a niche enabler to a core architectural component in IoT, secure credentials, and consumer engagement. In this briefing we synthesize the macro trajectory, competitive dynamics, supply-side constraints and practical decision levers that senior executives should adopt in 2026. For readers seeking the granular regional and application splits, proprietary scenario models, and vendor-level revenue tables, the full report and datasets are available on our website.
Worldwide High-capacity NFC Chip Market
Why this market matters to enterprise strategy in 2026
-
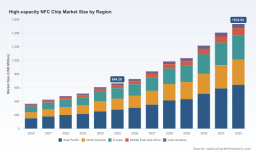
Market momentum: After expanding from roughly USD 365.4 million in 2020 to USD 664.28 million in 2025, the high-capacity NFC chip market is projected to continue rapid expansion, reaching approximately USD 1,534.92 million by 2032. Our forecasted compound annual growth rate for the 2026–2032 period is 12.71%. These dynamics reframe NFC chips from peripheral components to strategic enablers for product differentiation and platform monetization.
Worldwide High-capacity NFC Chip Market -
Structural concentration: The market exhibits meaningful concentration at the top. PW Consulting’s analysis places the three largest suppliers as a dominant block and the top five controlling a substantial majority of industry revenue — a structure that both stabilizes technology roadmaps and creates barriers for new entrants. This concentration elevates the importance of supplier strategy for enterprises that embed NFC functions into devices, packaging, and services.
Worldwide High-capacity NFC Chip Market -
Cross-industry reach: High-capacity NFC is no longer a single-use commodity. It supports secure onboarding (Matter and other frameworks), high-throughput credentialing for transit and payments, anti-counterfeiting for luxury goods, and data-rich cold chain monitoring. Expect procurement, product, and security teams to be primary stakeholders in NFC decisions from 2026 onward.
Report scope and operational value (what’s inside)
-
Market sizing and forecasting: Methodology, base-year reconciliations (2020–2025), and scenario-driven forecasts for 2026–2032 mapped to revenue outcomes under differing adoption and pricing paths.
-
Go-to-market playbooks: Actionable roadmaps for device OEMs, packaging companies, certification bodies and system integrators that convert NFC capabilities into monetizable features.
-
Supplier and technology benchmarking: Comparative evaluation of architectures (EEPROM vs. flash, multi-protocol combos), security primitives, memory density tiers and read-performance trade-offs.
-
Risk models and procurement tactics: Lead-time simulations, price sensitivity analysis, hedging strategies, and contract design templates to mitigate extended lead times and rising average selling prices.
-
M&A and partnership intelligence: Identification of attractive consolidation targets, strategic partnership matrices, and valuation sensitivities given the market’s concentration profile.
-
Primary research: Interview excerpts with system integrators, Tier-1 buyers and device manufacturers, plus an anonymized dataset of supplier lead-times and price movement observed in 2024–2026.
Competitive landscape — players to watch and their strategic postures
-
NXP Semiconductors (Eindhoven) — Positions itself as a performance leader for high-capacity tags with products focused on throughput, RF optimization and IoT-tailored features. Recent product introductions emphasize larger user memory and RF tuning capabilities, making NXP a natural partner for applications that require fast, reliable reads and tamper-aware deployment.
-
STMicroelectronics (Plan-les-Ouates) — Broad portfolio coverage with moves into secure onboarding for smart home ecosystems. Their recent secure-tag announcement targeting Matter 1.5 onboarding signals a strategic push into device commissioning and zero-battery provisioning, a capability that will influence smart-home product architectures and reduce friction in consumer device setup.
-
Infineon Technologies (Neubiberg) — Combines secure non-volatile technologies with multi-protocol flexibility, making it attractive where high-assurance contactless interaction (payments, identity, industrial controls) is required. Their emphasis on secure flash and flexible protocol stacks positions them well for regulated and industrial segments.
-
Broadcom Inc. (Palo Alto) — Plays to integration: combo chips that pair NFC with low-energy Bluetooth and other radios. This approach is compelling for mobile and wearable OEMs aiming to reduce BOM complexity while enabling cross-radio experiences.
-
Samsung Electronics (Suwon) — Focuses on mobile-first optimizations and cryptographic integrations; attractive to OEMs and service providers wanting tight integration between device firmware, secure elements, and NFC I/O.
-
Sony Corporation (Tokyo) — FeliCa-based solutions retain a strong position in transit and payment ecosystems where the standard remains entrenched. Sony’s deep ecosystem relationships mean long-term recurring demand in specific verticals.
Recent developments shaping supplier selection and risk
-
Product launches with security and onboarding features are accelerating supplier differentiation. Notable examples include high-performance HF tag ICs that raise throughput and advanced secure onboarding chips that enable battery-less commissioning. These functional differentiators should be evaluated as part of total cost of ownership, not just unit price.
-
Pricing and cost pressures: Several major vendors have implemented price increases in 2026, citing higher materials, energy and manufacturing costs. Buyers must model these increases into product pricing and negotiate indexation clauses or multi-year agreements to dampen P&L volatility.
-
Supply chain friction: Extended lead times for wafers and substrates — in some cases stretching to 30–40 weeks — have become a persistent constraint for advanced high-capacity variants. This drives a shift in procurement from just-in-time to just-in-case inventory strategies for critical SKUs and spurs interest in local or nearshore packaging partners.
-
Geopolitical and regulatory constraints: Export controls and trade measures affecting semiconductor components introduce execution risk for manufacturers with cross-border operations. Corporates must incorporate regulatory scenarios into sourcing and dual-sourcing plans to maintain production continuity.
Strategic recommendations for 2026 decision-makers
- -
-
Translate NFC capability into differentiated product outcomes: Prioritize features that map to revenue — secure credentialing, frictionless onboarding, anti-counterfeiting — rather than treating NFC as a checkbox. Product managers should quantify the incremental ARPU or cost savings enabled by NFC use cases.
-
-
Re-evaluate procurement architecture: Move from purely transactional sourcing to strategic supplier partnerships. Negotiate priority allocation, capacity reservations, and supply-backed SLAs for high-value programs. Where feasible, stagger purchase commitments across multiple suppliers to mitigate single-vendor disruptions.
-
-
Build variant-aware inventory playbooks: For products relying on higher-capacity NFC variants, create inventory buffers and adopt dynamic allocation logic tied to manufacturing cadence and sales velocity.
-
-
Invest in standards and onboarding ecosystems: Support and adopt interoperable onboarding standards (e.g., Matter-related flows) to reduce customer friction and lower returns. Working with suppliers that provide strong support for modern onboarding paradigms can shorten time-to-market for connected products.
-
-
Pursue targeted R&D and IP plays: Given the market’s concentration, invest in software and integration IP (secure provisioning, OTA management, lifecycle analytics) that capture margins beyond component sales. Consider licensing or co-development deals with dominant IC vendors to lock in technical roadmaps.
-
-
Evaluate M&A and partnership windows: The current market structure and growth profile create opportunities for strategic bolt-ons — from packaging players to authentication-service providers — that can accelerate time-to-revenue and strengthen differentiation.
What PW Consulting recommends as next steps
For C-suite and business unit leaders planning 2026 investments, we recommend a three-step program:
-
Conduct a use-case prioritization workshop to quantify the commercial impact of NFC-enabled features across product lines.
-
Perform a supplier-risk audit that maps current contracts, lead-times and exposure to regulatory constraints; implement immediate sourcing mitigations where single points of failure exist.
-
Commission a pilot that combines high-capacity tags, secure onboarding, and lifecycle telemetry to validate both technical integration and a monetization model (subscription, data licensing, or reduced churn).
Final note — why consult the full report
This briefing distills high-level strategic implications from our full Worldwide High-capacity NFC Chip Market study. The complete report contains the granular, actionable intelligence procurement teams, product leaders and corporate strategists require: detailed scenario models, price and lead-time matrices, supplier scorecards, and primary-interview evidence. In keeping with our “trailer” approach, we have withheld exhaustive segmentation tables and vendor revenue breakdowns here to encourage direct access to the source document and interactive datasets.
To review the full methodologies, obtain vendor-level benchmarking and download the data workbook that underpins our USD-denominated market sizing and the 12.71% CAGR forecast for 2026–2032, please visit the PW Consulting report page or contact our industry team for an executive briefing.
For detailed analysis of this topic, please visit the official page: Worldwide High-capacity NFC Chip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com