

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Worldwide 3D Automated Optical Inspection Equipment in PCB Market to Expand at 11.2% CAGR During 2026–2032

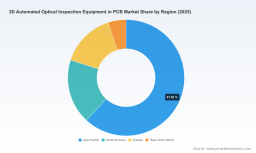
Worldwide 3D Automated Optical Inspection Equipment in PCB Market — Strategic Outlook for 2026 Decision‑Making
PW Consulting’s newest market intelligence brief, “Worldwide 3D Automated Optical Inspection (AOI) Equipment in PCB Market,” synthesizes five years of historical performance and a seven‑year forecast to deliver the decisive context executives need as they make procurement, investment, and M&A choices in 2026. Anchored on a 2025 base year and built from primary vendor interviews, proprietary shipment models and field validation, the study projects the market to grow from USD 1,100.0 Million in 2025 to USD 2,312.74 Million by 2032, implying a compound annual growth rate (CAGR) of 11.2% across the forecast window. The research is designed as a practical playbook: it equips leaders with scenario tools, vendor scorecards and procurement tactics while intentionally withholding granular region- and application-level datapoints from this summary to encourage direct access to the full deliverable.
Worldwide 3D Automated Optical Inspection Equipment in PCB Market
Why 2026 Is a Pivotal Year for AOI Investment
Three convergent forces are reshaping AOI economics and timing decisions for PCB assemblers in 2026:
Worldwide 3D Automated Optical Inspection Equipment in PCB Market
- Technology maturation and regulatory tightening — Standards introduced or updated in 2025 increasingly mandate sub‑micron and tighter height‑measurement tolerances for high‑reliability boards, elevating the bar for inspection performance and certification readiness across supply chains.
- Supply and cost pressure — Component shortages and longer lead times for high‑resolution camera modules have extended procurement cycles; optics and sensor inflation drove a reported average system price increase in 2025, altering total cost of ownership calculus.
- Geopolitical and trade constraints — New export controls and tariff regimes implemented in 2025 have introduced transaction friction for certain cross‑border equipment flows, forcing manufacturers to reconsider sourcing, localization and inventory strategies.
These vectors create a narrow window in 2026 where the right blend of timing, vendor selection and contract structure can materially improve yield, throughput and regulatory compliance while protecting margins from elevated capital costs.
Worldwide 3D Automated Optical Inspection Equipment in PCB Market
What the Report Delivers — Practical, Actionable Content
PW Consulting structures the report to be immediately usable by business leaders, not just descriptive. Key actionable components include:
- Market sizing and methodology: transparent assumptions, sensitivity tests and a replication guide so corporate planners can adapt the base model to their installed base and product mix.
- Seven‑scenario forecasting tool: baseline, upside and downside scenarios that quantify the P&L and CapEx implications of supply disruptions, tariff shocks and accelerated HDI adoption.
- Vendor benchmarking and scorecards: independent assessment across throughput, defect coverage, sensor modularity, analytics maturity and service footprint to support short‑listing and negotiation.
- Procurement and CapEx playbook: timing guidelines for purchase vs. lease, recommended contract clauses to mitigate long lead times, and a decision matrix for retrofit vs. greenfield inspection lines.
- ROI and TCO calculators: tailored templates for build‑versus‑buy, cycle‑time improvements, false‑call reduction and first‑pass yield uplift, enabling finance teams to fast‑track approvals.
- Compliance and certification roadmap: line‑level actions to achieve new standard thresholds and audit readiness across production sites.
- M&A and partnership screen: a prioritized list of strategic attributes to identify acquisitive or partnerable targets and integration playbooks for software and data assets.
Note: the report contains granular regional and end‑use splits, along with per‑technology market shares and unit pricing curves. Those detailed tables and the underlying datasets are reserved for the full report package.
Competitive Landscape — How Leading Vendors Are Shaping 2026 Strategies
The AOI vendor ecosystem remains moderately concentrated, with the top three suppliers commanding a meaningful share of market revenue and the top five accounting for over two‑thirds of measured market sales. That concentration drives faster dissemination of technology paradigms but also intensifies competition around service, analytics and platform extensibility.
- Koh Young Technology (Seoul, South Korea) : A recognized leader in high‑speed true‑3D imaging and AI‑augmented defect detection. Their recent launch of the Zenith Alpha C2+ at productronica in October 2025 underscores continued investment in edge AI and throughput enhancements that target high‑mix SMT lines.
- CyberOptics Corporation (Minneapolis, MN, USA) : Known for robust multi‑reflection suppression and high accuracy in complex packages. The SQ3000+ platform introduced in mid‑2025 extends capability to finer placement classes and 01005 components — a clear signal to OEMs producing miniaturized consumer and medical electronics.
- Viscom AG (Hannover, Germany) : Positioned to serve high‑volume and HDI production with a focus on resolution and process integration. Demonstrations at trade shows in 2025 emphasized incremental resolution gains that improve defect detection on dense interconnect boards.
- Test Research, Inc. (TRI) (Taipei, Taiwan) : Builds on AI‑driven analysis for paste and placement verification; its systems are commonly integrated into feedback loops within SMT lines for closed‑loop correction.
- SAKI Corporation (Tokyo, Japan) : Differentiates via sensor mechanics and compliance focus; recent certification milestones reflect a strategy to win in high‑reliability segments with tight tolerances.
- Mirtec Corporation (Oxford, CT, USA) and Nordson Test & Inspection (Carlsbad, CA, USA) : Both emphasize imaging resolution and hybrid inspection capabilities (AOI + AXI), addressing customers who need consolidated inspection footprints for mixed production runs.
For buyers, vendor selection is increasingly less about headline accuracy claims and more about integration capabilities, data fidelity across the production line, global service coverage and the ability to support compliance updates — attributes that the PW Consulting vendor scorecard quantifies.
Operational Risks and Procurement Considerations
- Supply chain: High‑resolution 3D camera modules faced average lead times of 16–20 weeks in late 2025. This compels planners to adopt long‑lead procurement windows or secure options in multi‑vendor supply cushions.
- Regulation and standards: 2025 updates to industry standards introduced tighter height‑measurement accuracy requirements for critical applications. Inspection systems must be validated for these thresholds as part of acceptance testing.
- Trade and tariffs: Export controls on advanced imaging sensors and new import tariffs in certain geographies altered landed costs and delivery timelines in 2025; companies should model “tariff shock” scenarios within CapEx plans.
- Price dynamics: Reported optics inflation contributed to an average market price increase in 2025, shifting many procurement conversations from sticker price to total lifetime cost, service agreements and upgrade routes.
Strategic Recommendations for 2026 Decision‑Makers
Actions we advise executives to prioritize this year:
- Segment investments by risk and revenue impact: accelerate AOI upgrades on boards that attach the highest warranty and field‑failure risk; defer low‑risk lines where manual inspection remains cost‑effective.
- Negotiate modularity: insist on sensor modularity and software licensing models that permit phased upgrades to manage cashflow and navigate potential export restrictions.
- Lock long‑lead components early: secure critical optics and spare parts via forward‑buy options or vendor consignment to avoid production interruptions.
- Embed inspection data into the digital thread: integrate AOI outputs with MES and SPC systems to create closed‑loop process optimisation, which often delivers faster ROI than hardware upgrades alone.
- Prepare for compliance audits: map product families to the updated measurement standards and run validation protocols during acceptance to avoid expensive retrofits.
- Evaluate service and localization: prioritize vendors with service nodes and spare inventories close to your production sites to reduce downtime risk in constrained markets.
- Leverage the market window for strategic M&A: given the market’s concentration, selectively acquiring sensor, software or analytics capabilities can accelerate differentiation while expanding installed base economics.
How to Use This Report in Your 2026 Planning Cycle
PW Consulting positions the report as both a strategic primer and an operational toolkit for executives, procurement leads and manufacturing engineers. Recommended next steps for organizations that purchase the report:
- Executive briefing: a 90‑minute, PW‑led session to translate forecast scenarios into board‑level decisions on CapEx and risk posture.
- Procurement workshop: use our vendor scorecard and negotiation checklist in vendor RFPs to compress evaluation timelines and reduce negotiation leakage.
- Operational pilot: deploy the ROI calculator and the compliance roadmap to a representative line to quantify first‑year uplift and payback timing.
- M&A screening: apply the strategic attributes checklist to identify acquisition targets or partnership candidates that close capability gaps.
The full report contains the complete datasets (regional and end‑use splits, per‑technology market shares, unit pricing curves, and a detailed vendor benchmarking matrix) that underpin the guidance above. These granular tables and downloadable models are intentionally exclusive to the full delivery to preserve the rigor and reproducibility of our analysis.
To request the full report, schedule an executive briefing, or license the dataset for integration into your CapEx planning systems, visit PW Consulting’s research portal or contact our sales team. PW Consulting’s Worldwide 3D AOI Market brief gives you the scenario frameworks, vendor intelligence and procurement playbooks you need to convert 2026 uncertainty into strategic advantage.
For detailed analysis of this topic, please visit the official page: Worldwide 3D Automated Optical Inspection Equipment in PCB Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com