

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Forecasts Worldwide Pt Paste for Gas Sensor Market to Reach USD 170.38 Million by 2032
By pmarketresearch, 2026-07-15
Worldwide Pt Paste for Gas Sensor Market: Strategic Imperatives for 2026 — PW Consulting Insights
PW Consulting’s latest market intelligence release on the Worldwide Pt Paste for Gas Sensor Market is a targeted briefing for executives who must translate materials risk, supplier strategy, and product architecture into defensible 2026 decisions. This article previews the report’s strategic value: it highlights the structural drivers, supplier dynamics, and pragmatic playbooks that matter to OEMs, Tier suppliers and investors — while protecting the detailed segmentation and proprietary datasets that compel a full download.
Worldwide Pt Paste for Gas Sensor Market
Market trajectory at a glance
Platinum paste used in gas sensors has moved from a niche specialty into a critical materials category with discernible commercial scale. Our research shows the market expanded from USD 74.5 Million in 2020 to USD 110.0 Million in the 2025 base year. Under the forecast framework used in the report, the market grows through 2032 at a 6.45% compound annual growth rate (forecast period 2026–2032), reaching a projected USD 170.38 Million by 2032. This steady expansion reflects both unit growth in sensor deployment and rising per-unit materials value driven by PGM feedstock dynamics and advanced paste formulations.
Worldwide Pt Paste for Gas Sensor Market
Why platinum paste remains a strategic lever for sensor competitiveness
- Functional indispensability: Platinum-based pastes combine catalytic activity and electrical conduction in demanding high-temperature architectures (e.g., oxygen sensors, NOx sensing elements and certain heater designs). Many gas-sensor architectures still rely on PGM characteristics that are difficult to replace without performance trade-offs.
- Design-variant trade-offs: Manufacturers choose between high-temperature co-fired, low-temperature co-fired and thick-film conductor chemistries depending on thermal budgets, substrate compatibility, and process economics. These choices cascade into sourcing, quality control, and qualification timelines that directly affect time-to-market.
- Regulatory and reliability constraints: RoHS2-compliant, lead-free formulations and traceability requirements force sensor OEMs to align materials selection with long-term regulatory compliance and after-market liability management.
Supply-side stressors: price volatility, availability and strategic sourcing
The upstream PGM landscape has introduced a new layer of strategic uncertainty. Industry inputs indicate a multi-year platinum supply shortfall culminating in 2025, when primary supply registered a decline and above-ground stocks tightened. Platinum price volatility intensified in 2025, with market reports documenting a very sharp year-on-year increase that materially affects paste production economics. For procurement and product teams, this destroys the utility of simple unit-cost assumptions and elevates the value of hedging, recycling and supplier collaboration.
Worldwide Pt Paste for Gas Sensor Market
Practical implication: procurement teams cannot treat Pt paste as a commodity buy. The materials premium is driven by catalytic-grade requirements (surface area, particle fineness, and metallurgical form), not by bulk bullion metrics, making supply agreements, technical service and continuity clauses as influential on landed cost as raw metal pricing.
Competitive landscape: capabilities that matter in 2026
The supplier field is multi-dimensional: global PGM specialists, specialty-chemicals formulators, and niche paste manufacturers each bring differentiated value.
- TANAKA Precious Metals (Japan) — Specialist formulations for gas sensor electrodes and heaters, with an integrated powder-to-paste manufacturing model and high-temperature firing capability. Their product range indicates deep application-level engineering and strong quality controls relevant for automotive and industrial sensor OEMs.
- Heraeus Electronics (Germany) — Focus on thick-film conductor pastes and alloyed Pt compositions optimized for electrical performance and process compatibility. Recent updates to product documentation reflect continuous incremental optimization for solderability and chemical resistance in fuel-sensing and temperature-position applications.
- Dycotec Materials (UK) — Offers screen-printable fritted Pt pastes targeted at zirconia oxygen sensors and heater circuits; positions itself on fine-line printability and lower firing-temperature windows that appeal to certain ceramic substrates.
- Ferro Corporation (US) — Active in specialty thick-film formulations with emphasis on process reliability and supply support for sensor OEMs.
- Johnson Matthey (UK) & Umicore (Belgium) — Established PGM houses that contribute upstream material expertise, recycling capability and long-term feedstock strategies that support downstream paste producers.
- MANA Metal (China) & American Elements (US) — Regional and application-focused paste manufacturers supplying electrode pastes for flat oxygen sensors and SOFCs, reflecting a broader supplier base into which OEMs can tier procurement to manage risk and cost.
Recent supplier behavior underlines how technical documentation and raw-material commentary matter to buyers. Notably, Heraeus updated technical data for a solderable AuPtPd conductor in February 2026, and Johnson Matthey’s 2025 market commentary highlighted ongoing PGM deficits — both developments that are directly relevant to material selection and contracting in 2026.
What the PW Consulting report contains — practical outputs for immediate action
Our full market report is a toolkit designed for decision-making rather than an academic compendium. Key actionable deliverables include:
- Detailed market-sizing and historic demand analysis (2020–2025) and a transparent forecasting methodology for 2026–2032, including sensitivity testing to Pt price scenarios.
- Supplier capability maps and a vendor qualification framework that grades suppliers on technical fit (formulation, firing window, printability), commercial reliability (lead times, minimum order quantities), and risk mitigation (recycling, alternate feedstocks).
- Supply-chain stress tests and a cost-model that isolates PGM feedstock as a line-item and projects landed paste cost under multiple mineral and currency paths.
- Design-for-cost and materials-substitution playbooks, including low-PG content strategies, binder chemistry alternatives, and manufacturing yield levers.
- Contracting templates and strategic procurement tools (e.g., hedging thresholds, consignment inventory models, dual-sourcing triggers).
- Regulatory compliance checklist (RoHS2 alignment) and qualification roadmaps for automotive and industrial sensor standards.
- Investor-oriented comparative profiles, M&A screening criteria and partnership candidates for vertical integration or recycling collaborations.
How executives should apply these insights in 2026
- Procurement: Shift from transactional spot-buying to layered procurement: shorter-term physical coverage, medium-term fixed-price commitments with technical support clauses, and long-term evaluation of strategic inventory or recycling partnerships.
- Product management: Prioritize design changes that reduce PGM dependency where possible, while protecting sensing performance through co-development agreements with paste suppliers to trial lower-loading formulations or alternative architectures.
- Operations: Validate manufacturing process windows against multiple paste families (high-temp, low-temp, thick-film) to avoid single-chemistry lock-in; include supplier capability audits in qualification gates.
- Corporate strategy: Evaluate near-term minority investments in recycling capacity or select paste makers to secure feedstock access and to capture margin upside as paste ASPs rise with Pt input costs.
Scenario planning for board-level discussion
Our forecast is the baseline for planning, but the report includes two stress scenarios that are immediately relevant for budgeting and capital allocation in 2026: a downside scenario driven by prolonged PGM supply constraints and delayed sensor adoption in adjacent markets; and an upside scenario where accelerated deployment of advanced emission-control sensors and industrial monitoring pushes adoption. Each scenario quantifies margin impacts, supply risk exposure, and inventory/hardening capital needs — providing the basis for contingency budgeting.
Conclusion — why this brief matters to your 2026 playbook
For companies competing in gas sensing, platinum paste is no longer a line-item in a bill-of-materials: it is a strategic variable affecting product design, supply resilience and margin. PW Consulting’s report synthesizes market trajectory, supplier landscape, and hands-on commercial playbooks that change how procurement, engineering and strategy teams make 2026 decisions. The piece above previews our findings; the full report contains the granular segmentation, supplier scorecards and downloadable cost models that operationalize the insights.
To access the full dataset, supplier matrices and the step-by-step implementation toolkit, visit the PW Consulting report page for the Worldwide Pt Paste for Gas Sensor Market.
For detailed analysis of this topic, please visit the official page: Worldwide Pt Paste for Gas Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Microbial Fuel Cell Market to Grow from USD 17.65 Million in 2025 to USD 37.23 Million by 2032 at an 11.25% CAGR
By pmarketresearch, 2026-07-15
Worldwide Microbial Fuel Cell Market — Strategic Preview for 2026 Decisionmakers
PW Consulting’s latest market study on the Worldwide Microbial Fuel Cell (MFC) market synthesizes five years of historical performance (2020–2025) with a rigorous forecast through 2032. The sector is emerging from pilot-driven experimentation into selective commercialization, and our analysis quantifies that transition: the global MFC market advanced from USD 10.45 Million in 2020 to USD 17.65 Million in 2025, and our base forecasts anticipate a continuation of strong expansion to USD 19.93 Million in 2026 and USD 37.23 Million by 2032, representing a compound annual growth rate (CAGR) of 11.25% over the forecast period. For corporate strategists and investment committees preparing 2026 plans, this report offers actionable intelligence designed to bridge lab-scale promise and commercially viable deployments.
Worldwide Microbial Fuel Cell Market
Why this report matters for 2026 planning
-
Timing and investment sizing: The MFC sector is at an inflection point—capital allocation that favours pilot-to-demonstration projects in 2026 is likely to capture optionality as the technology’s commercial metrics improve.
Worldwide Microbial Fuel Cell Market -
Risk-adjusted roadmaps: Our scenario-based modelling translates technical constraints (e.g., electrode fouling, continuous-flow power density limits) into investment milestones, enabling realistic go/no‑go gates for scaling pilots beyond sub-kilowatt demonstrations.
Worldwide Microbial Fuel Cell Market -
Procurement and supply-chain levers: Given material cost dynamics and supplier concentration in key components, procurement strategies established in 2026 can materially influence unit economics in 2028–2030.
-
Regulatory arbitrage: Changing energy and wastewater directives create a near-term window for early movers to pilot regulatory-compliant systems that capture both environmental service value and energy offsets.
Core industry dynamics that should shape 2026 decisions
Our integrated analysis highlights four dynamics executives must incorporate into near‑term strategy.
-
Material and component economics: Carbon-based electrodes remain a critical cost driver. Market data indicate commercial carbon cloth for MFCs is traded in the range of USD 45–75 per m² (Fuel Cell Store Catalog, Oct 2024). Changes in supply, alternative electrode treatments, or bulk sourcing agreements will directly influence project-level return-on-investment.
-
Performance ceilings and engineering trade-offs: Advanced continuous-flow wastewater MFC prototypes have demonstrated power densities up to 5 W/m³ (U.S. DOE, Bioenergy Technologies Office Report, June 2023). Translating laboratory power densities into stable, fouling‑resistant field operation remains the primary engineering challenge—one that our techno-economic pathways address with realistic degradation and maintenance schedules.
-
Regulatory tailwinds: Policy frameworks that emphasise energy-efficient wastewater treatment (e.g., EU directives on urban wastewater) increase the total addressable market for MFC-enabled secondary or tertiary treatment systems, particularly where regulators reward energy neutrality or recovery (European Commission, Environment Directorate, March 2023).
-
Commercial scale constraints: Despite rapid R&D progress, the industry remains weighted toward pilot-scale installations under 1 kW due to electrode fouling and limited continuous power output. This constraint drives the current commercialization pathway toward modular, decentralized use cases rather than large centralized power generation (Industry Market Data, Sept 2024).
What the report contains — practical, decision-ready modules
-
Market sizing and forecast model: a transparent, auditable model covering 2020–2032 with base, conservative and aggressive scenarios and sensitivity analyses designed to stress-test capex and OPEX assumptions.
-
Techno-economic unit models: bottom-up cost and revenue modules for representative MFC configurations, including lifecycle maintenance and replacement cycles that reflect realistic fouling rates and electrode wear.
-
Commercialization playbooks: step-by-step pathways for scaling from pilot to demonstration to early commercial rollouts—covering procurement templates, vendor selection criteria, and pilot success KPIs.
-
Policy and incentive mapping: jurisdictional analysis of regulatory drivers and co-funding opportunities that can accelerate adoption, with red-team scenarios for evolving standards.
-
Supplier and raw-material scouting: a procurement map highlighting high-impact components and alternative sourcing strategies to mitigate cost and supply risk.
-
Investment matrices and ROI dashboards: comparative analyses to prioritise project types and geographies based on risk-adjusted returns and strategic fit.
Competitive landscape — who matters now
The MFC market exhibits moderate concentration: the top three players account for approximately 38.5% of identifiable market activity, while the top five account for about 52.15%. That structure creates space for both specialist players and integrators to compete: incumbents with strong pilot-track records can defend niches, while new entrants can carve value by targeting specific feedstock or decentralised use cases.
-
Aquacycl Ltd. (Didcot, UK; https://www.aquacycl.com/) — Known for its USABR™ bioelectrochemical reactors, Aquacycl focuses on energy recovery from high-strength industrial wastewater. Their commercial orientation and reactor engineering expertise make them a strategic ally for industrial partners seeking bundled wastewater-energy solutions.
-
Plant-e B.V. (Wageningen, Netherlands; https://plant-e.com/) — Plant-e commercialises plant-MFC systems that harvest electricity from root-zone organic matter via electro-active bacterial communities. Their strength lies in novel application form factors and public-facing demonstration projects that generate visibility and small-scale revenue.
-
Microbenergy S.L. (Valladolid, Spain; https://www.microbenergy.com/en/) — Producer of BEE-BOX® modular MFC units, Microbenergy targets decentralized wastewater treatment combined with localized electricity production. Their modular approach aligns well with municipalities and off-grid facilities pursuing low-footprint solutions.
-
Nijhuis Saur Industries (Doetinchem, Netherlands; https://nijhuissaur.com/) — With BeeVe® membrane-free bioelectrochemical systems, Nijhuis Saur brings integrated wastewater treatment capabilities oriented toward COD removal and energy capture. Their systems appeal to water utilities seeking to augment existing treatment trains with energy-recovery modules.
For strategic buyers and corporate development teams, the profiles above inform three practical plays for 2026:
-
Forge industrial piloting partnerships with firms that supply high-strength streams—those feedstocks produce higher bioelectric yields, improving project economics within pilot horizons.
-
Pursue technology licensing or joint-development agreements with modular-system vendors to accelerate time-to-market while avoiding heavy upfront capex.
-
Invest selectively in electrode and fouling-mitigation R&D—targeted breakthroughs here unlock step-changes in OPEX and system availability, and therefore in overall project IRR.
Practical recommendations for 2026 corporate programs
-
Prioritise demonstration projects that are structured as cost+ performance contracts: this aligns vendor incentives with real-world uptime and energy recovery, and protects buyers from early-life performance variability.
-
Negotiate supplier partnerships with volume-based pricing floors for high-cost components (e.g., carbon cloth), and evaluate alternate electrode substrates to hedge price exposure.
-
Embed regulatory liaison in early-stage pilots to secure design approval and to capture potential incentives tied to energy-neutral wastewater targets.
-
Design pilots with clear metrics for degradability, maintenance cadence, and net energy balance—these are the primary gating criteria for moving from <1 kW pilots to multi-kW demonstrations.
What we are intentionally withholding — why you should consult the full report
In keeping with the “trailer” principle, this briefing surfaces strategic conclusions, market trajectories and practical recommendations that should guide 2026 decisions while intentionally withholding granular segment breakdowns, region-by-region share tables and product-level revenue splits. These detailed datasets are crucial for transaction diligence, procurement tendering and financial modelling, and are available in full on the PW Consulting report portal.
Next steps
For executive teams preparing 2026 budgets and R&D priorities, the immediate actions are clear: (1) allocate seed capital to 6–12 month pilots that include third‑party performance verification, (2) establish procurement frameworks with contingency pricing for high-cost electrode inputs, and (3) open strategic dialogues with the supplier cohort identified in this preview to accelerate co-development opportunities. PW Consulting’s full report provides the granular datasets, downloadable financial models and vendor scorecards required to operationalise these steps.
To access the complete Worldwide Microbial Fuel Cell Market report, including the full segmentation matrices, supplier contracts template, and the auditable forecast model underpinning the 11.25% CAGR projection, visit our official report page or contact PW Consulting’s Market Intelligence desk for a guided briefing and licensing options.
For detailed analysis of this topic, please visit the official page: Worldwide Microbial Fuel Cell Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide 5G NR Antenna Market Poised to Expand at a 15.68% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide 5G NR Antenna Market — Strategic Outlook for 2026 Decision-Makers
Executive Preview
PW Consulting’s latest market study, "Worldwide 5G NR Antenna Market," provides a pragmatic, decision-ready roadmap for executives preparing capital allocation, procurement, and product strategy in 2026. Anchored on a base year of 2025 and covering historical performance (2020–2025) with a forecast window through 2032, the report quantifies the commercial trajectory of 5G NR antenna systems and translates that trajectory into actionable choices for network operators, equipment suppliers, infrastructure investors and systems integrators.
Worldwide 5G NR Antenna Market
Key headline metrics (figures expressed in USD, revenue unit: Million): the market expanded from approximately USD 12.5 billion in 2020 to USD 28.9 billion in 2025, and under our central scenario is projected to reach roughly USD 80.1 billion by 2032. The forecast is driven by a compound annual growth rate (CAGR) of 15.68% over the 2026–2032 period—an environment that will reward early alignment between network plans, spectrum timelines and antenna technology roadmaps.
Worldwide 5G NR Antenna Market
What the Report Delivers — Practical Content for 2026 Planning
-
Comprehensive market sizing and multi-year forecasts, with scenario-based sensitivity analyses that isolate the impact of spectrum availability, regulatory constraints and backhaul economics on antenna demand.
Worldwide 5G NR Antenna Market -
Technology deep dives that translate radio-antenna system choices (e.g., massive MIMO architectures, hybrid active/passive designs, DAS/Distributed Antenna Systems and sub-6 vs mmWave strategies) into network-level throughput, coverage and TCO implications.
-
Deployment economics modules: detailed capex/opex modeling for macro-cell vs small-cell rollouts, fiber and fronthaul cost drivers, and trade-offs for centralized vs distributed radio architectures.
-
Supplier benchmarking and vendor playbooks: qualitative and quantitative scorecards that compare product portfolios, manufacturing footprints, certification timelines and partnership ecosystems (without publishing granular competitive splits in this executive summary).
-
Regulatory risk maps and compliance checklists addressing recent OTA emission limits, spectrum auction calendars and country-level infrastructure constraints—integrated with templates for procurement clauses and test acceptance criteria.
-
Implementation toolkits: rollout prioritization matrices, phased procurement schedules keyed to spectrum availability, and a standalone scenario model that supports “what-if” planning for funding, coverage and capacity targets.
Market Dynamics That Matter in 2026
-
Regulatory and standards shifts: 3GPP Release 19 introduced new over-the-air spatial emission limits in the upper 6 GHz band to protect incumbent satellite services. These requirements materially affect antenna pattern design, test regimes and supplier selection for upper mid-band deployments. Operators must incorporate OTA compliance testing into procurement milestones to avoid deployment delays and retrofit costs.
-
Spectrum timing and policy: legislated auction schedules and expanded spectrum identification in multiple jurisdictions introduce discrete timing risks and opportunities. For organizations deciding 2026 capex levels, spectrum milestones will be a primary determinant of when to accelerate dense urban densification vs. suburban macro enhancements.
-
Infrastructure cost pressure: fiber optic deployment costs and recent raw-material dynamics are elevating the share of backhaul/fronthaul in total deployment costs. Early contracting for high-quality fiber (including bend-insensitive and high-density types) and negotiating supply chain assurances will protect rollout economics.
-
Certification and test readiness: advances in NTN (non-terrestrial networks) and first-to-market PTCRB certifications for NTN RF conformance demonstrate that certification pathways can create first-mover advantages. Firms that align product development and test plans with emerging certification regimes will shorten time-to-revenue.
Competitive Landscape — Who’s Positioned to Win (and Why)
The antenna market is structurally consolidating: the top three suppliers account for nearly half of industry revenue, while the top five capture roughly two-thirds. This concentration creates an environment where scale, product breadth and integration capability matter—particularly for large macro and high-capacity massive MIMO deployments.
-
Ericsson (Stockholm) — Strengths: integrated massive MIMO and hybrid active-passive solutions with strong beamforming capability and macro-site optimization. Strategy: leverage systems-integration leadership to embed antennas in broader RAN deals and to influence OTA measurement standards.
-
Nokia (Espoo) — Strengths: adaptable AirScale mMIMO portfolios and hybrid approaches designed for both macro and small-cell scenarios. Strategy: drive modular architectures that allow operators to scale capacity without full site replacements.
-
Huawei (Shenzhen) — Strengths: ultra-wideband AAUs and energy-efficient massive MIMO suited to dense urban/suburban markets. Strategy: emphasize price-performance and integrated power-efficiency roadmaps where regulatory access permits.
-
Samsung (Suwon) — Strengths: high-throughput massive MIMO radios and active participation in NTN testing partnerships. Strategy: pursue specialized high-throughput deployments and strategic lab collaborations to validate edge use cases.
-
ZTE (Shenzhen) — Strengths: high-channel-count AAUs and hybrid designs for coverage-capacity balance. Strategy: continue to compete on scalability and value for macro rollouts.
-
Passive and DAS specialists — Vendors such as CommScope, Amphenol Antenna Solutions, Comba Telecom, Corning, JMA Wireless, and SOLiD play critical roles in in-building coverage, passive antenna supply and optical-RF integration. Their competitive advantage lies in venue-specific solutions, sustainability credentials and regional manufacturing footprints.
-
Regional and niche players — Companies like Tongyu Communication and PROSE Technologies focus on cost-competitive passive antennas and sustainability-optimized designs—important options for operators pursuing differentiated procurement strategies or localized supply chains.
Implications of Recent Industry Developments
-
Standard updates (3GPP R19) mean antenna vendors must adapt designs and test documentation for OTA spatial emissions. Buyers should require proof points and lab-validated procedures as part of RFP responses.
-
Product launches and certification milestones (for example, new massive MIMO units and the first PTCRB NTN test certifications) signal accelerating commercialization of advanced antenna capabilities. These events create windows for strategic pilots—especially in markets where regulatory regimes enable early mmWave or upper mid-band usage.
-
Raw material and fiber cost volatility suggests procurement teams should model scenarios with higher-than-expected backhaul costs and consider procurement techniques such as indexed long-term contracts or material hedging where feasible.
Five Tactical Recommendations for 2026
-
Adopt a “compliance-first” procurement posture: include OTA emission compliance milestones and certification deliverables in contracts to reduce retrofit risk and avoid deployment holds stemming from new spatial emission limits.
-
Prioritize modular/multi-band antenna platforms that can be field-upgraded through software and swap-in modules—this reduces stranded-capacity risk as operators acquire new spectrum tranches.
-
Harden supply chains for fiber and critical components: secure preferred supplier agreements, stagger payment terms, and build inventory buffers for long-lead items in markets facing acute fiber price pressure.
-
Design pilot programs that validate hybrid architectures and DAS in high-value venues. Use these pilots to refine acceptance criteria, validate vendor integration and collect real-world TCO inputs for a broader rollout.
-
Use the market’s concentration dynamics to negotiate ecosystem benefits: leverage the presence of scale vendors for integration discounts but retain competitive tension by qualifying regional niche suppliers for contingency sourcing and specialized applications.
How to Use This Report in Boardroom Decision-Making
The PW Consulting study is structured to be operationally useful: it maps market growth to specific decision levers (spectrum timelines, certification readiness, backhaul economics), provides vendor scorecards and tender-ready technical checklists, and includes an interactive scenario model to stress-test capital plans under alternative regulatory and cost pathways. For procurement teams, the report provides RFP templates and test acceptance matrices. For strategy teams and investors, it delivers scenario insights and M&A hot spots. For product and engineering leaders, it outlines design trade-offs between energy efficiency, array complexity and OTA emission compliance.
Note that this executive summary highlights strategic implications and headline market sizing. Detailed segment-level splits, regional breakdowns, vendor market shares and deployment-level unit economics are intentionally reserved for the full report and its companion dataset—information that materially influences competitive positioning and project-level investment decisions.
Next Steps
-
Operators and investors: use the scenario model in this report to align 2026 capex with spectrum timelines and to prioritize pilots in high-return corridors.
-
Vendors and suppliers: align product roadmaps with the OTA emission and certification requirements outlined here; use the vendor scorecard framework to benchmark go-to-market strategies.
-
Procurement and integration teams: adopt the RFP and acceptance templates from the study to lock in compliance and supply chain protections before contracts are finalized.
PW Consulting’s Worldwide 5G NR Antenna Market report combines empirical market sizing (base year 2025), forward-looking scenario analysis (2026–2032), and operational toolkits designed to reduce execution risk in the next 18–36 months. For organizations that must decide where—and when—to invest in 5G antenna capacity in 2026, the study supplies both the conviction and the instruments to act. Access to the full dataset and vendor-level benchmarking is available through PW Consulting’s report portal for teams requiring project-level specificity.
For detailed analysis of this topic, please visit the official page: Worldwide 5G NR Antenna Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Global Highly Pure Coconut Shell Activated Carbon Market to Grow at a 9.15% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Highly Pure Coconut Shell Activated Carbon Market: Strategic Imperatives for 2026
As corporates retool supply chains and sharpen product portfolios for a post‑pandemic, regulation‑intense market environment, highly pure coconut shell activated carbon has emerged as a small but strategically critical material across water treatment, air purification, precious metals recovery and high‑tech filtration. PW Consulting’s new market study — using 2025 as the base year and projecting through 2032 — quantifies a clear growth trajectory and, more importantly, translates that trajectory into decision‑grade implications for 2026. The headline: the market, which rose from roughly USD 310.3 million in 2020 to USD 480.9 million in 2025, is forecast to expand to about USD 887.6 million by 2032, growing at a 9.15% CAGR over the 2026–2032 forecast period.
Worldwide Highly Pure Coconut Shell Activated Carbon Market
Why 2026 Is a Pivotal Year
Three dynamics converge to make 2026 a tactical inflection point:
Worldwide Highly Pure Coconut Shell Activated Carbon Market
- Supply constraints and raw material cost volatility that crystallized in 2024–2025 are expected to remain a material factor into 2026.
- Regulatory tightening in water and air quality standards is converting compliance demand into repeatable, higher‑margin sales of high‑purity grades.
- An evolving competitive landscape — a mix of large global producers, regional specialists and value‑added suppliers — means execution on sourcing and product differentiation will determine winners and losers.
What the Numbers Tell Strategic Leaders
Our headline macro figures provide three immediate, actionable readings for executives planning 2026 budgets and strategic moves:
Worldwide Highly Pure Coconut Shell Activated Carbon Market
- Market scale and momentum: The market nearly doubled from 2020 to 2032 in our base model, implying sustained end‑market expansion. This supports selective capacity investment and premiumization strategies for high‑purity product lines.
- Price‑sensitivity vs. structural demand: The historical uptick in average import prices and the rapid pass‑through actions by major producers in 2025 indicate that short‑term price shocks can be absorbed when the end use is regulatory or performance driven (e.g., municipal water, semiconductor manufacturing).
- Concentration matters: The market displays moderate concentration (CR3 ~42% and CR5 ~58%), which means large producers exert pricing leverage but there is ample room for agile regional suppliers and niche specialists to win via service, lead times, or customized grades.
Supply‑Side Realities and Operational Responses
Raw material trajectories have been the dominant near‑term driver. Reduced coconut harvests in major producing countries tightened shell supply in 2024–2025, pushing feedstock prices materially higher and prompting at least one major supplier to implement a substantial price increase in mid‑2025. In response, PW Consulting recommends three immediate operational moves for 2026:
- Lock cost and continuity: negotiate layered supply agreements combining fixed‑price tranches, volume commitments, and indexed smaller lots to balance cost certainty with flexibility.
- De‑risk feedstock via vertical and near‑vertical plays: consider strategic investments upstream (charcoal processing partnerships, outgrower schemes) or long‑term offtake contracts that include quality specifications and sustainability clauses.
- Short‑cycle capacity levers: prioritize debottlenecking and modular production upgrades rather than greenfield green‑site builds; such measures improve unit economics with lower capital and shorter lead times.
Competitive Landscape: Positioning, Risks and Opportunities
The coconut shell activated carbon sector is populated by global heavyweights, regional champions and specialized innovators. Leading producers combine scale, global distribution networks and increasingly, forward integration into regeneration and filtration services. Regional manufacturers in major producing countries preserve cost advantages and proximity to feedstock, while Western suppliers emphasize regulatory compliance, traceability and service. Recent strategic moves underscore these trends: capacity expansions by established producers and industry‑wide price adjustments in response to raw material tightness.
For decision makers assessing partners or acquisition targets in 2026, our report highlights three dimensions to evaluate:
- Feedstock control and traceability — supplier resilience is now a strategic lever, not just an operational concern.
- Product differentiation — investments in low‑ash, high‑hardness, high‑purity grades and in tailored pore structures create defensible value propositions for premium end uses.
- Service integration — carbon regeneration, filtration system bundling and certification (AWWA, EN, ISO) are becoming pathways to stickier customer relationships and margin capture.
Demand Drivers and Commercial Playbooks
Demand remains anchored in traditional water and wastewater treatment, but growth is accelerating in higher value segments — specialty food and beverage processing, pharmaceuticals, precious metal recovery and emerging high‑tech uses such as supercapacitors and semiconductor wet processes. For commercial teams entering 2026, PW Consulting outlines three concrete playbooks:
- Segmented pricing: adopt value‑based pricing where regulatory compliance or product integrity is primary; maintain competitive transactional pricing in commoditized industrial applications.
- Channel optimization: combine direct institutional sales for large treatment projects with distributor partnerships for fragmented municipal and industrial buyers to optimize reach and inventory turn.
- Service‑led differentiation: create bundled offerings (supply + testing + regeneration + replacement schedules) to convert one‑time product sales into recurring revenue streams.
Risk Scenarios and Contingency Planning
Our scenario framework for 2026–2028 models three plausible paths and the corresponding tactical responses:
- Base scenario — steady demand, persistent raw material tightness: prioritize procurement hedges and margin management through selective premiumization.
- Tight‑supply/high‑price scenario — accelerated feedstock shortages and continued price inflation: fast‑track upstream partnerships, reduce exposure to spot markets, and accelerate transition to higher‑value specialty grades.
- Demand‑surge scenario — regulatory acceleration or industrial adoption beyond forecasts: activate modular capacity expansion plans, secure alternative feedstock routes, and evaluate opportunistic M&A to close time‑to‑market gaps.
What Our Report Contains (and What It Deliberately Omits)
PW Consulting’s full report is structured to be immediately operational for procurement, product, M&A and corporate strategy teams. Included are:
- Detailed market model with historicals (2020–2025), 2026–2032 forecasts, sensitivity runs and scenario outputs.
- Supply chain maps and feedstock pricing models that show cost drivers and regional sourcing hotspots.
- Competitive profiles and capability matrices for the leading manufacturers and suppliers, benchmarking capacity, product portfolios, service offerings and strategic moves.
- Commercial playbooks for pricing, channel design and product development, plus a procurement toolkit with contract templates and hedging approaches.
- Regulatory and tariff impact analysis, including stress tests for reshoring and regionalization strategies.
In keeping with our “trailer” approach, the public summary above intentionally refrains from publishing the granular regional and application split tables, mesh‑by‑grade pricing matrices, or the full company financial comparisons — these are proprietary datasets included in the definitive report and our interactive dashboard. For teams evaluating investment, procurement or M&A in 2026, those datasets materially change the financial calculus and are available through our report access channels.
Strategic Recommendations — A 90‑Day Blueprint for 2026
To translate insight into action, PW Consulting recommends the following prioritized actions for the next 90 days:
- Procurement: finalize at least one multi‑year feedstock agreement with price collars and quality clauses; implement inventory optimization to smooth short‑term disruptions.
- Commercial: reprice select product lines to reflect realized cost increases, while testing premium offers in regulated end markets.
- Operations: scope modular capacity upgrades and evaluate contract manufacturing options to preserve capital flexibility.
- Corporate Development: initiate targeted diligence on regional producers with feedstock access and service capabilities that complement your portfolio.
Conclusion — Why This Report Matters for 2026
The coconut shell activated carbon market presents a rich but nuanced set of growth opportunities. The macro view — a market rising from roughly USD 480.9 million in 2025 to nearly USD 887.6 million by 2032 at a 9.15% CAGR — validates strategic involvement. Yet, the immediate competitive and supply‑side frictions exposed in 2024–2025 mean that the value lies in execution: securing feedstock, differentiating product quality, and bundling services. PW Consulting’s study does not merely forecast demand; it equips decision makers with the playbooks, data models and supplier roadmaps needed to convert a favorable market outlook into sustainable competitive advantage in 2026 and beyond.
To obtain the full dataset, company benchmarking tables, price matrices and the interactive forecast model, please access the full report via PW Consulting’s market research portal.
For detailed analysis of this topic, please visit the official page: Worldwide Highly Pure Coconut Shell Activated Carbon Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Multi‑Sensor & Multi‑Directional Security Camera Market Poised to Reach USD 3,911.8 Million by 2032 at a 15.26% CAGR
By pmarketresearch, 2026-07-15
Worldwide Multi-Sensor and Multi-Directional Security Camera Market: Strategic Briefing for 2026 Decisions
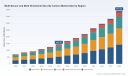
PW Consulting’s new market study on the Worldwide Multi-Sensor and Multi-Directional Security Camera Market (base year 2025; forecast 2026–2032) is designed as a decision-grade briefing for technology buyers, procurement leaders, systems integrators, and corporate strategists preparing capital and operating plans in 2026. The market has moved from a nascent, fragmented investment pattern to a robust growth trajectory — expanding from roughly USD 712 million in 2020 to about USD 1,447 million in 2025, with continued acceleration into the forecast window. Our baseline scenarios project sustained expansion toward an industry size in the low billions by the end of the decade, underpinned by a compound annual growth rate of 15.26% during the forecast horizon. This briefing highlights the practical implications of that growth without disclosing the granular segment tables contained in the full report; consider this a strategic preview that surfaces the actionable insights you need to prioritize 2026 initiatives.
Worldwide Multi-Sensor and Multi Directional Security Camera Market
Why multi-sensor / multi-directional systems matter now
Security investments are increasingly being judged by coverage efficiency, analytics completeness, and lifecycle cost rather than by headcount or per-camera line-item prices alone. Multi-sensor and multi-directional architectures deliver a differentiated value proposition: broader situational awareness from fewer physical enclosures, reduced blind spots in large or complex environments, and better analytics outcomes when combined with edge AI and modern stitching/warping pipelines. Two parallel technology shifts amplify this trend in 2026:
Worldwide Multi-Sensor and Multi Directional Security Camera Market
- Edge compute and AI acceleration (including embedded platforms such as NVIDIA Jetson-class solutions) enable onboard analytics that cut server costs and reduce dependencies on centralized processing.
- Network and power advances (PoE++ and higher-efficiency codecs) make the installation of multi-sensor systems more predictable and less disruptive to existing infrastructure.
At the same time, procurement patterns are evolving: buyers demand interoperability (ONVIF-conformant products), stronger supply-chain provenance due to export control and compliance regimes, and turnkey cloud-management options that simplify operations at scale. The result is an expanding set of deployment archetypes—from smart-city wide-area surveillance to logistics hubs where a few multi-sensor enclosures can replace dozens of single-lens cameras.
Worldwide Multi-Sensor and Multi Directional Security Camera Market
Report coverage and operational value
The full PW Consulting study is built to be operational from day one. It combines market sizing and trend analysis with practical tools that enterprise teams can apply in RFPs, pilots, and technology roadmaps. Key deliverables include:
- Market sizing and scenario forecasts (global totals and modeled upside/downside cases across the 2026–2032 window).
- Technology and deployment playbooks, covering fixed multi-sensor, adjustable multi-directional, and hybrid PTZ/multi-sensor architectures.
- Procurement templates and specification checklists (including NDAA and interoperability clauses, PoE++ electrical profiles, and edge-AI capability baseline requirements).
- Vendor benchmarking and decision matrices that translate product features into procurement risk/benefit scores.
- TCO and ROI models calibrated for common end-user archetypes (e.g., public infrastructure, commercial campuses, transportation hubs, industrial sites) so buyers can move from proof-of-concept to capital approval confidently.
- Regulatory and compliance trackers that map NDAA implications, ONVIF conformance, and export-control risk to sourcing strategies.
We intentionally withhold the detailed tables and segment-level breakout in this preview so that procurement teams have a single destination for the complete, downloadable workbench and data models — the full report contains the granular line-by-line figures that operationalize these bullets.
Competition and product strategies — what stands out
The competitive field in 2026 is populated by well-established OEMs and a growing class of cloud-native entrants. Market concentration is meaningful but not prohibitive: the top three vendors account for roughly two-fifths of industry revenue, while the top five capture a bit more than half — creating space for regional specialists and solution-focused challengers to win via integration and service models.
- Hanwha Vision (Seoul; Americas presence) — Strong in wide-area, AI-enabled multi-sensor systems and recent product launches that embed high-performance onboard acceleration. Their roadmap emphasizes serverless recording and platform integration to simplify large-scale deployments.
- Axis Communications (Lund, Sweden) — Focused on modular multi-directional platforms and high-resolution panoramic models that prioritize seamless 360° coverage for complex sites where visual continuity matters.
- i-PRO (Osaka) — Differentiates on low-profile multi-sensor designs with robust edge AI and advanced auto-tracking suited for challenging lighting and environmental conditions.
- Avigilon / Motorola Solutions (Vancouver) — Combines cloud-enabled management with adjustable multi-sensor offerings and a strong enterprise channel play, emphasizing integrated analytics.
- Pelco, Rhombus, OpenEye, Digital Watchdog, Honeywell, Hikvision, Dahua, Vivotek, Bosch, AV Costar, ACTi — A diverse group spanning legacy global brands, cloud-first startups, and regional specialists. Their value propositions vary from cost-optimized panoramic modules to NDAA-compliant, enterprise-grade platforms and cloud-native analytics stacks.
Recent vendor moves underscore three market forces: product differentiation through embedded AI (e.g., deployments using onboard acceleration platforms), compliance-driven catalog updates (notably NDAA-compliant line refreshes), and continued vendor marketing around cloud-managed, PoE-driven installations. Buyers should assess suppliers not only on camera hardware but on their platform economics, firmware update cadence, and openness to third-party analytics.
Regulatory and supply-chain considerations for 2026
NDAA compliance remains a practical gating factor for many government and large enterprise deployments in the U.S., and export-control regimes continue to influence sourcing strategies for components and finished goods. ONVIF conformance is the default interoperability expectation for networked systems, but true multi-vendor operability still requires end-to-end testing in target operational environments. Mitigation strategies documented in the report include dual-sourcing, localized testing programs, firmware attestation procedures, and contractual remedies tied to continuity of supply.
Six tactical moves for procurement and technology teams
- Prioritize pilots that combine a representative space and peak-event scenarios; measure analytics precision, stitching artifacts, and end-to-end latency rather than raw camera specs.
- Mandate open standards (ONVIF) and explicitly test vendor claims for NDAA compliance and export provenance during the RFP stage.
- Budget for PoE++ planning and verify power budgets at switch and trunk levels early in the design cycle to avoid late-stage electrical upgrades.
- Insist on modularity in analytics: evaluate whether AI can be upgraded in-field and whether vendors support heterogeneous analytics stacks (edge + cloud).
- Model TCO over 5–7 years including firmware/maintenance, analytics subscriptions, and decommissioning costs — use the report’s ROI templates to stress-test scenarios.
- Develop a supplier resilience scorecard that incorporates geographic manufacturing footprints, service-level agreements, and roadmap transparency.
How PW Consulting’s study supports board-level and operational decisions
This research is structured to support both strategic planning and tactical procurement. For boards and C-level custodians, the study provides scenario-based market exposure analysis and enterprise-level risk assessments tied to supplier concentration and regulatory headwinds. For CIOs and security operations leaders, the report supplies procurement language, scoring templates, and deployment checklists that reduce pilot-to-production friction.
Because the decision calculus in 2026 increasingly ties security camera investments to operational outcomes (analytics-driven safety, automated incident detection, and integration with building and traffic management systems), buyers who align procurement with the broader enterprise technology stack will capture the most upside. The full report contains the granular forecasts, segmented revenue tables, vendor scorecards, and downloadable TCO models necessary to operationalize these recommendations.
Next steps
If your 2026 capital planning cycle includes multi-sensor or multi-directional camera investments, PW Consulting’s full report provides the detailed models, vendor intelligence, and procurement-ready artifacts you need to convert strategy into deployed capability. Consider the preview above as a high-level map: for the turn-by-turn guidance, segment-level forecasts, and the vendor comparison matrices that large-scale buyers require, please access the complete report and the companion Excel workbooks available through PW Consulting’s market research portal.
For detailed analysis of this topic, please visit the official page: Worldwide Multi-Sensor and Multi Directional Security Camera Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Halloysite Nanotubes Market to Grow at a 6.52% CAGR Through 2032, New Insights Reveal
By pmarketresearch, 2026-07-15
Worldwide Halloysite Nanotubes Market — Strategic Briefing for 2026 Decision-Makers
Executive summary
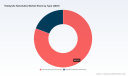
Halloysite nanotubes (HNTs) have migrated from a niche mineral curiosity to a strategic material class in high-value industrial and advanced technology applications. PW Consulting’s new market study—anchored on a 2025 base year and projecting through 2032—finds a clear, investable trajectory: the global HNT market has expanded from under USD 40 million in 2020 to just over USD 52 million in 2025, and PW projects steady growth through 2032 with a compound annual growth rate of 6.52%. By 2032 our scenario modeling foresees the market approaching the low eighties (USD million), driven by new feedstock projects, novel functionalization routes, and emergent end-market integration (notably in energy storage, high-performance composites, and regulated personal-care and medical applications).
Worldwide Halloysite Nanotubes Market
Why this report matters for 2026 strategic decisions
- Timing: 2026 is a pivot year — many pilot projects, capital raises and resource confirmations reported in late 2024–2025 reach execution or investment review in 2026. Our study translates that inflection into pragmatic decision points for procurement, R&D prioritization, and M&A.
- Actionability: The report delivers not only market sizing and forecasts but operational playbooks—supply‑chain stress tests, qualification checklists for HNT grades, and go-to-market frameworks for product teams seeking to incorporate HNTs with predictable cost and regulatory profiles.
- Risk-adjusted insight: With market concentration materially above a basic commodity market (our CR3 and CR5 indicators underline a mid‑to‑high consolidation), companies must weigh supplier concentration, co‑processing risks, and the potential for feedstock-linked vertical integration when making 2026 capital allocation decisions.
Market trajectory & macro view
Our base-year analysis (2025) captures an industry that has recovered and consolidated following early‑decade volatility. From roughly USD 38.5 million in 2020 to USD 52.2 million in 2025, the market demonstrates both resilience and commercial maturation. Forecasting from 2026 through 2032—our dedicated projection window—PW applies a 6.52% CAGR to capture the combined effect of expanding downstream adoption and incremental supply unlocks. By modeling alternate adoption curves for batteries, advanced coatings, and pharmaceutical carriers, we quantify how modest shifts in each segment’s uptake materially alter capital planning and inventory management needs for manufacturers and integrators in 2026.
Worldwide Halloysite Nanotubes Market
Key growth vectors and what to watch in 2026
- Advanced energy materials: Halloysite-derived silicon and other functionalized feedstocks are being pursued aggressively as a low‑cost precursor for next‑gen anodes. New capacity and commercial pilots in 2025–2026 create optionality for OEMs seeking domesticized battery material supply chains.
- High‑performance composites and coatings: HNTs’ tubular morphology and ability to host active molecules continue to unlock improvements in barrier, mechanical reinforcement and controlled-release functionality—properties attractive to polymer and coatings formulators aiming to differentiate on performance.
- Regulated personal-care and medical applications: The route from lab to market is longer here, but demand for biocompatible, naturally derived carrier systems is rising. Regulatory compatibility and documentation will determine which suppliers scale first.
- Supply-side transformation: Surface deposits and new mining methodologies reported in 2024–2026 can materially expand monthly production capability, but environmental permitting and processing quality controls remain gating factors.
Supply dynamics and raw-material economics
Two dynamics shape upstream strategy in 2026: rarity and grade variability. High‑purity halloysite commands a material premium over standard clays because of its nanotubular structure and low impurity profile, which directly affects downstream processing costs and qualification timelines. Recent corporate disclosures suggest that surface-minable deposits and lower‑carbon excavation methods are creating potential volume uplifts—however, developers must still navigate permitting, restoration obligations and water-management requirements. For procurement teams, the imperative in 2026 is clear: structure contracts that combine quality guarantees and staged volume commitments to manage both price and qualification risk.
Worldwide Halloysite Nanotubes Market
Competitive landscape — who matters and why
The HNT ecosystem remains concentrated around a handful of vertically integrated and specialty suppliers. PW’s competitive review focuses on companies whose operational footprints, resource quality and technology strategies are most consequential for buyers and investors in 2026.
- Imerys S.A. (Paris, France) — an incumbent operator leveraging a long-standing, high-purity deposit overseas that remains attractive to fine-ceramics and other high-quality applications. Imerys’ 2025 financial updates indicate stable performance and ongoing cost optimization, which will affect pricing and availability for premium applications.
- Ionic Mineral Technologies (Provo, Utah, USA) — notable for large, high-purity U.S. deposits and an explicit strategy to turn HNT feedstock into proprietary battery materials. Ionic’s 2025 Series B financing and subsequent resource confirmations (late‑2025) materially change project viability and make it a pivotal company for western supply security and battery-material roadmaps.
- American Elements (Los Angeles, USA) — positions itself as a rapid-source supplier across research and industrial grades, with deep cataloguing of high‑purity product specs. Their go-to-market model supports rapid prototyping and scale-up needs for customers that require tight compositional controls.
- Stanford Advanced Materials (SAM) (Lake Forest, USA) — serves the scientific and industrial R&D communities with defined morphological specifications and reproducible batches, supporting downstream qualification efforts in coatings, electronics and composites.
Beyond these established names, project developers and junior miners advancing kaolin‑halloysite plays are very much part of the 2026 competitive map; successful early-stage financing and de‑risking steps in 2025–2026 will determine whether additional low‑cost supply appears in the near term.
Regulation, sustainability and qualification hurdles
HNT mining and downstream use intersects with environmental regulation and product safety frameworks. Operators must demonstrate responsible extraction, land restoration and water stewardship to pass permitting thresholds. Meanwhile, applications in pharmaceuticals, cosmetics and food-contact materials require compliance with chemical safety and biocompatibility standards—delaying some commercial ramps but increasing entry barriers in return. For sustainability-oriented buyers, traceability and low‑carbon processing routes will factor into supplier selection in 2026; PW’s scenario analysis quantifies the price and time premiums associated with these attributes.
What the PW Consulting report delivers (practical contents)
Our study balances strategic context with executable intelligence. Highlights include:
- Market sizing and forecast models (2020–2032) with scenario toggles for regulatory timelines, battery adoption curves and feedstock unlocks.
- Supply‑chain maps and supplier capability matrices that enable procurement teams to run rapid shortlists and qualification pathways.
- Product integration playbooks—technical checklists, pilot‑to‑production timelines, and typical qualification failure modes drawn from lab and field data.
- Commercial benchmarking and a negotiated-sourcing playbook for buyers, including term‑sheet templates and risk allocation clauses for staged supply agreements.
- Competitive landscaping and M&A radar with profiles, recent developments and strategic fit matrices for corporates and investors.
- Regulatory and ESG compliance matrices tailored by application class, plus advocacy and permitting best practices for resource developers.
Strategic implications and recommended 2026 actions
- For manufacturers and OEMs: secure dual-source qualification paths now. Prioritize suppliers that can demonstrate both material grade consistency and documented environmental compliance.
- For R&D and product teams: adopt a staged validation approach—proof‑of‑concept, pilot batches, and an industrial validation phase with defined KPI gates to avoid costly scale-up delays.
- For procurement and supply‑chain executives: negotiate flexible offtake agreements linking take-or-pay floors to clearly defined acceptance criteria (particle morphology, impurity thresholds). Embed price‑reopener clauses tied to documented feedstock quality and throughput metrics.
- For investors and M&A teams: monitor project developers and vertically integrated players delivering both feedstock and value‑added processing. Capital deployed in 2026 should favor entities with clear permitting progress and demonstrable processing reproducibility.
Concluding perspective — the 2026 inflection
Halloysite nanotubes are no longer an exotic sideline; they are a strategic raw material whose supply, quality and traceability will dictate who wins in several advanced-material frontiers. The market’s steady growth and the concentration profile mean that decisive action in 2026—whether to secure supply, accelerate product trials, or position for strategic investments—will have outsized consequences. PW Consulting’s report equips leaders with the market maps, operational blueprints and risk frameworks needed to convert that action into tangible outcomes.
Next steps
To access the full dataset, supplier scorecards, and the downloadable scenario models that underlie our conclusions, visit the PW Consulting report page and register for the executive briefing. The full report preserves detailed segmentation intelligence and proprietary unit‑cost models that are intentionally withheld from public summaries to protect analyst work product and to enable clients to act on uniquely actionable insights.
For detailed analysis of this topic, please visit the official page: Worldwide Halloysite Nanotubes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Paper Napkins and Serviettes Market to Reach USD 5,000 Million by 2025 as Foodservice Fuels Demand
By pmarketresearch, 2026-07-15
Worldwide Paper Napkins and Serviettes Market — Strategic Outlook for 2026 Decision‑Makers
Executive summary
PW Consulting’s new market study on the Worldwide Paper Napkins and Serviettes Market synthesizes five years of historic performance with a seven‑year forecast to deliver a decision‑grade view for 2026 and beyond. The global market reached approximately USD 5,000 million in 2025 and, driven by steady end‑market demand and structural shifts in sourcing and sustainability, is projected to expand at a compound annual growth rate (CAGR) of around 4.31% through the 2026–2032 forecast window — reaching roughly USD 6.72 billion by 2032 under the base forecast. This release is intended as a strategic “trailer”: it demonstrates the depth and applicability of our analysis while reserving the proprietary, granular segment and regional datapoints for the full report and interactive dashboards available from PW Consulting.
Worldwide Paper Napkins and Serviettes Market
Why this report matters for 2026 planning
- Actionable foresight: The market is neither hyper‑volatile nor static — it is evolving along predictable but industry‑altering vectors (sustainability, cost inflation in fiber inputs, and consumption shifts in away‑from‑home channels). Procurement leaders, manufacturers, private‑equity investors, and foodservice operators require clarity on where to deploy capital and where to defend margins in 2026.
- Timing: 2026 sits at the inflection between recovery investments made in 2023–2025 (capacity expansions, product reformulations) and the operational realities of today’s input cost environment. Companies that align commercial priorities with procurement levers now will capture disproportionate share of margin expansion in the next three years.
- Decision utility: PW Consulting’s study is designed to support board‑level portfolio choices, plant‑level capacity investments, product roadmap prioritization, and channel playbook adjustments — all calibrated to the market trajectory we model through 2032.
Market trajectory and the macro picture
The napkin and serviette market has shown consistent growth from 2020 through 2025, with the market expanding from a multi‑billion base in 2020 to roughly USD 5.0 billion in 2025. Our baseline forecast — built from bottom‑up supply/demand modelling, pricing scenarios, and channel dynamics — yields a mid‑case CAGR of 4.31% for 2026–2032. That trajectory is the result of interacting forces: continued demand in foodservice and retail, product premiumization in selected channels, and regulatory and commercial pressure toward higher recycled content and certified compostable options.
Worldwide Paper Napkins and Serviettes Market
Supply‑side pressures remain a critical lever. Recent industry indicators point to elevated pulp index readings and upward movement in sanitary tissue producer prices, which feed directly into raw material cost pass‑through and supplier margin dynamics. These inputs, combined with regional regulatory moves on compostability and recycled content requirements, create a two‑track environment: near‑term cost management is essential, while medium‑term product and process innovation will determine competitive positioning.
Worldwide Paper Napkins and Serviettes Market
Key market dynamics shaping 2026 strategies
- Sustainability as a business imperative: Commercial buyers are increasingly prioritizing products with higher recycled fiber content and recognised compostability certifications. This is reshaping product specifications in foodservice and healthcare procurement tenders and influencing retail assortments.
- Input cost volatility: Pulp and sanitary tissue price indices have trended upward in early 2026, creating margin pressures for vertically integrated manufacturers and third‑party converters alike. Strategic procurement and hedging, as well as mix optimisation, become decisive in 2026 budgeting cycles.
- Channel evolution: Away‑from‑home consumption patterns are recalibrating after pandemic‑era shocks; automation and consumption‑reduction dispenser systems are gaining traction in institutional and quick‑service channels.
- Consolidation and capacity shifts: Select global players continue to invest in regional capacity expansions and differentiated product lines, while nimble regional manufacturers pursue specialty niches (certified compostable, printed/BRANDED hospitality serviettes).
Segmentation (what the report covers — without revealing proprietary splits)
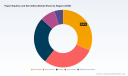
Our study dissects the market across three core dimensions: By Type (e.g., single‑ply vs. multi‑ply formats and premium tissue constructions), By Application (household retail versus foodservice and institutional channels), and By Region (major global regions and cross‑border trade flows). The full report includes volumetric and value estimates, trend lines, and sensitivity scenarios for each segment. In this communication we intentionally withhold the fine‑grained regional and application value shares to preserve the proprietary modelling that underpins our strategic recommendations; these are available in the complete report and interactive model.
Competitive landscape: major players and strategic moves
The market displays a moderate level of concentration among global incumbents with meaningful room for regional specialists and product innovators. Our competitive analysis profiles leading multinational tissue companies, regional converters, and specialist suppliers. Selected company profiles and recent developments include:
- Kimberly‑Clark Corporation (Irving, Texas): A dominant consumer and away‑from‑home brand owner, actively increasing recycled content in flagship napkin products and transitioning packaging to recycled materials.
- Procter & Gamble Co. (Cincinnati, Ohio): Leveraging strong retail positioning and product performance messaging (absorbency, multi‑use) to defend premium segments, particularly in North America.
- Georgia‑Pacific LLC (Atlanta, Georgia): Focused on commercial and institutional channels, expanding offerings that include compostable options to meet evolving procurement standards.
- Essity AB (Stockholm): Leading the professional hygiene channel with dispenser systems designed to reduce consumption; 2026 launches demonstrate material consumption reduction potential in foodservice.
- Sofidel Group (Porcari): Executing North American capacity expansion strategies to support both retail and away‑from‑home demand.
- Cascades Inc., WEPA, Metsa Group, APP, Hengan, La Pajarita, Mank: Each of these players occupies strategic positions — from certified compostable product lines to custom‑printed hospitality serviettes and regional manufacturing footprints. Their differentiated plays reflect the value opportunities in specialty channels and sustainability certification.
Recent corroborated industry moves that materially influence 2026 decision‑making include Essity’s rollout of next‑generation dispenser systems (early 2026), Sofidel’s new Ohio facility (January 2026), Kimberly‑Clark’s reformulated Scott brand with higher recycled content (late 2025), and Cascades’ launch of BPI‑certified compostable napkins (September 2025). Together, these events demonstrate an industry actively re‑tooling product portfolios and supply chains for sustainability and efficiency — not incremental changes but structural shifts that will influence contract terms, capital allocation, and product positioning in 2026.
Practical implications by stakeholder
- Manufacturers: Prioritise investments that reduce fiber intensity per use (dispensers, embossing efficiency), expand certified recycled and compostable SKUs, and tighten upstream pulp procurement strategies. Scenario planning is required to stress‑test margin outcomes under varying pulp price trajectories.
- Distributors & Broadliners: Re‑evaluate assortment strategies to include sustainability credentials as a trade differentiator and develop flexible stocking models to manage lead times from expanded regional capacity.
- Foodservice operators & Institutions: Consider capex in portion‑control dispensers and enforce procurement specifications that reward lifecycle performance (end‑of‑use compostability) to align with regulatory and customer sustainability expectations.
- Private equity & strategic investors: Look for buyouts or minority investments in regional players with clear certification credentials or in technology providers that reduce consumption per cover; valuation premia are likely for assets that demonstrably lower total cost of ownership.
Report contents — what you’ll get in the full deliverable
PW Consulting’s full report is structured to be immediately operational for commercial and procurement teams. Deliverables include:
- Detailed historical (2020–2025) and forecast (2026–2032) market model in USD millions with scenario toggles for price, volume, and substitution effects;
- Segment‑level analysis (by type, application, and region) with volumetric and value tables and sensitivity testing;
- Competitive intelligence dossiers on the leading global and regional players, including product portfolios, capacity footprints, and recent strategic moves;
- Procurement playbook and supplier negotiation levers tied to input cost scenarios;
- Regulatory and certification tracker (EU/North America hygiene standards, composting programmes, and labeling implications);
- M&A and partnership heat map with candidate targets and valuation benchmarks (for investors and corporate development teams).
How to use this analysis in 2026 planning cycles
Begin with three practical steps:
- Integrate PW Consulting’s mid‑case market model into your 2026 budgeting to stress‑test P&L under alternative pulp price paths and adoption rates for sustainable SKUs.
- Prioritise near‑term procurement and product moves that deliver both margin protection and sustainability credentials — for many companies this means a hybrid approach combining modest capex (dispensers, packaging changes) and SKU rationalisation.
- Use competitive benchmarking from our dossiers to inform go‑to‑market and capacity decisions: match your product investments to channels where willingness to pay for sustainability or performance premiums is highest.
Next steps & access
This overview surfaces the strategic conclusions and practical directions that PW Consulting’s full report unpacks in granular detail. For teams preparing budgets, RFPs, or M&A pipelines in 2026, the full dataset and scenario model are essential. To review the complete analysis, access interactive tables, or commission tailored advisory work (pricing playbooks, procurement tender support, or acquisition screening), please visit the PW Consulting report page or contact our industry practice. The full intelligence package contains the proprietary segment and regional breakdowns, downloadable models, and consulting options that are intentionally withheld here to preserve the integrity and commercial value of the analytic work.
PW Consulting — providing the market clarity you need to make confident, timely strategic choices in the Worldwide Paper Napkins and Serviettes market.
For detailed analysis of this topic, please visit the official page: Worldwide Paper Napkins and Serviettes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide PDMAT Market to Reach USD 638.7 Million by 2032 at 7.5% CAGR — Asia Pacific Leads with USD 225M (2025)
By pmarketresearch, 2026-07-15
Worldwide PDMAT Market — Strategic Intelligence Briefing for 2026 Decision‑Makers
PW Consulting today releases a strategic briefing based on our forthcoming Worldwide PDMAT (Penta(dimethylamino)tantalum) Market report. Built on a five‑year historical foundation (2020–2025) and forward projections through 2032, this analysis frames the commercial dynamics that will shape supplier choices, capital allocation and technology roadmaps as semiconductor manufacturers accelerate node transitions and advanced packaging programs in 2026.
Worldwide PDMAT Market
Market snapshot: what the headline numbers mean for strategy
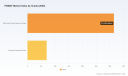
Our modeling uses 2025 as the base year and projects the market through a 2026–2032 forecast window. The PDMAT market, measured in USD (revenue unit: Million), has shown steady expansion in the historical period and is expected to continue on a growth trajectory with a compound annual growth rate (CAGR) of 7.5% over the forecast horizon. Practically speaking, this translates into a materially larger addressable spend for precursors used in ALD/CVD TaN barrier films and related applications by the late 2020s, shifting supplier economics and sourcing strategies for both OEMs and chemical suppliers.
Worldwide PDMAT Market
For executives preparing capital and procurement plans in 2026, the key takeaway is structural: PDMAT is a niche but high-value precursor whose market dynamics are governed more by technology roadmaps, purity and supply reliability than by raw volume alone. The premium attached to ultra‑high purity material and the specialized logistics for air‑ and moisture‑sensitive organometallics mean that strategic sourcing decisions will have outsized impact on fab yield and time‑to‑volume for customers moving to sub‑22nm and advanced Cu interconnect schemes.
Worldwide PDMAT Market
What the report delivers — practical, actionable intelligence (without spoiling the granular datasets)
- Market sizing and trajectory: validated historical series and a consensus‑calibrated forecast (2026–2032) that quantifies the commercial runway for PDMAT in USD millions and outlines sensitivity to node adoption curves and alternative precursor substitution.
- Supply‑side capability mapping: an operational review of high‑purity production methods, capacity constraints, and purification bottlenecks that determine who can reliably support high‑volume manufacturing (HVM) at scale.
- Technology and application analysis: detailed discussion of ALD vs CVD use cases, materials interoperability (TaN barrier integration), and the implications for film performance as device geometries shrink.
- Risk and compliance matrix: handling, packaging, and transport requirements for air‑ and moisture‑sensitive PDMAT, plus regulatory considerations that affect cross‑border shipments and qualification cycles.
- Go‑to‑market playbooks: supplier segmentation (research‑grade vs HVM‑ready), ideal partnership models, and M&A/outsourcing scenarios tailored to chemical suppliers, fabless houses and IDM procurement teams.
We intentionally preserve the granular segmentation tables and regional/application breakdowns for the full report. This “trailer” provides depth to build immediate confidence, while the comprehensive datasets, supplier scorecards and scenario models are available in the downloadable report package for teams ready to operationalize procurement or investment moves.
Competition landscape — who matters and why
The PDMAT supplier universe combines global life‑science/chemicals incumbents, specialized organometallic manufacturers and regional players that have optimized for local semiconductor ecosystems. Market concentration metrics underscore a relatively concentrated market: the top three suppliers control a majority share while the top five consolidate an even larger portion of available supply. That structure creates differentiated supplier power — incumbents with global reach can offer multi‑site qualification and logistics; regional producers often compete on responsiveness, pricing flexibility and proximity to leading fabs.
- Merck KGaA (EMD Group) — Darmstadt, Germany: A global incumbent known for supplying ultra‑high purity PDMAT with established distribution across major semiconductor regions. Strengths include validated quality systems for HVM deployment and multi‑region support that shortens qualification cycles for multinational fabs.
- Ereztech — United States: A nimble supplier that serves both small‑volume research requirements and more substantial batch orders, with custom packaging options (glass ampules, metal bubblers) that reflect a practical understanding of ALD/CVD system realities.
- Strem Chemicals (Ascensus Specialties) — Newburyport, MA, United States: Focused on research‑grade offerings, Strem provides high‑purity products suitable for R&D and pre‑qualification phases; their role is critical in early‑stage process development.
- Nanmat Technology — Taiwan: One of the larger regional CVD/ALD precursor manufacturers, positioned to supply Taiwan’s dense semiconductor ecosystem. Capability to scale for foundry customers is a strategic asset.
- TOPCO Scientific & PentaPro Materials (Taiwan): Regional specialists offering organometallic products tailored for local customers; they are attractive to OEMs seeking supply-chain diversity in Asia.
- Argosun & Sinocompound (China): Chinese suppliers that provide high‑purity grades and can be competitive on lead times for customers in mainland Asia; they are increasingly relevant as domestic fabs expand.
- DOCK Chemicals — Germany: A European source for ultra‑high purity precursors with specialization in manufacturing processes that target extremely low impurity thresholds.
From a strategic standpoint, buyers should assess suppliers against three clustered capabilities: (1) demonstrable ultra‑high purity production and low impurity metrics, (2) packaging/logistics expertise for moisture/air sensitive organometallics, and (3) multi‑site qualification footprints or partnerships that de‑risk supply interruptions. Where the market is concentrated, strategic dual‑sourcing and qualification of regional alternatives become essential hedges.
Dynamics shaping the market (technology, supply chain and regulation)
PDMAT’s chemistry—and the manufacturing ecosystem around it—creates inherent supply‑side barriers. Typical synthesis routes use metathesis of tantalum pentachloride with dimethylamido reagents followed by multi‑stage purification to remove chlorides and oxygen; HVM‑grade materials demand extremely low impurity ceilings, driving specialized capital and process know‑how. These purification steps and the need to maintain an inert environment across packaging and delivery elevate cost and extend qualification lead times relative to more commoditized precursors.
Operational realities matter. PDMAT is highly air‑ and moisture‑sensitive and is typically handled in inert atmospheres and supplied in specialized containers (glass ampules, metal bubblers, etc.) to preserve chemical integrity. These constraints affect logistics, on‑site handling procedures and qualification cycles for fabs integrating new precursor suppliers.
Regulatory and safety classifications confine many PDMAT offerings to R&D or industrial use profiles rather than broader commercial categories, with implications for cross‑border transport documentation and customs handling. Producers pursuing HVM markets must therefore invest not only in purity but also in compliant packaging, specialized transport relationships and the documentation infrastructure necessary for multi‑jurisdiction supply.
Strategic implications and recommended actions for 2026 planning
- Prioritize supplier qualification now if your 2026 roadmaps depend on sub‑22nm barrier performance. Qualification windows are long; securing parallel supply options reduces single‑point failure risk.
- Score suppliers on a combined metric of purity performance, packaged logistics competence, and multi‑site redundancy rather than price-only criteria. The premium for reliability can translate directly to fewer yield losses and faster ramp.
- Consider strategic investments or partnerships with regional manufacturers to shorten lead times for advanced packaging and to insulate supply chains amid geopolitical friction.
- For chemical producers and investors: target the purification and packaging nodes of the value chain. They are high‑barrier, high‑value segments where premium pricing and durable margin profiles are achievable.
- Operational readiness: ensure fab protocols and chemical‑handling SOPs are in place for sensitive organometallics—supplier selection without internal handling capability will erode the value of lower procurement prices.
Why PW Consulting’s report matters for 2026 decisions
This briefing is purposefully high‑signal and selective. It connects the macro growth trajectory (base year 2025, historical 2020–2025, forecast 2026–2032, CAGR 7.5%, USD Million revenue framing) to the operational realities that materially affect procurement timing, supplier selection and capital allocation. The full report contains the granular segmentation, supplier scorecards, risk models and downloadable scenario tools that procurement, product and strategy teams need to convert this macro runway into executable plans.
To unlock the full dataset, proprietary supplier assessments and the decision‑grade scenarios we use to stress‑test procurement strategies, please refer to the full Worldwide PDMAT Market report. The complete report equips teams to move beyond high‑level trends and implement defensible, near‑term actions that preserve yield, minimize qualification time and secure supply through 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide PDMAT Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com