

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide PDMAT Market to Reach USD 638.7 Million by 2032 at 7.5% CAGR — Asia Pacific Leads with USD 225M (2025)

Worldwide PDMAT Market — Strategic Intelligence Briefing for 2026 Decision‑Makers
PW Consulting today releases a strategic briefing based on our forthcoming Worldwide PDMAT (Penta(dimethylamino)tantalum) Market report. Built on a five‑year historical foundation (2020–2025) and forward projections through 2032, this analysis frames the commercial dynamics that will shape supplier choices, capital allocation and technology roadmaps as semiconductor manufacturers accelerate node transitions and advanced packaging programs in 2026.
Worldwide PDMAT Market
Market snapshot: what the headline numbers mean for strategy
Our modeling uses 2025 as the base year and projects the market through a 2026–2032 forecast window. The PDMAT market, measured in USD (revenue unit: Million), has shown steady expansion in the historical period and is expected to continue on a growth trajectory with a compound annual growth rate (CAGR) of 7.5% over the forecast horizon. Practically speaking, this translates into a materially larger addressable spend for precursors used in ALD/CVD TaN barrier films and related applications by the late 2020s, shifting supplier economics and sourcing strategies for both OEMs and chemical suppliers.
Worldwide PDMAT Market
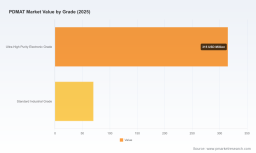
For executives preparing capital and procurement plans in 2026, the key takeaway is structural: PDMAT is a niche but high-value precursor whose market dynamics are governed more by technology roadmaps, purity and supply reliability than by raw volume alone. The premium attached to ultra‑high purity material and the specialized logistics for air‑ and moisture‑sensitive organometallics mean that strategic sourcing decisions will have outsized impact on fab yield and time‑to‑volume for customers moving to sub‑22nm and advanced Cu interconnect schemes.
Worldwide PDMAT Market
What the report delivers — practical, actionable intelligence (without spoiling the granular datasets)
- Market sizing and trajectory: validated historical series and a consensus‑calibrated forecast (2026–2032) that quantifies the commercial runway for PDMAT in USD millions and outlines sensitivity to node adoption curves and alternative precursor substitution.
- Supply‑side capability mapping: an operational review of high‑purity production methods, capacity constraints, and purification bottlenecks that determine who can reliably support high‑volume manufacturing (HVM) at scale.
- Technology and application analysis: detailed discussion of ALD vs CVD use cases, materials interoperability (TaN barrier integration), and the implications for film performance as device geometries shrink.
- Risk and compliance matrix: handling, packaging, and transport requirements for air‑ and moisture‑sensitive PDMAT, plus regulatory considerations that affect cross‑border shipments and qualification cycles.
- Go‑to‑market playbooks: supplier segmentation (research‑grade vs HVM‑ready), ideal partnership models, and M&A/outsourcing scenarios tailored to chemical suppliers, fabless houses and IDM procurement teams.
We intentionally preserve the granular segmentation tables and regional/application breakdowns for the full report. This “trailer” provides depth to build immediate confidence, while the comprehensive datasets, supplier scorecards and scenario models are available in the downloadable report package for teams ready to operationalize procurement or investment moves.
Competition landscape — who matters and why
The PDMAT supplier universe combines global life‑science/chemicals incumbents, specialized organometallic manufacturers and regional players that have optimized for local semiconductor ecosystems. Market concentration metrics underscore a relatively concentrated market: the top three suppliers control a majority share while the top five consolidate an even larger portion of available supply. That structure creates differentiated supplier power — incumbents with global reach can offer multi‑site qualification and logistics; regional producers often compete on responsiveness, pricing flexibility and proximity to leading fabs.
- Merck KGaA (EMD Group) — Darmstadt, Germany: A global incumbent known for supplying ultra‑high purity PDMAT with established distribution across major semiconductor regions. Strengths include validated quality systems for HVM deployment and multi‑region support that shortens qualification cycles for multinational fabs.
- Ereztech — United States: A nimble supplier that serves both small‑volume research requirements and more substantial batch orders, with custom packaging options (glass ampules, metal bubblers) that reflect a practical understanding of ALD/CVD system realities.
- Strem Chemicals (Ascensus Specialties) — Newburyport, MA, United States: Focused on research‑grade offerings, Strem provides high‑purity products suitable for R&D and pre‑qualification phases; their role is critical in early‑stage process development.
- Nanmat Technology — Taiwan: One of the larger regional CVD/ALD precursor manufacturers, positioned to supply Taiwan’s dense semiconductor ecosystem. Capability to scale for foundry customers is a strategic asset.
- TOPCO Scientific & PentaPro Materials (Taiwan): Regional specialists offering organometallic products tailored for local customers; they are attractive to OEMs seeking supply-chain diversity in Asia.
- Argosun & Sinocompound (China): Chinese suppliers that provide high‑purity grades and can be competitive on lead times for customers in mainland Asia; they are increasingly relevant as domestic fabs expand.
- DOCK Chemicals — Germany: A European source for ultra‑high purity precursors with specialization in manufacturing processes that target extremely low impurity thresholds.
From a strategic standpoint, buyers should assess suppliers against three clustered capabilities: (1) demonstrable ultra‑high purity production and low impurity metrics, (2) packaging/logistics expertise for moisture/air sensitive organometallics, and (3) multi‑site qualification footprints or partnerships that de‑risk supply interruptions. Where the market is concentrated, strategic dual‑sourcing and qualification of regional alternatives become essential hedges.
Dynamics shaping the market (technology, supply chain and regulation)
PDMAT’s chemistry—and the manufacturing ecosystem around it—creates inherent supply‑side barriers. Typical synthesis routes use metathesis of tantalum pentachloride with dimethylamido reagents followed by multi‑stage purification to remove chlorides and oxygen; HVM‑grade materials demand extremely low impurity ceilings, driving specialized capital and process know‑how. These purification steps and the need to maintain an inert environment across packaging and delivery elevate cost and extend qualification lead times relative to more commoditized precursors.
Operational realities matter. PDMAT is highly air‑ and moisture‑sensitive and is typically handled in inert atmospheres and supplied in specialized containers (glass ampules, metal bubblers, etc.) to preserve chemical integrity. These constraints affect logistics, on‑site handling procedures and qualification cycles for fabs integrating new precursor suppliers.
Regulatory and safety classifications confine many PDMAT offerings to R&D or industrial use profiles rather than broader commercial categories, with implications for cross‑border transport documentation and customs handling. Producers pursuing HVM markets must therefore invest not only in purity but also in compliant packaging, specialized transport relationships and the documentation infrastructure necessary for multi‑jurisdiction supply.
Strategic implications and recommended actions for 2026 planning
- Prioritize supplier qualification now if your 2026 roadmaps depend on sub‑22nm barrier performance. Qualification windows are long; securing parallel supply options reduces single‑point failure risk.
- Score suppliers on a combined metric of purity performance, packaged logistics competence, and multi‑site redundancy rather than price-only criteria. The premium for reliability can translate directly to fewer yield losses and faster ramp.
- Consider strategic investments or partnerships with regional manufacturers to shorten lead times for advanced packaging and to insulate supply chains amid geopolitical friction.
- For chemical producers and investors: target the purification and packaging nodes of the value chain. They are high‑barrier, high‑value segments where premium pricing and durable margin profiles are achievable.
- Operational readiness: ensure fab protocols and chemical‑handling SOPs are in place for sensitive organometallics—supplier selection without internal handling capability will erode the value of lower procurement prices.
Why PW Consulting’s report matters for 2026 decisions
This briefing is purposefully high‑signal and selective. It connects the macro growth trajectory (base year 2025, historical 2020–2025, forecast 2026–2032, CAGR 7.5%, USD Million revenue framing) to the operational realities that materially affect procurement timing, supplier selection and capital allocation. The full report contains the granular segmentation, supplier scorecards, risk models and downloadable scenario tools that procurement, product and strategy teams need to convert this macro runway into executable plans.
To unlock the full dataset, proprietary supplier assessments and the decision‑grade scenarios we use to stress‑test procurement strategies, please refer to the full Worldwide PDMAT Market report. The complete report equips teams to move beyond high‑level trends and implement defensible, near‑term actions that preserve yield, minimize qualification time and secure supply through 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide PDMAT Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com