

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Multi‑Sensor & Multi‑Directional Security Camera Market Poised to Reach USD 3,911.8 Million by 2032 at a 15.26% CAGR

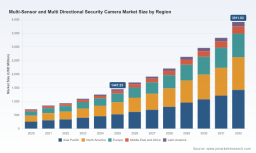
Worldwide Multi-Sensor and Multi-Directional Security Camera Market: Strategic Briefing for 2026 Decisions
PW Consulting’s new market study on the Worldwide Multi-Sensor and Multi-Directional Security Camera Market (base year 2025; forecast 2026–2032) is designed as a decision-grade briefing for technology buyers, procurement leaders, systems integrators, and corporate strategists preparing capital and operating plans in 2026. The market has moved from a nascent, fragmented investment pattern to a robust growth trajectory — expanding from roughly USD 712 million in 2020 to about USD 1,447 million in 2025, with continued acceleration into the forecast window. Our baseline scenarios project sustained expansion toward an industry size in the low billions by the end of the decade, underpinned by a compound annual growth rate of 15.26% during the forecast horizon. This briefing highlights the practical implications of that growth without disclosing the granular segment tables contained in the full report; consider this a strategic preview that surfaces the actionable insights you need to prioritize 2026 initiatives.
Worldwide Multi-Sensor and Multi Directional Security Camera Market
Why multi-sensor / multi-directional systems matter now
Security investments are increasingly being judged by coverage efficiency, analytics completeness, and lifecycle cost rather than by headcount or per-camera line-item prices alone. Multi-sensor and multi-directional architectures deliver a differentiated value proposition: broader situational awareness from fewer physical enclosures, reduced blind spots in large or complex environments, and better analytics outcomes when combined with edge AI and modern stitching/warping pipelines. Two parallel technology shifts amplify this trend in 2026:
Worldwide Multi-Sensor and Multi Directional Security Camera Market
- Edge compute and AI acceleration (including embedded platforms such as NVIDIA Jetson-class solutions) enable onboard analytics that cut server costs and reduce dependencies on centralized processing.
- Network and power advances (PoE++ and higher-efficiency codecs) make the installation of multi-sensor systems more predictable and less disruptive to existing infrastructure.
At the same time, procurement patterns are evolving: buyers demand interoperability (ONVIF-conformant products), stronger supply-chain provenance due to export control and compliance regimes, and turnkey cloud-management options that simplify operations at scale. The result is an expanding set of deployment archetypes—from smart-city wide-area surveillance to logistics hubs where a few multi-sensor enclosures can replace dozens of single-lens cameras.
Worldwide Multi-Sensor and Multi Directional Security Camera Market
Report coverage and operational value
The full PW Consulting study is built to be operational from day one. It combines market sizing and trend analysis with practical tools that enterprise teams can apply in RFPs, pilots, and technology roadmaps. Key deliverables include:
- Market sizing and scenario forecasts (global totals and modeled upside/downside cases across the 2026–2032 window).
- Technology and deployment playbooks, covering fixed multi-sensor, adjustable multi-directional, and hybrid PTZ/multi-sensor architectures.
- Procurement templates and specification checklists (including NDAA and interoperability clauses, PoE++ electrical profiles, and edge-AI capability baseline requirements).
- Vendor benchmarking and decision matrices that translate product features into procurement risk/benefit scores.
- TCO and ROI models calibrated for common end-user archetypes (e.g., public infrastructure, commercial campuses, transportation hubs, industrial sites) so buyers can move from proof-of-concept to capital approval confidently.
- Regulatory and compliance trackers that map NDAA implications, ONVIF conformance, and export-control risk to sourcing strategies.
We intentionally withhold the detailed tables and segment-level breakout in this preview so that procurement teams have a single destination for the complete, downloadable workbench and data models — the full report contains the granular line-by-line figures that operationalize these bullets.
Competition and product strategies — what stands out
The competitive field in 2026 is populated by well-established OEMs and a growing class of cloud-native entrants. Market concentration is meaningful but not prohibitive: the top three vendors account for roughly two-fifths of industry revenue, while the top five capture a bit more than half — creating space for regional specialists and solution-focused challengers to win via integration and service models.
- Hanwha Vision (Seoul; Americas presence) — Strong in wide-area, AI-enabled multi-sensor systems and recent product launches that embed high-performance onboard acceleration. Their roadmap emphasizes serverless recording and platform integration to simplify large-scale deployments.
- Axis Communications (Lund, Sweden) — Focused on modular multi-directional platforms and high-resolution panoramic models that prioritize seamless 360° coverage for complex sites where visual continuity matters.
- i-PRO (Osaka) — Differentiates on low-profile multi-sensor designs with robust edge AI and advanced auto-tracking suited for challenging lighting and environmental conditions.
- Avigilon / Motorola Solutions (Vancouver) — Combines cloud-enabled management with adjustable multi-sensor offerings and a strong enterprise channel play, emphasizing integrated analytics.
- Pelco, Rhombus, OpenEye, Digital Watchdog, Honeywell, Hikvision, Dahua, Vivotek, Bosch, AV Costar, ACTi — A diverse group spanning legacy global brands, cloud-first startups, and regional specialists. Their value propositions vary from cost-optimized panoramic modules to NDAA-compliant, enterprise-grade platforms and cloud-native analytics stacks.
Recent vendor moves underscore three market forces: product differentiation through embedded AI (e.g., deployments using onboard acceleration platforms), compliance-driven catalog updates (notably NDAA-compliant line refreshes), and continued vendor marketing around cloud-managed, PoE-driven installations. Buyers should assess suppliers not only on camera hardware but on their platform economics, firmware update cadence, and openness to third-party analytics.
Regulatory and supply-chain considerations for 2026
NDAA compliance remains a practical gating factor for many government and large enterprise deployments in the U.S., and export-control regimes continue to influence sourcing strategies for components and finished goods. ONVIF conformance is the default interoperability expectation for networked systems, but true multi-vendor operability still requires end-to-end testing in target operational environments. Mitigation strategies documented in the report include dual-sourcing, localized testing programs, firmware attestation procedures, and contractual remedies tied to continuity of supply.
Six tactical moves for procurement and technology teams
- Prioritize pilots that combine a representative space and peak-event scenarios; measure analytics precision, stitching artifacts, and end-to-end latency rather than raw camera specs.
- Mandate open standards (ONVIF) and explicitly test vendor claims for NDAA compliance and export provenance during the RFP stage.
- Budget for PoE++ planning and verify power budgets at switch and trunk levels early in the design cycle to avoid late-stage electrical upgrades.
- Insist on modularity in analytics: evaluate whether AI can be upgraded in-field and whether vendors support heterogeneous analytics stacks (edge + cloud).
- Model TCO over 5–7 years including firmware/maintenance, analytics subscriptions, and decommissioning costs — use the report’s ROI templates to stress-test scenarios.
- Develop a supplier resilience scorecard that incorporates geographic manufacturing footprints, service-level agreements, and roadmap transparency.
How PW Consulting’s study supports board-level and operational decisions
This research is structured to support both strategic planning and tactical procurement. For boards and C-level custodians, the study provides scenario-based market exposure analysis and enterprise-level risk assessments tied to supplier concentration and regulatory headwinds. For CIOs and security operations leaders, the report supplies procurement language, scoring templates, and deployment checklists that reduce pilot-to-production friction.
Because the decision calculus in 2026 increasingly ties security camera investments to operational outcomes (analytics-driven safety, automated incident detection, and integration with building and traffic management systems), buyers who align procurement with the broader enterprise technology stack will capture the most upside. The full report contains the granular forecasts, segmented revenue tables, vendor scorecards, and downloadable TCO models necessary to operationalize these recommendations.
Next steps
If your 2026 capital planning cycle includes multi-sensor or multi-directional camera investments, PW Consulting’s full report provides the detailed models, vendor intelligence, and procurement-ready artifacts you need to convert strategy into deployed capability. Consider the preview above as a high-level map: for the turn-by-turn guidance, segment-level forecasts, and the vendor comparison matrices that large-scale buyers require, please access the complete report and the companion Excel workbooks available through PW Consulting’s market research portal.
For detailed analysis of this topic, please visit the official page: Worldwide Multi-Sensor and Multi Directional Security Camera Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com