

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Paper Napkins and Serviettes Market to Reach USD 5,000 Million by 2025 as Foodservice Fuels Demand

Worldwide Paper Napkins and Serviettes Market — Strategic Outlook for 2026 Decision‑Makers
Executive summary
PW Consulting’s new market study on the Worldwide Paper Napkins and Serviettes Market synthesizes five years of historic performance with a seven‑year forecast to deliver a decision‑grade view for 2026 and beyond. The global market reached approximately USD 5,000 million in 2025 and, driven by steady end‑market demand and structural shifts in sourcing and sustainability, is projected to expand at a compound annual growth rate (CAGR) of around 4.31% through the 2026–2032 forecast window — reaching roughly USD 6.72 billion by 2032 under the base forecast. This release is intended as a strategic “trailer”: it demonstrates the depth and applicability of our analysis while reserving the proprietary, granular segment and regional datapoints for the full report and interactive dashboards available from PW Consulting.
Worldwide Paper Napkins and Serviettes Market
Why this report matters for 2026 planning
- Actionable foresight: The market is neither hyper‑volatile nor static — it is evolving along predictable but industry‑altering vectors (sustainability, cost inflation in fiber inputs, and consumption shifts in away‑from‑home channels). Procurement leaders, manufacturers, private‑equity investors, and foodservice operators require clarity on where to deploy capital and where to defend margins in 2026.
- Timing: 2026 sits at the inflection between recovery investments made in 2023–2025 (capacity expansions, product reformulations) and the operational realities of today’s input cost environment. Companies that align commercial priorities with procurement levers now will capture disproportionate share of margin expansion in the next three years.
- Decision utility: PW Consulting’s study is designed to support board‑level portfolio choices, plant‑level capacity investments, product roadmap prioritization, and channel playbook adjustments — all calibrated to the market trajectory we model through 2032.
Market trajectory and the macro picture
The napkin and serviette market has shown consistent growth from 2020 through 2025, with the market expanding from a multi‑billion base in 2020 to roughly USD 5.0 billion in 2025. Our baseline forecast — built from bottom‑up supply/demand modelling, pricing scenarios, and channel dynamics — yields a mid‑case CAGR of 4.31% for 2026–2032. That trajectory is the result of interacting forces: continued demand in foodservice and retail, product premiumization in selected channels, and regulatory and commercial pressure toward higher recycled content and certified compostable options.
Worldwide Paper Napkins and Serviettes Market
Supply‑side pressures remain a critical lever. Recent industry indicators point to elevated pulp index readings and upward movement in sanitary tissue producer prices, which feed directly into raw material cost pass‑through and supplier margin dynamics. These inputs, combined with regional regulatory moves on compostability and recycled content requirements, create a two‑track environment: near‑term cost management is essential, while medium‑term product and process innovation will determine competitive positioning.
Worldwide Paper Napkins and Serviettes Market
Key market dynamics shaping 2026 strategies
- Sustainability as a business imperative: Commercial buyers are increasingly prioritizing products with higher recycled fiber content and recognised compostability certifications. This is reshaping product specifications in foodservice and healthcare procurement tenders and influencing retail assortments.
- Input cost volatility: Pulp and sanitary tissue price indices have trended upward in early 2026, creating margin pressures for vertically integrated manufacturers and third‑party converters alike. Strategic procurement and hedging, as well as mix optimisation, become decisive in 2026 budgeting cycles.
- Channel evolution: Away‑from‑home consumption patterns are recalibrating after pandemic‑era shocks; automation and consumption‑reduction dispenser systems are gaining traction in institutional and quick‑service channels.
- Consolidation and capacity shifts: Select global players continue to invest in regional capacity expansions and differentiated product lines, while nimble regional manufacturers pursue specialty niches (certified compostable, printed/BRANDED hospitality serviettes).
Segmentation (what the report covers — without revealing proprietary splits)
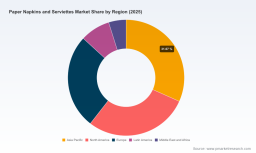
Our study dissects the market across three core dimensions: By Type (e.g., single‑ply vs. multi‑ply formats and premium tissue constructions), By Application (household retail versus foodservice and institutional channels), and By Region (major global regions and cross‑border trade flows). The full report includes volumetric and value estimates, trend lines, and sensitivity scenarios for each segment. In this communication we intentionally withhold the fine‑grained regional and application value shares to preserve the proprietary modelling that underpins our strategic recommendations; these are available in the complete report and interactive model.
Competitive landscape: major players and strategic moves
The market displays a moderate level of concentration among global incumbents with meaningful room for regional specialists and product innovators. Our competitive analysis profiles leading multinational tissue companies, regional converters, and specialist suppliers. Selected company profiles and recent developments include:
- Kimberly‑Clark Corporation (Irving, Texas): A dominant consumer and away‑from‑home brand owner, actively increasing recycled content in flagship napkin products and transitioning packaging to recycled materials.
- Procter & Gamble Co. (Cincinnati, Ohio): Leveraging strong retail positioning and product performance messaging (absorbency, multi‑use) to defend premium segments, particularly in North America.
- Georgia‑Pacific LLC (Atlanta, Georgia): Focused on commercial and institutional channels, expanding offerings that include compostable options to meet evolving procurement standards.
- Essity AB (Stockholm): Leading the professional hygiene channel with dispenser systems designed to reduce consumption; 2026 launches demonstrate material consumption reduction potential in foodservice.
- Sofidel Group (Porcari): Executing North American capacity expansion strategies to support both retail and away‑from‑home demand.
- Cascades Inc., WEPA, Metsa Group, APP, Hengan, La Pajarita, Mank: Each of these players occupies strategic positions — from certified compostable product lines to custom‑printed hospitality serviettes and regional manufacturing footprints. Their differentiated plays reflect the value opportunities in specialty channels and sustainability certification.
Recent corroborated industry moves that materially influence 2026 decision‑making include Essity’s rollout of next‑generation dispenser systems (early 2026), Sofidel’s new Ohio facility (January 2026), Kimberly‑Clark’s reformulated Scott brand with higher recycled content (late 2025), and Cascades’ launch of BPI‑certified compostable napkins (September 2025). Together, these events demonstrate an industry actively re‑tooling product portfolios and supply chains for sustainability and efficiency — not incremental changes but structural shifts that will influence contract terms, capital allocation, and product positioning in 2026.
Practical implications by stakeholder
- Manufacturers: Prioritise investments that reduce fiber intensity per use (dispensers, embossing efficiency), expand certified recycled and compostable SKUs, and tighten upstream pulp procurement strategies. Scenario planning is required to stress‑test margin outcomes under varying pulp price trajectories.
- Distributors & Broadliners: Re‑evaluate assortment strategies to include sustainability credentials as a trade differentiator and develop flexible stocking models to manage lead times from expanded regional capacity.
- Foodservice operators & Institutions: Consider capex in portion‑control dispensers and enforce procurement specifications that reward lifecycle performance (end‑of‑use compostability) to align with regulatory and customer sustainability expectations.
- Private equity & strategic investors: Look for buyouts or minority investments in regional players with clear certification credentials or in technology providers that reduce consumption per cover; valuation premia are likely for assets that demonstrably lower total cost of ownership.
Report contents — what you’ll get in the full deliverable
PW Consulting’s full report is structured to be immediately operational for commercial and procurement teams. Deliverables include:
- Detailed historical (2020–2025) and forecast (2026–2032) market model in USD millions with scenario toggles for price, volume, and substitution effects;
- Segment‑level analysis (by type, application, and region) with volumetric and value tables and sensitivity testing;
- Competitive intelligence dossiers on the leading global and regional players, including product portfolios, capacity footprints, and recent strategic moves;
- Procurement playbook and supplier negotiation levers tied to input cost scenarios;
- Regulatory and certification tracker (EU/North America hygiene standards, composting programmes, and labeling implications);
- M&A and partnership heat map with candidate targets and valuation benchmarks (for investors and corporate development teams).
How to use this analysis in 2026 planning cycles
Begin with three practical steps:
- Integrate PW Consulting’s mid‑case market model into your 2026 budgeting to stress‑test P&L under alternative pulp price paths and adoption rates for sustainable SKUs.
- Prioritise near‑term procurement and product moves that deliver both margin protection and sustainability credentials — for many companies this means a hybrid approach combining modest capex (dispensers, packaging changes) and SKU rationalisation.
- Use competitive benchmarking from our dossiers to inform go‑to‑market and capacity decisions: match your product investments to channels where willingness to pay for sustainability or performance premiums is highest.
Next steps & access
This overview surfaces the strategic conclusions and practical directions that PW Consulting’s full report unpacks in granular detail. For teams preparing budgets, RFPs, or M&A pipelines in 2026, the full dataset and scenario model are essential. To review the complete analysis, access interactive tables, or commission tailored advisory work (pricing playbooks, procurement tender support, or acquisition screening), please visit the PW Consulting report page or contact our industry practice. The full intelligence package contains the proprietary segment and regional breakdowns, downloadable models, and consulting options that are intentionally withheld here to preserve the integrity and commercial value of the analytic work.
PW Consulting — providing the market clarity you need to make confident, timely strategic choices in the Worldwide Paper Napkins and Serviettes market.
For detailed analysis of this topic, please visit the official page: Worldwide Paper Napkins and Serviettes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com