

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide 5G NR Antenna Market Poised to Expand at a 15.68% CAGR Through 2032

Worldwide 5G NR Antenna Market — Strategic Outlook for 2026 Decision-Makers
Executive Preview
PW Consulting’s latest market study, "Worldwide 5G NR Antenna Market," provides a pragmatic, decision-ready roadmap for executives preparing capital allocation, procurement, and product strategy in 2026. Anchored on a base year of 2025 and covering historical performance (2020–2025) with a forecast window through 2032, the report quantifies the commercial trajectory of 5G NR antenna systems and translates that trajectory into actionable choices for network operators, equipment suppliers, infrastructure investors and systems integrators.
Worldwide 5G NR Antenna Market
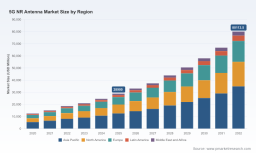
Key headline metrics (figures expressed in USD, revenue unit: Million): the market expanded from approximately USD 12.5 billion in 2020 to USD 28.9 billion in 2025, and under our central scenario is projected to reach roughly USD 80.1 billion by 2032. The forecast is driven by a compound annual growth rate (CAGR) of 15.68% over the 2026–2032 period—an environment that will reward early alignment between network plans, spectrum timelines and antenna technology roadmaps.
Worldwide 5G NR Antenna Market
What the Report Delivers — Practical Content for 2026 Planning
-
Comprehensive market sizing and multi-year forecasts, with scenario-based sensitivity analyses that isolate the impact of spectrum availability, regulatory constraints and backhaul economics on antenna demand.
Worldwide 5G NR Antenna Market -
Technology deep dives that translate radio-antenna system choices (e.g., massive MIMO architectures, hybrid active/passive designs, DAS/Distributed Antenna Systems and sub-6 vs mmWave strategies) into network-level throughput, coverage and TCO implications.
-
Deployment economics modules: detailed capex/opex modeling for macro-cell vs small-cell rollouts, fiber and fronthaul cost drivers, and trade-offs for centralized vs distributed radio architectures.
-
Supplier benchmarking and vendor playbooks: qualitative and quantitative scorecards that compare product portfolios, manufacturing footprints, certification timelines and partnership ecosystems (without publishing granular competitive splits in this executive summary).
-
Regulatory risk maps and compliance checklists addressing recent OTA emission limits, spectrum auction calendars and country-level infrastructure constraints—integrated with templates for procurement clauses and test acceptance criteria.
-
Implementation toolkits: rollout prioritization matrices, phased procurement schedules keyed to spectrum availability, and a standalone scenario model that supports “what-if” planning for funding, coverage and capacity targets.
Market Dynamics That Matter in 2026
-
Regulatory and standards shifts: 3GPP Release 19 introduced new over-the-air spatial emission limits in the upper 6 GHz band to protect incumbent satellite services. These requirements materially affect antenna pattern design, test regimes and supplier selection for upper mid-band deployments. Operators must incorporate OTA compliance testing into procurement milestones to avoid deployment delays and retrofit costs.
-
Spectrum timing and policy: legislated auction schedules and expanded spectrum identification in multiple jurisdictions introduce discrete timing risks and opportunities. For organizations deciding 2026 capex levels, spectrum milestones will be a primary determinant of when to accelerate dense urban densification vs. suburban macro enhancements.
-
Infrastructure cost pressure: fiber optic deployment costs and recent raw-material dynamics are elevating the share of backhaul/fronthaul in total deployment costs. Early contracting for high-quality fiber (including bend-insensitive and high-density types) and negotiating supply chain assurances will protect rollout economics.
-
Certification and test readiness: advances in NTN (non-terrestrial networks) and first-to-market PTCRB certifications for NTN RF conformance demonstrate that certification pathways can create first-mover advantages. Firms that align product development and test plans with emerging certification regimes will shorten time-to-revenue.
Competitive Landscape — Who’s Positioned to Win (and Why)
The antenna market is structurally consolidating: the top three suppliers account for nearly half of industry revenue, while the top five capture roughly two-thirds. This concentration creates an environment where scale, product breadth and integration capability matter—particularly for large macro and high-capacity massive MIMO deployments.
-
Ericsson (Stockholm) — Strengths: integrated massive MIMO and hybrid active-passive solutions with strong beamforming capability and macro-site optimization. Strategy: leverage systems-integration leadership to embed antennas in broader RAN deals and to influence OTA measurement standards.
-
Nokia (Espoo) — Strengths: adaptable AirScale mMIMO portfolios and hybrid approaches designed for both macro and small-cell scenarios. Strategy: drive modular architectures that allow operators to scale capacity without full site replacements.
-
Huawei (Shenzhen) — Strengths: ultra-wideband AAUs and energy-efficient massive MIMO suited to dense urban/suburban markets. Strategy: emphasize price-performance and integrated power-efficiency roadmaps where regulatory access permits.
-
Samsung (Suwon) — Strengths: high-throughput massive MIMO radios and active participation in NTN testing partnerships. Strategy: pursue specialized high-throughput deployments and strategic lab collaborations to validate edge use cases.
-
ZTE (Shenzhen) — Strengths: high-channel-count AAUs and hybrid designs for coverage-capacity balance. Strategy: continue to compete on scalability and value for macro rollouts.
-
Passive and DAS specialists — Vendors such as CommScope, Amphenol Antenna Solutions, Comba Telecom, Corning, JMA Wireless, and SOLiD play critical roles in in-building coverage, passive antenna supply and optical-RF integration. Their competitive advantage lies in venue-specific solutions, sustainability credentials and regional manufacturing footprints.
-
Regional and niche players — Companies like Tongyu Communication and PROSE Technologies focus on cost-competitive passive antennas and sustainability-optimized designs—important options for operators pursuing differentiated procurement strategies or localized supply chains.
Implications of Recent Industry Developments
-
Standard updates (3GPP R19) mean antenna vendors must adapt designs and test documentation for OTA spatial emissions. Buyers should require proof points and lab-validated procedures as part of RFP responses.
-
Product launches and certification milestones (for example, new massive MIMO units and the first PTCRB NTN test certifications) signal accelerating commercialization of advanced antenna capabilities. These events create windows for strategic pilots—especially in markets where regulatory regimes enable early mmWave or upper mid-band usage.
-
Raw material and fiber cost volatility suggests procurement teams should model scenarios with higher-than-expected backhaul costs and consider procurement techniques such as indexed long-term contracts or material hedging where feasible.
Five Tactical Recommendations for 2026
-
Adopt a “compliance-first” procurement posture: include OTA emission compliance milestones and certification deliverables in contracts to reduce retrofit risk and avoid deployment holds stemming from new spatial emission limits.
-
Prioritize modular/multi-band antenna platforms that can be field-upgraded through software and swap-in modules—this reduces stranded-capacity risk as operators acquire new spectrum tranches.
-
Harden supply chains for fiber and critical components: secure preferred supplier agreements, stagger payment terms, and build inventory buffers for long-lead items in markets facing acute fiber price pressure.
-
Design pilot programs that validate hybrid architectures and DAS in high-value venues. Use these pilots to refine acceptance criteria, validate vendor integration and collect real-world TCO inputs for a broader rollout.
-
Use the market’s concentration dynamics to negotiate ecosystem benefits: leverage the presence of scale vendors for integration discounts but retain competitive tension by qualifying regional niche suppliers for contingency sourcing and specialized applications.
How to Use This Report in Boardroom Decision-Making
The PW Consulting study is structured to be operationally useful: it maps market growth to specific decision levers (spectrum timelines, certification readiness, backhaul economics), provides vendor scorecards and tender-ready technical checklists, and includes an interactive scenario model to stress-test capital plans under alternative regulatory and cost pathways. For procurement teams, the report provides RFP templates and test acceptance matrices. For strategy teams and investors, it delivers scenario insights and M&A hot spots. For product and engineering leaders, it outlines design trade-offs between energy efficiency, array complexity and OTA emission compliance.
Note that this executive summary highlights strategic implications and headline market sizing. Detailed segment-level splits, regional breakdowns, vendor market shares and deployment-level unit economics are intentionally reserved for the full report and its companion dataset—information that materially influences competitive positioning and project-level investment decisions.
Next Steps
-
Operators and investors: use the scenario model in this report to align 2026 capex with spectrum timelines and to prioritize pilots in high-return corridors.
-
Vendors and suppliers: align product roadmaps with the OTA emission and certification requirements outlined here; use the vendor scorecard framework to benchmark go-to-market strategies.
-
Procurement and integration teams: adopt the RFP and acceptance templates from the study to lock in compliance and supply chain protections before contracts are finalized.
PW Consulting’s Worldwide 5G NR Antenna Market report combines empirical market sizing (base year 2025), forward-looking scenario analysis (2026–2032), and operational toolkits designed to reduce execution risk in the next 18–36 months. For organizations that must decide where—and when—to invest in 5G antenna capacity in 2026, the study supplies both the conviction and the instruments to act. Access to the full dataset and vendor-level benchmarking is available through PW Consulting’s report portal for teams requiring project-level specificity.
For detailed analysis of this topic, please visit the official page: Worldwide 5G NR Antenna Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com