

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Worldwide Pt Paste for Gas Sensor Market to Reach USD 170.38 Million by 2032

Worldwide Pt Paste for Gas Sensor Market: Strategic Imperatives for 2026 — PW Consulting Insights
PW Consulting’s latest market intelligence release on the Worldwide Pt Paste for Gas Sensor Market is a targeted briefing for executives who must translate materials risk, supplier strategy, and product architecture into defensible 2026 decisions. This article previews the report’s strategic value: it highlights the structural drivers, supplier dynamics, and pragmatic playbooks that matter to OEMs, Tier suppliers and investors — while protecting the detailed segmentation and proprietary datasets that compel a full download.
Worldwide Pt Paste for Gas Sensor Market
Market trajectory at a glance
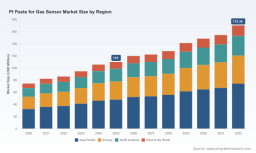
Platinum paste used in gas sensors has moved from a niche specialty into a critical materials category with discernible commercial scale. Our research shows the market expanded from USD 74.5 Million in 2020 to USD 110.0 Million in the 2025 base year. Under the forecast framework used in the report, the market grows through 2032 at a 6.45% compound annual growth rate (forecast period 2026–2032), reaching a projected USD 170.38 Million by 2032. This steady expansion reflects both unit growth in sensor deployment and rising per-unit materials value driven by PGM feedstock dynamics and advanced paste formulations.
Worldwide Pt Paste for Gas Sensor Market
Why platinum paste remains a strategic lever for sensor competitiveness
- Functional indispensability: Platinum-based pastes combine catalytic activity and electrical conduction in demanding high-temperature architectures (e.g., oxygen sensors, NOx sensing elements and certain heater designs). Many gas-sensor architectures still rely on PGM characteristics that are difficult to replace without performance trade-offs.
- Design-variant trade-offs: Manufacturers choose between high-temperature co-fired, low-temperature co-fired and thick-film conductor chemistries depending on thermal budgets, substrate compatibility, and process economics. These choices cascade into sourcing, quality control, and qualification timelines that directly affect time-to-market.
- Regulatory and reliability constraints: RoHS2-compliant, lead-free formulations and traceability requirements force sensor OEMs to align materials selection with long-term regulatory compliance and after-market liability management.
Supply-side stressors: price volatility, availability and strategic sourcing
The upstream PGM landscape has introduced a new layer of strategic uncertainty. Industry inputs indicate a multi-year platinum supply shortfall culminating in 2025, when primary supply registered a decline and above-ground stocks tightened. Platinum price volatility intensified in 2025, with market reports documenting a very sharp year-on-year increase that materially affects paste production economics. For procurement and product teams, this destroys the utility of simple unit-cost assumptions and elevates the value of hedging, recycling and supplier collaboration.
Worldwide Pt Paste for Gas Sensor Market
Practical implication: procurement teams cannot treat Pt paste as a commodity buy. The materials premium is driven by catalytic-grade requirements (surface area, particle fineness, and metallurgical form), not by bulk bullion metrics, making supply agreements, technical service and continuity clauses as influential on landed cost as raw metal pricing.
Competitive landscape: capabilities that matter in 2026
The supplier field is multi-dimensional: global PGM specialists, specialty-chemicals formulators, and niche paste manufacturers each bring differentiated value.
- TANAKA Precious Metals (Japan) — Specialist formulations for gas sensor electrodes and heaters, with an integrated powder-to-paste manufacturing model and high-temperature firing capability. Their product range indicates deep application-level engineering and strong quality controls relevant for automotive and industrial sensor OEMs.
- Heraeus Electronics (Germany) — Focus on thick-film conductor pastes and alloyed Pt compositions optimized for electrical performance and process compatibility. Recent updates to product documentation reflect continuous incremental optimization for solderability and chemical resistance in fuel-sensing and temperature-position applications.
- Dycotec Materials (UK) — Offers screen-printable fritted Pt pastes targeted at zirconia oxygen sensors and heater circuits; positions itself on fine-line printability and lower firing-temperature windows that appeal to certain ceramic substrates.
- Ferro Corporation (US) — Active in specialty thick-film formulations with emphasis on process reliability and supply support for sensor OEMs.
- Johnson Matthey (UK) & Umicore (Belgium) — Established PGM houses that contribute upstream material expertise, recycling capability and long-term feedstock strategies that support downstream paste producers.
- MANA Metal (China) & American Elements (US) — Regional and application-focused paste manufacturers supplying electrode pastes for flat oxygen sensors and SOFCs, reflecting a broader supplier base into which OEMs can tier procurement to manage risk and cost.
Recent supplier behavior underlines how technical documentation and raw-material commentary matter to buyers. Notably, Heraeus updated technical data for a solderable AuPtPd conductor in February 2026, and Johnson Matthey’s 2025 market commentary highlighted ongoing PGM deficits — both developments that are directly relevant to material selection and contracting in 2026.
What the PW Consulting report contains — practical outputs for immediate action
Our full market report is a toolkit designed for decision-making rather than an academic compendium. Key actionable deliverables include:
- Detailed market-sizing and historic demand analysis (2020–2025) and a transparent forecasting methodology for 2026–2032, including sensitivity testing to Pt price scenarios.
- Supplier capability maps and a vendor qualification framework that grades suppliers on technical fit (formulation, firing window, printability), commercial reliability (lead times, minimum order quantities), and risk mitigation (recycling, alternate feedstocks).
- Supply-chain stress tests and a cost-model that isolates PGM feedstock as a line-item and projects landed paste cost under multiple mineral and currency paths.
- Design-for-cost and materials-substitution playbooks, including low-PG content strategies, binder chemistry alternatives, and manufacturing yield levers.
- Contracting templates and strategic procurement tools (e.g., hedging thresholds, consignment inventory models, dual-sourcing triggers).
- Regulatory compliance checklist (RoHS2 alignment) and qualification roadmaps for automotive and industrial sensor standards.
- Investor-oriented comparative profiles, M&A screening criteria and partnership candidates for vertical integration or recycling collaborations.
How executives should apply these insights in 2026
- Procurement: Shift from transactional spot-buying to layered procurement: shorter-term physical coverage, medium-term fixed-price commitments with technical support clauses, and long-term evaluation of strategic inventory or recycling partnerships.
- Product management: Prioritize design changes that reduce PGM dependency where possible, while protecting sensing performance through co-development agreements with paste suppliers to trial lower-loading formulations or alternative architectures.
- Operations: Validate manufacturing process windows against multiple paste families (high-temp, low-temp, thick-film) to avoid single-chemistry lock-in; include supplier capability audits in qualification gates.
- Corporate strategy: Evaluate near-term minority investments in recycling capacity or select paste makers to secure feedstock access and to capture margin upside as paste ASPs rise with Pt input costs.
Scenario planning for board-level discussion
Our forecast is the baseline for planning, but the report includes two stress scenarios that are immediately relevant for budgeting and capital allocation in 2026: a downside scenario driven by prolonged PGM supply constraints and delayed sensor adoption in adjacent markets; and an upside scenario where accelerated deployment of advanced emission-control sensors and industrial monitoring pushes adoption. Each scenario quantifies margin impacts, supply risk exposure, and inventory/hardening capital needs — providing the basis for contingency budgeting.
Conclusion — why this brief matters to your 2026 playbook
For companies competing in gas sensing, platinum paste is no longer a line-item in a bill-of-materials: it is a strategic variable affecting product design, supply resilience and margin. PW Consulting’s report synthesizes market trajectory, supplier landscape, and hands-on commercial playbooks that change how procurement, engineering and strategy teams make 2026 decisions. The piece above previews our findings; the full report contains the granular segmentation, supplier scorecards and downloadable cost models that operationalize the insights.
To access the full dataset, supplier matrices and the step-by-step implementation toolkit, visit the PW Consulting report page for the Worldwide Pt Paste for Gas Sensor Market.
For detailed analysis of this topic, please visit the official page: Worldwide Pt Paste for Gas Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com