

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
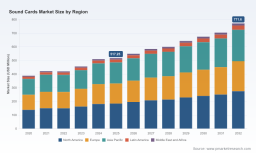
PW Consulting: Worldwide Sound Cards Market Valued at USD 517.25 Million in 2025, Poised for 5.88% CAGR to USD 771.6 Million by 2032

Worldwide Sound Cards Market 2026 Strategic Outlook: Navigating Growth Amid Supply Chain Realities
PW Consulting’s latest Worldwide Sound Cards Market report — anchored on a 2025 base year and projecting through 2032 — delivers a decision-grade, strategy-first analysis designed for executives planning 2026 investments. The market has moved from a mid-single-hundred million-dollar base in 2020 to a stronger position by 2025, and our model forecasts continued expansion through 2032. Across the 2026–2032 forecast window the market is projected to grow at a compound annual growth rate (CAGR) of 5.88%, with the total market size reaching an estimated USD 771.6 Million by 2032. These headline figures frame a market that is maturing but far from saturated — offering differentiated opportunities for product innovators, channel specialists, and strategic acquirers.
Worldwide Sound Cards Market
Why this report matters to 2026 corporate strategy
- Tactical visibility into growth corridors: Our modeling quantifies a clear, steady expansion path and isolates where incremental revenue and margin expansion are most plausible over a seven-year horizon.
- Supply-chain and policy foresight: The report synthesizes recent shifts in semiconductor export controls, tightening passive component lead times, and tariff uncertainty that will influence sourcing, cost pass-through, and time-to-market in 2026.
- Actionable risk-adjusted scenarios: Beyond a base forecast, we provide downside and upside scenarios that map to realistic procurement and product-development choices for the coming 12–24 months.
- Competitive playbooks for incumbents and entrants: The analysis translates technical product differentiation (DACs/ADCs, DSP stacks, driver ecosystems) into commercial moves — pricing, channel prioritization, and partnership strategies — that generate measurable impact in 2026.
Key market dynamics shaping strategic choices
- Steady, segmented demand: The market’s mid-single-digit CAGR reflects a balance between enduring professional/studio demand and renewed consumer interest driven by gaming, home entertainment, and creator economies. This creates room for premium, mid-market, and value-tier propositions.
- Component and policy friction: U.S. export controls on advanced semiconductors, tighter lead times for passives and discretes late in 2025, and tariff uncertainty into 2026 introduce input-cost volatility and sourcing risk that must be actively managed in supplier contracts and inventory planning.
- Technology-driven differentiation: Ongoing innovation in DAC/ADC performance, integrated DSP platforms, and better driver/firmware ecosystems means hardware alone is no longer sufficient; software and user experience increasingly determine premium positioning.
- Market concentration and competitive balance: The market is moderately concentrated: our concentration metrics indicate that leading firms hold a meaningful but not dominant share, leaving room for nimble challengers and strategic consolidators.
What the report contains — practical components for 2026 execution
- Demand model and scenario suite: A base-case forecast plus stress-tested upside and downside scenarios tied to component pricing, export control severity, and consumer device upgrade cycles.
- Go-to-market playbooks: Segmented strategies for OEM, retail, and direct-to-consumer channels — including recommended channel mixes, promotional levers, and subscription/service tie-ins for different price tiers.
- Product and technology roadmaps: Comparative feature matrices for external vs. internal form factors, high-fidelity vs. budget designs, and latency/DSP trade-off guidance for professional and gaming audiences.
- Supply-chain heatmaps and sourcing playbook: Supplier risk scoring, dual-sourcing templates, and cost-pass-through scenarios to protect margin in a volatile component environment.
- Competitive benchmarking: Strategic profiles for the major players, capabilities mapping, and M&A target screening criteria — designed to accelerate due diligence and integration planning.
- Pricing and margin toolkit: Elasticity experiments, margin optimization simulations, and SKU rationalization recommendations to maximize 2026 profitability without sacrificing growth.
Competitive landscape — strategic implications for core players
Our assessment synthesizes product portfolios, channel footprints, and technology moats across established OEMs, professional-audio specialists, and value-focused entrants. Leading providers exhibit distinct strategic postures that will influence competitive dynamics in 2026:
Worldwide Sound Cards Market
- Creative Technology Ltd. (Singapore): Continues to anchor the consumer/gaming lead with a recognized brand and a steady cadence of product enhancements, most recently with a USB DAC/amp launch and firmware updates aimed at measurable PCM performance gains. Creative’s ability to pair hardware with software ecosystems remains a key advantage — and a blueprint for competitors seeking to monetize post-sale services.
- ASUS (Taiwan): Leverages motherboard and gaming hardware expertise to defend high-fidelity and enthusiast niches. ASUS’s cross-product bundling and software suites create stickiness in gaming ecosystems — a worthwhile avenue for alliances between component suppliers and platform vendors.
- Realtek (Taiwan): As a dominant audio codec and chipset supplier, Realtek’s scale underpins the majority of onboard audio solutions. For strategic buyers and OEMs, Realtek’s roadmap and availability are critical — export controls and onshore capacity expansions are therefore key risk factors to monitor closely in 2026.
- Professional-audio specialists (UK/USA/Germany/Japan): Firms such as Focusrite, Universal Audio, RME, MOTU, PreSonus, and Roland maintain premium positions through superior converters, low-latency drivers, and pro-grade feature sets. These vendors are less price-sensitive but highly sensitive to component quality and driver stability — areas where partnership with specialized chipmakers can yield defensive advantages.
- Value/aftermarket players (USA/Germany/others): Brands like Sabrent and Behringer target volume-oriented segments. Their playbook for 2026 will hinge on cost discipline, supply-chain resilience, and rapid time-to-market for trend-driven SKUs.
- Chip/IC suppliers and niche vendors: C-Media, and other controller suppliers, remain indispensable to aftermarket and OEM sound-card suppliers. Innovations in DAC/ADC silicon from specialized vendors are enabling next-generation products; securing priority supply or co-development agreements will be decisive for companies targeting the professional and high-end consumer spaces.
Strategic moves we recommend for 2026
- De-risk procurement: Move from single-source to prioritized dual-source strategies for critical analog/digital converters and passive components; implement staged inventory buffers tied to scenario triggers from our report’s supply heatmap.
- Monetize software: Where product differentiation narrows, bundle firmware, tuning profiles, and cloud-based presets/subscriptions to extend ARPU and reduce sensitivity to hardware ASP pressure.
- Segment-focused product stacks: Build distinct platforms for pro studios, gamers/creators, and mainstream consumers — standardize modular electronics to shorten product cycles and enable tiered feature activation through firmware licensing.
- Pursue selective verticalization: Consider vertical partnerships or minority investments with converter manufacturers to secure capacity and favorable pricing, or to co-develop next-generation DAC/ADC IP aligned to professional workflows.
- Use M&A as a capability lever: Bolt-on acquisitions can accelerate software, driver, or professional market access. Our M&A playbook evaluates targets by capability gap, integration complexity, and near-term revenue accretion potential.
Risk considerations and mitigation
Key risks for 2026 include regulatory shifts (notably semiconductor export controls), component shortfalls and price spikes, and tariff volatility affecting imported modules. Our report translates these risks into operational thresholds and recommended contract language (e.g., indexation clauses, priority allocation terms) to protect margins and continuity of supply. We also highlight upside catalysts — such as accelerated DAC/ADC adoption in creator hardware and expanded domestic chip capacity — that could compress time-to-profitability for new premium products.
Worldwide Sound Cards Market
How to use this insight
Executives preparing budgets, product roadmaps, supply contracts, or M&A activity for 2026 will find the PW Consulting report especially valuable. It equips teams with a quantified market outlook, scenario-triggered action lists, and vendor-specific playbooks that translate market movement into concrete, testable initiatives. For boards and investors, the report provides a clear view of risk-reward trade-offs across strategic options — from investing in premium R&D to pursuing volume-driven cost leadership.
To access the full dataset, regional and application splits, company-level scorecards, and the decision-ready toolkits referenced here, visit the PW Consulting Worldwide Sound Cards Market report page. The published report contains the detailed segmentation and granular forecasts that underpin the high-level insights presented in this release — essential inputs for any 2026 strategy that seeks to convert forecasted growth into sustained competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Sound Cards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com