

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Picrorhiza Extract Market Set to Reach USD 80.6 Million by 2032, Expanding at a 6.42% CAGR (2026–2032)

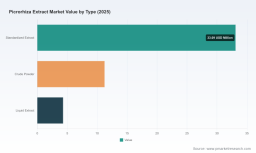
Worldwide Picrorhiza Extract Market — Strategic Outlook for 2026
PW Consulting’s latest market brief on the Worldwide Picrorhiza Extract Market provides senior executives, procurement leads, R&D heads and investors with a purpose-built strategic compass for 2026. Drawing on a multi‑year historical series, forward-looking scenario modeling and direct supplier intelligence, the report converts a technically complex specialty botanicals market into high‑conviction actions — while reserving full granularity to our published study to preserve commercial value.
Worldwide Picrorhiza Extract Market
Market trajectory at a glance
The Picrorhiza extract market has moved from niche to a structurally growing specialty segment. Our base-year series shows the global market expanding from USD 34.62 Million in 2020 to USD 48.65 Million in 2025, with a projected market value of USD 52.93 Million in 2026. Under the report’s central forecast, the market grows at a compound annual growth rate (CAGR) of 6.42% through the 2026–2032 horizon, reaching roughly USD 80.6 Million by 2032.
Worldwide Picrorhiza Extract Market
These topline dynamics reflect a combination of demand-side uplift (renewed interest in herbal actives across nutraceutical, pharmaceutical and personal care applications) and constrained supply driven by geography, regulation and raw‑material pressure. For decision-makers, the headline numbers are an early indicator: the market is sufficiently large to justify strategic engagement but remains concentrated enough to reward targeted sourcing and premiumization strategies.
Worldwide Picrorhiza Extract Market
Why 2026 is an inflection point for corporate planning
- Regulatory pressure and conservation constraints: Picrorhiza kurroa has been regulated internationally for decades and remains subject to trade restrictions and national controls designed to protect wild populations. These constraints are reshaping supply chains and accelerating demand for cultivated, certified feedstocks.
- Supply gap and sourcing scarcity: Historical industry reporting shows that annual raw‑material demand has outstripped sustainable supply, creating a structural supply deficit that is catalyzing organized cultivation and upstream investments.
- Scientific momentum: Recent publications (including a January 2026 preprint identifying Picrorhiza kurroa as a potential prebiotic when combined with Lactobacillus fermentum) are expanding application avenues and value‑capture opportunities beyond traditional uses.
For executives, 2026 is when strategic choices made today — secure offtake agreements, cultivation investments, or product innovation partnerships — will materially influence market position for the remainder of the decade.
What the PW Consulting report delivers — practical, decision‑ready content
- Transparent market sizing and validated growth scenarios (historic 2020–2025 series and 2026–2032 forecasts).
- Supply‑chain heatmaps and risk scoring for sourcing geographies, processing nodes and logistical pinch points.
- Regulatory and conservation compliance matrices, including trade control impacts and actionable mitigation steps.
- Go‑to‑market playbooks for product teams: formulation windows, claim substantiation pathways and prioritization of pipeline opportunities.
- Vendor intelligence with operational profiles, capability assessments and commercial negotiation levers.
- M&A and partnership screening framework: valuation levers, integration risks and sample term structures for offtake/anchor investments.
Each deliverable is focused on implementation: checklists, template term sheets and scenario‑driven recommendations that procurement, R&D and corporate strategy teams can apply in Q1–Q3 2026.
Competitive landscape — tactical implications from supplier intelligence
The Picrorhiza extract supply base is regionally concentrated among specialist botanical firms, with a meaningful presence of India‑ and China‑origin producers. Our vendor map identifies several active commercial suppliers and their operational profiles, including manufacturers and exporters emphasizing organic standards, bulk B2B supply, and standardization capabilities.
- Established Indian producers are differentiated by export scale, organic and conventional supply lines, and experience in serving nutraceutical value chains. Their strengths include bulk manufacturing, compliance to international buyer expectations, and familiarity with the Himalayan sourcing environment.
- Chinese producers provide complementary supply options, typically serving formulators with cost‑competitive offerings and regional logistics advantages for Asian buyers.
- Smaller specialists and contract exporters often occupy niches (industrial powders, specific packaging formats, short lead‑time lots) and can be attractive partners for flexible sourcing and toll manufacturing.
Market concentration metrics highlight a fragmented market: the top three and top five suppliers together account for a minority share, which means there is room for new entrants and for buyers to diversify. This fragmentation, paired with material supply constraints, creates a window for commercial arbitrage — premium pricing for certified, traceable supply and consolidation opportunities for strategic acquirers.
Supply chain and sourcing risks — what to watch and act on now
- High‑altitude sourcing constraints: Picrorhiza is a high‑altitude species whose primary economic parts are roots and rhizomes harvested in sensitive Himalayan ecosystems. Transport, batch traceability and seasonality are non‑trivial operational risks.
- Wild‑collection regulation: International and national controls — including long‑standing listings designed to curb overharvest — increase compliance cost and can limit volumes unless cultivated sources are developed and certified.
- Quality and standardization variability: Differences in raw material handling, extraction methods and standardization mean that ingredient quality can vary significantly between suppliers. Buyers face the choice between locking in premium, certified supply or managing a broader, lower‑cost supplier pool with more quality gating.
Mitigants for 2026: build multi‑tier supply strategies (short‑term spot, medium‑term offtake, long‑term cultivation partnerships), insist on chain‑of‑custody documentation, and prioritize suppliers that can scale cultivated output in line with conservation policies.
Product and R&D opportunities
Recent scientific developments are the most actionable signal for product teams. Independent research demonstrating prebiotic potential when Picrorhiza is formulated with specific probiotic strains opens a new product class — synbiotic herbal formulations — that can attract premium positioning in dietary supplements and specialized clinical nutrition. Alongside this, ongoing cultivation research demonstrates pathways for scaling sustainable feedstock that meet both conservation and commercial needs.
Recommended R&D moves for 2026:
- Prioritize bioactivity and formulation work that validates target claims (e.g., prebiotic, hepatoprotective adjunctions) under realistic processing conditions.
- Design clinical or pilot human studies to convert novel mechanistic findings into branded health claims acceptable in key regulatory jurisdictions.
- Explore co‑development partnerships with suppliers who can guarantee traceable, standardized extract batches for reproducible studies.
Regulatory and sustainability playbook
Regulatory realities are not a distant compliance exercise; they are a commercial lever. Picrorhiza’s listing under international trade control mechanisms and national restrictions in source countries both raise the bar for documentation and create a de‑risking premium for certified cultivated material. Corporates should:
- Develop a compliance matrix for each target market, mapping required documentation, permitted claims and labeling constraints.
- Create a sustainability procurement policy that balances conservation commitments with secure supply, including community benefit agreements and traceability audits.
- Use certification and third‑party stewardship as differentiation in B2B negotiations: certified cultivated supply can command better commercial terms and faster regulatory acceptance.
Investment, M&A and partnership signals
For 2026, the most attractive corporate moves are pragmatic and risk‑calibrated:
- Secure midstream exposure through offtake agreements and minority investments with option‑to‑acquire clauses tied to cultivation scalability.
- Consider bolt‑on acquisitions of extraction capabilities or packaging specialists to reduce time‑to‑market for new formulations.
- Enter strategic partnerships with farmer cooperatives or upstream cultivators to create exclusive supply corridors that align with sustainability commitments.
These choices preserve optionality while capturing upside as demand validates premium positioning and new applications mature.
How PW Consulting’s report supports 2026 decisions
Our report combines rigorous market modeling (historic 2020–2025 series and 2026–2032 scenario outputs) with operational vendor intelligence, regulatory de‑risking playbooks and transaction frameworks. It is structured to be directly usable by procurement RFPs, M&A diligence and product development roadmaps. To respect the “teaser” principle integral to corporate research, we present the full methodology, all model outputs and subsegment breakouts in the subscription report available on our site — these include the granular regional and application splits, supplier scorecards and downloadable commercial templates that informed the strategic recommendations summarized here.
Next steps — where to focus in Q1–Q3 2026
- Run parallel supply scenarios: secure short‑term cover with vetted suppliers while negotiating medium‑term cultivated offtake.
- Begin targeted formulation pilots leveraging the latest prebiotic data and lock in small, traceable batches for reproducible testing.
- Embed sustainability clauses in procurement contracts and pilot community‑based cultivation projects to de‑risk regulatory exposure.
- Use competitive fragmentation to negotiate favorable commercial terms with specialist suppliers, while monitoring consolidation opportunities for strategic acquisition.
Picrorhiza extract is an example of a specialty botanical where scientific novelty, ecological scarcity and regulatory complexity intersect to create both risk and differentiated commercial value. PW Consulting’s market brief equips leaders with the analytic lens and practical tools needed to convert this dynamic into defensible market positioning in 2026 and beyond. For the full dataset, supplier dossiers, and downloadable templates that underpin the recommendations above, please consult the full report on our website.
For detailed analysis of this topic, please visit the official page: Worldwide Picrorhiza Extract Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com