

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide BARC Market to Rise from USD 962.0 Million in 2025 to USD 1,516.7 Million by 2032 at 6.72% CAGR — Asia Pacific Leads with USD 596.4M; Organic BARC and ArF Lithography Dominate, Top 3 Hold 65.4%

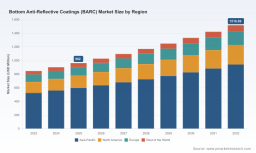
Worldwide Bottom Anti-Reflective Coatings (BARC) Market — Strategic Briefing for 2026 Decisions
PW Consulting’s latest market study on Worldwide Bottom Anti-Reflective Coatings (BARC) provides a concise, decision-focused synthesis aimed at executives, procurement leads, R&D heads and investors who must take concrete actions in 2026. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the study projects the market to grow at a compound annual growth rate (CAGR) of 6.72% from 2026 through 2032. To give immediate scale context: the industry moved from roughly USD 846 million in 2023 to an estimated USD 962 million in 2025, and under the base forecast the market reaches approximately USD 1,516.7 million by 2032. Market concentration remains meaningful — the top three players control a majority share (CR3 ~65.4%), and the top five increase that coverage further (CR5 ~82.2%) — underscoring that strategic incumbents and a small set of challengers will shape technology adoption and price dynamics going into 2026.
Worldwide Bottom Anti-Reflective Coatings (BARC) Market
Why this matters for 2026 strategy
-
Timing complexity: Qualification cycles for new BARC chemistries (particularly those aimed at EUV and high-NA systems) stretch across quarters. Procurement and process-integration decisions taken in 2026 will materially affect fab readiness for node transitions in 2027–2029.
Worldwide Bottom Anti-Reflective Coatings (BARC) Market -
Margin and cost pressure: Upstream input volatility — exemplified by an ~8% year-on-year increase in key resin monomers — is compressing supplier margins and will be passed through selectively to buyers unless mitigated by sourcing or formulation changes.
Worldwide Bottom Anti-Reflective Coatings (BARC) Market -
Regulatory and trade shocks: New restrictions (REACH Annex XVII) on certain aromatic solvents and an active tariff environment (including a 25% import tariff on BARC imports from China effective after the 2025 review) require geographies and product portfolios to be re-evaluated for compliance and landed cost impact.
-
Logistics friction: Elevated transport surcharges linked to route disruptions (a representative surcharge of USD 0.15/kg has been observed on Asia–Europe chemical shipments) add an often-overlooked incremental cost layer for international supply chains.
What the report delivers — operational intelligence, not theory
-
Proprietary market model: A flexible Excel-based model that allows users to run demand scenarios across 2026–2032, toggle macro assumptions (node adoption curves, lithography mix shifts) and test price elasticity under different raw-material and tariff regimes.
-
Vendor scorecards: Comparative benchmarking of the market’s leading suppliers across technology readiness, product breadth, qualification cycle length, manufacturing footprint and commercial flexibility. (Note: detailed vendor scores and subsegment data are only available in the full report.)
-
Supply-chain mapping: End-to-end supplier and raw-material dependency maps, highlighting single-source risk, geographic concentration and alternative feedstock pathways suitable for fast-track qualification.
-
Scenario playbooks: Three executable strategic paths for suppliers and three for fabs — each with investment triggers, expected payback bands, capex sizing guidance and sample procurement timelines.
-
Technology roadmap & IP heatmap: A practical view of where R&D dollars should flow for next-generation BARC chemistries (EUV-compatible, high-NA-ready, solvent-restricted formulations) and an assessment of patent clustering by incumbent and new entrants.
-
M&A & partnership shortlist: A vetted list of targets and partnership archetypes (manufacturing capacity buys, specialty-resin carve-outs, co-development partnerships) suitable for accelerating route-to-market, together with preliminary valuation heuristics.
-
Risk & compliance dossier: Regulatory and tariff monitoring templates plus modelled cost impacts for EU REACH scenarios and US import tariff cases, to support rapid executive decision cycles in 2026.
Competitive landscape: what incumbents and challengers are doing
The market is dominated by a cluster of experienced specialty-chemical suppliers and a handful of diversified materials groups. Several strategic patterns are clear heading into 2026:
-
Focused product innovation: JSR Corporation has openly targeted the next frontier of lithography by introducing an EUV-compatible BARC for high-NA systems (Oct 2025). This move signals that leading suppliers are prioritizing high-value, high-barrier offerings that align with advanced-node roadmap timing.
-
Capacity and qualification plays: Tokyo Ohka Kogyo expanded production capacity in 2025 to serve very advanced node demand — a defensive and offensive step that shortens lead times for existing customers and raises the bar for new entrants.
-
Quality and standards alignment: Shin-Etsu’s recent certifications emphasize the premium placed on reliability and process integration within fabs; certification and qualification are de facto market access gates in this sector.
-
Consolidation and rebranding: Several historical players have been absorbed into larger chemical platforms (e.g., Dow’s BARC portfolio integration into DuPont; AZ Electronic Materials now operating under Merck KGaA). Consolidation accelerates scale advantages but creates customer concerns about product roadmap continuity.
Strategic implication: buyers will increasingly select suppliers not only on price and chemistry but on their demonstrated ability to support long qualification cycles, localize supply where tariffs or logistics penalties bite, and offer roadmap alignment for EUV/high-NA transitions.
Key market dynamics and immediate risk mitigations
-
Raw-material inflation: The ~8% rise in certain resin monomer prices forces a two-track mitigation: (1) short-term hedging and extended fixed-price contracts with key suppliers; (2) accelerated co-development of lower-cost or more readily available monomer alternatives to reduce cost pass-through risk.
-
Regulatory reformulation: REACH restrictions on aromatic solvents make pre-emptive reformulation a commercial necessity for suppliers targeting EU customers. Buyers should request REACH-compliant formulation roadmaps and qualification timelines as part of procurement negotiations in 2026.
-
Tariff exposure and nearshoring: The 25% tariff on China-origin BARC imports to the US materially shifts landed-cost math. A combination of regional production presence, toll-manufacturing agreements and strategic inventory placement will be required to maintain competitive lead times at acceptable costs.
-
Logistics surcharge contingency: Even seemingly modest surcharges (e.g., USD 0.15/kg) compound when multiplied across volume-heavy annual procurement — include logistics surcharge scenarios in TCO calculations and consider regional buffer inventories for critical SKUs.
Recommended strategic plays for 2026 — who should do what
-
For suppliers: prioritize dual-track R&D — maintain incremental improvements for existing nodes while fast-tracking EUV/high-NA chemistries; shore up regional manufacturing where tariffs and logistics are punitive; and embed long-term supply contracts with key fabs to stabilize demand signaling.
-
For semiconductor fabs and IDM procurement: accelerate vendor qualification sequencing for next-gen lithography BARC now, lock volume-flexible contracts including raw-material cost pass-through terms, and require supplier compliance roadmaps for solvent restrictions and export-control risks.
-
For private-equity and strategic investors: evaluate targets that provide either specialty-resin IP or regional manufacturing bases; prioritize bolt-on acquisitions that shorten qualification timelines or supply chains for target customer segments.
-
For policymakers and trade teams: coordinate with industry to create rapid-compliance channels for reformulated chemistries and explore mitigation for tariff and logistics consequences that risk hollowing domestic production capabilities.
Trailer: what we’ve intentionally withheld and where to get it
In keeping with the “trailer” principle, this briefing highlights strategic value and the actionable levers companies must consider in 2026 — while deliberately omitting core granular subsegment figures and full vendor scorecard metrics that form the premium analytic engine of the study. The full report contains the complete segmentation matrices, downloadable forecast model, supplier benchmarking with scorecards and M&A shortlists that support immediate execution. For teams preparing capex approvals, vendor negotiations, or M&A diligence in 2026, those datasets are practical necessities.
To obtain the full report, the market model and the executable playbooks referenced here, please contact PW Consulting or visit our report page to access the complete Worldwide BARC Market study and supporting materials.
For detailed analysis of this topic, please visit the official page: Worldwide Bottom Anti-Reflective Coatings (BARC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com