

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Fabric Flame Retardancy Testers Market Poised to Grow at a 5.45% CAGR During 2026–2032

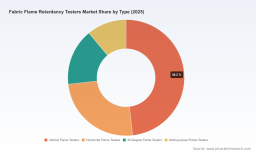
Worldwide Fabric Flame Retardancy Testers Market: A Strategic Preview for 2026 Decision‑Makers
PW Consulting’s latest market study on Worldwide Fabric Flame Retardancy Testers provides a focused, operationally-oriented roadmap for executives, procurement leaders, lab directors and investors positioning themselves for 2026 and beyond. The study synthesizes long‑run demand patterns, standards evolution, supplier capabilities and cost dynamics into practical decision tools. This preview highlights the report’s strategic value while reserving the granular segmentation tables and downloadable financial models for report subscribers.
Worldwide Fabric Flame Retardancy Testers Market
Market trajectory at a glance
The fabric flame retardancy testers market has shown steady growth through the early 2020s, expanding from the low‑double‑digit millions in 2020 to an estimated USD 115.8 million in 2025 (base year). Our forecast model projects continued expansion into the latter part of the decade: the market is expected to exceed USD 122 million in 2026 and reach the high‑hundreds of millions by the early 2030s, reflecting a compound annual growth rate of approximately 5.45% across the forecast window. That growth is driven by a blend of regulatory tightening, product safety imperatives across textiles and interiors, and replacement/upgrade cycles at independent testing houses and OEM captive labs.
Worldwide Fabric Flame Retardancy Testers Market
Why this matters for 2026 corporate strategy
- Procurement and CAPEX planning: With predictable, mid‑single‑digit CAGR growth, buyers can model replacement versus retrofit decisions for test benches and chambers. The market’s steady expansion supports staged investments (modular upgrades) rather than one‑time, high‑risk outlays.
- Regulatory compliance and product design: Changes to flammability standards and enforcement activity make tester selection a strategic lever for apparel, automotive interiors and building product manufacturers to de‑risk launches and demonstrate compliance.
- Aftermarket and service revenues: As testers age, demand shifts toward calibration, spare parts and upgrade kits. Companies that build service networks and subscription calibration programs can create recurring revenue streams that outpace equipment sales.
- M&A and partnership strategies: The market’s moderate concentration profile creates attractive targets for bolt‑on acquisitions—particularly for vendors seeking geographic reach or standards expertise.
What the full report delivers (practical content)
PW Consulting’s report is structured to move decision‑makers from insight to execution. Key deliverables include:
Worldwide Fabric Flame Retardancy Testers Market
- Proprietary market sizing and a flexible forecasting model (2026–2032) that can be re‑run with client assumptions.
- Demand driver analysis that links regulatory updates, end‑market growth and lab capacity to tester demand.
- A standards matrix mapping test methods (vertical/horizontal/45°/curtain, UL/ASTM/ISO/NFPA/GB/EN/ECE) to equipment features and procurement spec templates.
- Competitive benchmarking with feature‑level scorecards, channel and service footprints, and buyer reference profiles.
- Operational playbooks: lab setup checklists, calibration and traceability templates, total cost of ownership (TCO) models, and maintenance/service contract negotiation guides.
- An M&A screening toolkit with valuation sensitivities, integration risks, and capabilities mapping for potential targets.
Each of these outputs is oriented to be immediately usable by purchasing teams, lab managers and corporate strategists—while the full dataset, including downloadable Excel models and segmented forecasts, is available from the report portal.
Competitive landscape: how to interpret vendor positioning
The vendor field spans global incumbents and regional specialists. A small group of suppliers capture a meaningful share of formal installations, but the market retains fragmentation at the lower tiers. Top suppliers combine standards breadth, automation capability and after‑sales networks to win institutional contracts, while smaller vendors often compete on price and rapid customization.
Representative vendor positioning in the study illustrates common strategic archetypes:
- Comprehensive product line owners who cover vertical, horizontal, 45° and specialty test rigs and who emphasize standards compliance and lifecycle support.
- Specialists focused on specific test methods or end‑markets (e.g., curtain/vertical propagation or automotive interior chambers) that win by superior process control and niche certification experience.
- Automation and digital incumbents who pair mechanical rigs with PLC/optical measurement and reporting suites designed for high‑throughput labs or manufacturing QCs.
- Regional players with cost advantages and rapid local service, particularly in growth markets where localized calibration and spare parts responsiveness are high‑value.
The market concentration metrics in our report indicate a moderate degree of aggregation among the top vendors—enough to support strategic alliances and acquisitions, but with ample opportunity for challengers that can combine standards depth with service excellence.
Standards and regulatory dynamics shaping procurement
Standards evolution is a primary demand shaper for testers. Recent and ongoing items of note include amendments to established national standards and persistent relevance of legacy methods that buyers still require. For example, amendments to the U.S. consumer flammability standard for clothing textiles have been implemented in recent years, expanding permissible equipment models while leaving core flammability class outcomes intact—an important distinction for labs choosing future‑proof equipment. Meanwhile, vertical flame resistance protocols (commonly used for protective clothing) and ISO‑based flame spread procedures remain central reference points for many purchasers.
For equipment buyers, the implication is clear: purchase strategies should prioritize configurability and certifiability across multiple standards, and procurement specifications must explicitly require traceability to the relevant test methods and documented calibration paths.
Supply‑side signals and cost implications
Capital equipment makers operate against a backdrop of raw material cost volatility. Recent trends show steel price stabilization after prior volatility, with futures broadly signalling modest firmness into early 2026; aluminum mill shapes have experienced notable year‑on‑year increases. These dynamics translate into two operational realities for purchasers: lead times and list prices for new rigs can vary meaningfully with metal price cycles, and manufacturers may respond with engineered substitutions or modular designs to manage bill‑of‑materials cost jumps.
Buyers looking to optimize TCO should therefore negotiate price‑adjustment clauses, multi‑year service contracts that lock spare parts pricing, and explore local manufacturing or sourced components to reduce exposure to global metal cycles.
Priority actions for 2026
- Adopt a modular investment strategy: specify platforms that accept incremental sensor and automation upgrades to spread CAPEX over the tester lifecycle.
- Require multi‑standard certification and documented calibration pathways in procurement RFPs to avoid later retrofit costs.
- Build localized calibration and spare parts capacity in high‑use regions to reduce downtime—either via partner networks or controlled distributor agreements.
- Implement TCO and scenario models when assessing supplier bids; ask vendors for service revenue forecasts and spare‑parts life curves.
- Pursue targeted M&A or partnership for service network expansion in markets where in‑country calibration and accreditation create competitive advantage.
- Hedge raw‑material exposure through supplier agreements with price indexation or extended firm‑price windows for critical mechanical parts.
How PW Consulting’s report supports implementation
Beyond diagnostic analysis, the published study provides the tactical instruments that sourcing teams and lab directors need to act: editable forecast models, procurement RFP templates keyed to standards coverage, comparative supplier scorecards, and an execution checklist for establishing accredited test capability. For strategy teams, our M&A screening tools and competitor capability maps reduce discovery time and clarify integration priorities.
This preview lays out the strategic contours for 2026—what matters, why it matters, and what to do next. For readers requiring the full segmented forecasts, downloadable models, and the vendor‑level benchmarking matrices that underpin the recommendations, the complete report and associated toolkits are available from PW Consulting’s report page. Those resources contain the detailed regional and application splits, scenario runs and unit‑level pricing tables needed to finalize procurement budgets, acquisition targets and lab expansion plans.
Contact PW Consulting to access the full Worldwide Fabric Flame Retardancy Testers Market report and obtain client‑only briefings and template bundles tailored to your organization’s 2026 strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Fabric Flame Retardancy Testers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com