

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Nefopam Hydrochloride Market Poised to Reach USD 374.44 Million by 2032, Growing at a 5.5% CAGR

Worldwide Nefopam Hydrochloride Market — Strategic Imperatives for 2026
Executive summary
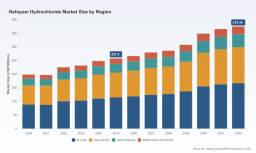
PW Consulting’s latest Worldwide Nefopam Hydrochloride Market report (base year 2025, historical 2020–2025, forecast 2026–2032) synthesizes commercial, clinical and regulatory intelligence into an actionable roadmap for executives planning their 2026 strategies. The market has expanded from roughly USD 198 million in 2020 to about USD 257 million in 2025, and our modelling projects continued expansion through the forecast window with a compound annual growth rate (CAGR) of approximately 5.5%, reaching the low hundreds of millions by the early 2030s. These headline numbers understate important structural shifts—shifts this report teases and unpacks for boardrooms, corporate development teams and commercial leaders without divulging every granular split in this summary.
Worldwide Nefopam Hydrochloride Market
Why this report matters for 2026 decision-makers
- Timing and optionality: 2026 will be a pivotal year for companies seeking to convert clinical momentum into sustainable commercial access. A small number of supply and filing advantages will determine who captures premium value.
- Regulatory frontiers: Divergent regulatory pathways across geographies create selective market openings. The absence of an approved US marketing authorisation remains a strategic barrier for global expansion, while established authorisations and national formularies across Europe and other markets create differentiated access corridors.
- Concentration and sourcing risk: With a moderately concentrated supplier base (CR3 ~58.4%; CR5 ~74.2%), downstream manufacturers and formulation specialists must prioritise supply security and qualification of alternate API sources to avoid production disruption and pricing pressure.
- Clinical evidence is shifting positioning: Emerging randomized data and formulation patents are reshaping the value proposition versus opioid and multimodal analgesic regimens—presenting both commercial upside and regulatory complexity.
Market dynamics and near-term catalytic events
The market’s steady growth is being driven by three interacting vectors: clinical evidence evolution, formulation and IP activity, and payor positioning. Recent developments illustrate this dynamic:
Worldwide Nefopam Hydrochloride Market
- IP and formulation innovation: In February 2025, a new patent was granted for an optimized nefopam hydrochloride formulation intended for acute and chronic pain, with the patent-holder signalling plans for Phase 2 studies. Such assets change the competitive calculus by enabling differentiated dossiers and lifecycle strategies.
- Clinical outcomes informing use-cases: A randomized, placebo-controlled, double-blind trial published mid-2025 evaluated nefopam for analgesia after cardiac surgery—evidence that can expand perioperative use-cases if results are favourable to efficacy and safety endpoints.
- Formulary assessments and cost-positioning: National formulary updates in 2025 demonstrate how local cost- and positioning-decisions influence uptake, particularly where an authorised alternative analgesic class exists.
- Regulatory contours: Nefopam is not approved for marketing in the United States, a long-standing constraint on volume expansion in that market. Conversely, several European national authorisations and past EMA decisions (including regulatory waivers for paediatric investigations in defined combinations) create a patchwork that rewards targeted go-to-market plans.
- Opioid-sparing narrative: Meta-analyses and reviews report a meaningful opioid-sparing signal for nefopam when used in multimodal regimens—an important commercial message as health systems pursue opioid stewardship.
Competitive landscape — who matters and why
Competition in the nefopam value chain spans API producers, integrated generic manufacturers and specialty formulation players. The market’s measured concentration (CR3 ~58.4%; CR5 ~74.2%) indicates that a few players exert significant influence over price and availability. Key participants covered in the report include:
Worldwide Nefopam Hydrochloride Market
- Polpharma (Poland) — A certified API producer with GMP and dossier capabilities; a strategically positioned European supplier for companies seeking EU-compliant API sourcing.
- Global Calcium (India) — Export-oriented manufacturer of nefopam API serving both domestic and international buyers; a price-competitive option for formulators outside Europe.
- PMC Isochem (France) — Offers API with European-centric regulatory filings (CEP/COS, JDMF) and a portfolio attractive to companies prioritising continental compliance.
- Emcure, Micro Labs, Maiden Group (India) — Integrated manufacturers with formulation and commercial capabilities; positioned to convert API supply into branded and generic finished products, often with regional commercial networks.
- CF Pharma, PRG Pharma, Guangzhou Green Cross — Listed suppliers and regional producers that represent capacity diversity and incremental supply options.
- Taj Pharma (India) — Notable for finished-dose formulations in both injection and tablet forms, representing downstream commercialization and immediate market presence.
Strategic takeaways:
- Buyers and OEMs should prioritise dual-sourcing and supplier qualification protocols to mitigate concentration risk.
- Manufacturers with regulatory dossiers covering multiple jurisdictions hold disproportionate negotiating power; securing or partnering for these dossiers accelerates market entry.
- Filers with access to differentiated formulations or IP (patents, proprietary delivery systems) can defend premium pricing and create barriers to generic substitution.
What the report contains — practical, transaction-ready intelligence
Designed for immediate commercial and corporate-development use, the report combines quantitative forecasting with pragmatic tools executives need for 2026 actions. Highlights include:
- Market sizing and forecast models (2020–2032) with scenario analyses and sensitivity testing across price, volume and regulatory outcomes.
- Supply chain and capacity maps: validated list of API manufacturers, regulatory filing coverage (EDMF/ASMF, CEP/COS, JDMF) and capacity indicators, with supplier scorecards covering quality, compliance and commercial terms.
- Regulatory and reimbursement matrix: jurisdiction-level filing status, likely dossier gaps, and payer positioning intelligence to inform market access strategies.
- Clinical and evidence synthesis: trial-by-trial evidence tables, meta-analytic summaries (including analgesic and opioid-sparing endpoints), and implications for label expansion and guideline adoption.
- Commercial playbooks: go-to-market blueprints for branded entrants, generics players and API suppliers, including pricing benchmarks, margin models and tender-play templates.
- M&A and partnership candidate shortlist: valuation frameworks and compatibility matrices for buyers seeking bolt-on assets or upstream integration.
- Risk heatmaps and mitigation templates covering supply disruption, regulatory changes and competitive pricing shocks.
While this press summary outlines the instruments in our toolkit, the report contains the underlying granular segmentation, region-by-region projections and supplier-level intelligence that supports executable deals and market strategies.
Strategic playbook for 2026 — recommended actions by stakeholder
- API suppliers: Invest selectively in regulatory filings (CEP/COS, JDMF) to expand addressable markets; pursue commercial partnerships with downstream formulators to stabilise demand.
- Generic manufacturers / formulators: Lock in multi-year supply agreements and pursue modest formulation differentiation (e.g., injection delivery systems or modified-release tablets) to avoid pure commoditisation.
- Innovator / specialty players: Advance payer-focused evidence generation that pairs the opioid-sparing narrative with pharmacoeconomic models; leverage IP to negotiate premium positions in perioperative formularies.
- Private equity and corporate development: Target consolidation of complementary API capacity and dossier portfolios to capture scale and filing coverage; use scenario models from the report to value optionality related to trial readouts and reimbursement shifts.
- Payers and hospital systems: Sponsor pragmatic comparative-effectiveness studies linked to stewardship programmes; consider conditional contracting that rewards opioid-sparing outcomes.
How executives should use this research in 2026
Use the report as a decision-support engine across four immediate priorities:
- Prioritise supplier qualification and enter multi-year contracts where exposure to concentrated supply is material to production continuity.
- Align evidence-generation investments (post-authorisation trials, real-world studies) with formulary uptake targets and payor requirements specific to priority markets.
- Screen potential M&A targets using our supplier scorecards and concentration data to fast-track integration of dossier-strong assets.
- Run scenario stress tests (included in the report) to understand the financial impact of positive or negative clinical readouts, changes to national formulary positions, and new entrants.
Conclusion — why now
The nefopam hydrochloride market is no longer a static generic niche. Incremental clinical evidence, formulation IP and concentrated supply create both commercial risk and opportunity. For 2026, organisations that combine disciplined supply security, targeted regulatory filings, payer-centred evidence and selective deal-making will capture disproportionate value as the market continues its modest but steady growth at an estimated 5.5% CAGR. PW Consulting’s full report provides the granular segmentations, supplier-level analytics and transactional playbooks required to convert this forecasted growth into profitable, de-risked strategies.
Next steps
PW Consulting has prepared an executive briefing package and client workshops to translate findings into a 90-day action plan. To access the full dataset, supplier scorecards, and scenario models referenced here (including the region and application-level detail intentionally excluded from this summary), please visit our report page or contact your PW Consulting account director for immediate access and a tailored briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Nefopam Hydrochloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com