

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide GMP Protein (E. coli) Contract Manufacturing Market to Expand from USD 1,585.4 Million in 2025 to USD 3,396.75 Million by 2032 at an 11.45% CAGR

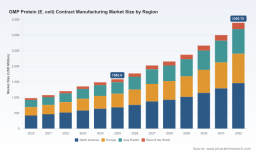
Worldwide GMP Protein (E. coli) Contract Manufacturing Market — Strategic Preview for 2026 Decision-Makers
As biomanufacturing leaders recalibrate supply chains and product roadmaps for the post‑pandemic era, understanding the trajectory of GMP contract manufacturing for E. coli‑expressed proteins is essential. PW Consulting’s latest market research — anchored on a 2025 base, a historical window that spans 2020–2025, and a forecast horizon covering 2026–2032 — shows clear, actionable signals for commercial planners, R&D chiefs, and corporate development teams. The market in focus reached USD 1,585.4 Million in 2025 and is projected to grow to USD 3,396.75 Million by 2032, representing a compounded annual growth rate (CAGR) of 11.45% through the forecast period. This growth, and the structural forces behind it, should shape capital allocation and outsourcing strategies into 2026 and beyond.
Worldwide GMP Protein (E. coli) Contract Manufacturing Market
Why the E. coli GMP protein CDMO market matters in 2026
-
Cost and speed advantages. E. coli platforms continue to offer a compelling combination of rapid strain development, high volumetric productivity and relatively lean facility footprints compared with mammalian systems. These attributes make microbial manufacturing the default choice for certain therapeutic classes and many research‑to‑clinic programs where time and cost are primary constraints.
Worldwide GMP Protein (E. coli) Contract Manufacturing Market -
Expanding product set. The market expansion is driven by a diverse set of protein classes — from enzymes and cytokines to antibody fragments and recombinant vaccines — creating a multi‑modal demand profile that CDMOs must service with flexible process toolboxes and regulatory readiness.
Worldwide GMP Protein (E. coli) Contract Manufacturing Market -
Regulatory tightening raises quality and analytics stakes. Recent guidance from regulators emphasizes enhanced characterization and control of host cell proteins (HCP) and residual host DNA in E. coli‑derived products. Expect increased demand for orthogonal assays, platform‑specific HCP panels (per USP <1132> and FDA guidance), and deeper lot‑release analytics to meet FDA, EMA and ICH expectations.
-
Mid‑market consolidation and capability densification. The market’s competitive footprint shows material share concentration across leading global CDMOs, while a broad mid‑tier of specialist providers continues to compete on niche capabilities such as ultra‑low endotoxin processing, inclusion body refolding, or pDNA co‑manufacturing. This structure creates optionality for buyers but also raises M&A interest among scale players seeking capability filling and geographic reach.
What PW Consulting’s report delivers — practical content that matters to executives
-
Strategic playbook: decision frameworks that translate market growth signals and regulatory changes into operational moves (e.g., when to insource versus partner, and the minimum analytics footprint required for clinical versus commercial programs).
-
Provider scorecards: a repeatable vendor evaluation template that weights technical capabilities, regulatory track record, capacity elasticity, and commercial terms — ready to deploy for RFP shortlisting and supplier risk assessments.
-
Techno‑economic models: build‑to‑buy calculators and scenario analyses that quantify the cost and timeline implications of key choices (fermentation scale, DSP approach, endotoxin and HCP control strategies) without exposing confidential client inputs.
-
Regulatory checklists and analytical roadmaps: a set of step‑by‑step controls and recommended orthogonal assay suites to meet USP/ICH/EMA expectations for E. coli‑derived products.
-
Capacity and supply maps: an interactive view of global GMP capacity trends and strategic hubs (note: detailed regional and application splits are available in the full report).
-
M&A and partnership playbook: criteria for bolt‑on acquisitions, co‑development partnerships, and licensing agreements that accelerate pDNA/ protein co‑manufacturing or secure platform technologies.
Competitive landscape — reading the vendor map in 2026
The vendor landscape is multifaceted: global scale players, specialty microbial CDMOs, and regional mid‑market providers each play distinct roles in the value chain. Our analysis of leading providers identifies three strategic positioning archetypes that buyers should consider when selecting partners.
-
Global integrators with breadth: Firms such as Lonza and AGC Biologics offer integrated service suites and global footprint advantages — useful for sponsors seeking single‑partner solutions spanning development through commercial supply. These providers often win on risk reduction, regulatory history, and the ability to absorb scale‑up complexity across sites.
-
Technology specialists: Companies like Wacker Biotech and MicroProtein Technologies (MPT) differentiate on proprietary secretion or refolding platforms and on expertise with challenging inclusion body projects. Sponsors with molecules that require unusual downstream processing or specialized refolding strategies should prioritize such specialists early in candidate selection.
-
Regional and niche providers: A cohort including Bionova Scientific, HIPRA Biotech Services, 53Biologics, Elise Biopharma, Richter BioLogics, Biovian (3PBIOVIAN), List Labs and Xpress Biologics (Polyplus/Sartorius) combine regulatory compliance with cost‑competitive, agile services. Strategic actions among these providers — for example, Bionova’s recent licensing partnership for high‑efficiency pDNA production (Feb 2026) and HIPRA’s expanded E. coli capability set (Jan 2025) — indicate continued specialization and selective capability buildouts.
Notably, the market exhibits moderate concentration: the top three providers account for a material share of spend while the top five capture just over half of the market. That structure favours both risk‑averse consolidation plays by large sponsors and opportunistic growth for skilled mid‑tier CDMOs that can demonstrate regulatory compliance and technical differentiation.
Regulatory and operational imperatives that will shape sourcing decisions
-
Analytics infrastructure is non‑negotiable. The combination of FDA guidance on HCP characterization, ICH Q6B expectations and EMA practice means sponsors and CDMOs must invest in orthogonal assay capability and platform‑specific HCP panels during late preclinical and early clinical stages.
-
Process robustness reduces lifecycle costs. Investments in host cell engineering, secretion systems, and refolding technologies lower downstream burden and reduce lot failures; the return on investment is particularly clear where commercial demand and high yields drive volume economics.
-
Workforce and quality systems are enduring differentiators. Large‑scale E. coli manufacturing requires highly trained personnel and mature QMS to pass regulatory scrutiny; these are harder to build than cleanroom capacity and are often the gating factor in vendor selection.
-
Dual sourcing and geographic flexibility mitigate geopolitical and supply risks. Given the pace of market growth and localized regulatory enforcement, having a primary and a qualified secondary CDMO — ideally in complementary regulatory jurisdictions — is prudent for late‑stage programs.
Actionable recommendations for 2026
-
Prioritize analytics before scale. Build or partner for orthogonal HCP and residual DNA testing early in late discovery to avoid costly process rework.
-
Match vendor archetype to program risk. Use global integrators for complex, global launches; choose specialists for technically demanding molecules; leverage regional players for cost‑sensitive, early‑phase projects that require agility.
-
Negotiate flexibility into CDMO contracts. Include options for scale steps, capacity hold, and technology transfer timelines to adapt as programs progress to pivotal and commercial stages.
-
Invest in platform technologies selectively. For sponsors with pipeline breadth in enzyme, cytokine, or antibody fragment spaces, platform investments in secretion or refolding technologies can yield multi‑product upside.
-
Model capacity at scenario level. Use forward scenarios tied to the market’s expected growth to 2032 (from USD 1,585.4 Million in 2025 to USD 3,396.75 Million in 2032 at an 11.45% CAGR) to decide timing and scale of CAPEX or partner commitments.
How PW Consulting supports executive decisions
We translate market data into executable plans. Our engagements commonly include: bespoke vendor diligence and scorecards; CAPEX/OPEX and cost‑of‑goods modeling for build versus buy; regulatory readiness audits with prioritized remediation roadmaps; and M&A advisory focused on capability fills and geographic expansion. For sponsors considering partnership or capacity investments in 2026, PW Consulting provides hands‑on support from RFP through tech transfer.
This preview intentionally highlights strategic trends and the practical content of our analysis while withholding granular segment‑level tables and vendor share breakdowns that are part of the full report. Those detailed splits and downloadable templates are available on the PW Consulting report page for organizations that require the complete dataset and reproducible models to inform procurement, manufacturing and M&A decisions.
For detailed analysis of this topic, please visit the official page: Worldwide GMP Protein (E. coli) Contract Manufacturing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com