

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Floating Production Storage and Offloading (FPSO) Equipment Market to Grow from USD 12,850.4 Million in 2025 to USD 21,098.31 Million by 2032 at a 7.34% CAGR
By pmarketresearch, 2026-07-15
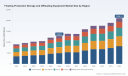
Worldwide Floating Production, Storage and Offloading (FPSO/FPSO-Equipment) Market — Strategic Outlook for 2026
Executive snapshot
PW Consulting’s latest market study on Worldwide Floating Production, Storage and Offloading Equipment offers a practitioner-focused strategic playbook for energy executives, project sponsors, investors, and supply‑chain leaders planning decisions in 2026. The market has expanded materially from the start of the decade: after recovering from pandemic-era disruptions, global equipment revenues surpass USD 12.8 billion in our 2025 base year and are modeled to exceed USD 21.1 billion by 2032 under our base scenario. Between 2026 and 2032 the sector grows at a compound annual growth rate (CAGR) of 7.34%, a pace driven by newbuild activity, lease-and-operate contracting trends, and accelerated investment in deepwater basins.
Worldwide Floating Production Storage and Offloading Equipment Market
Why this report matters for 2026 decision cycles
-
Timing and capital allocation: the market inflection captured in our models shows a near-term surge in sanctioning and long-lead ordering across multiple project corridors. For CFOs and programme directors, understanding the shape and timing of equipment demand materially affects hedging strategies, yard slot allocations, and working-capital planning.
Worldwide Floating Production Storage and Offloading Equipment Market -
Contracting strategy: lease-and-operate commercial structures are now the default for a majority of awards, materially changing risk distribution between operators and service providers. Our analysis quantifies the operating-lease premium against traditional CAPEX models and provides decision matrices that guide whether to pursue owner-operated or chartered structures in 2026 negotiations.
Worldwide Floating Production Storage and Offloading Equipment Market -
Supplier and yard engagement: the market’s moderate concentration — with the top-three players accounting for a substantial share of market activity and a top-five cluster controlling a majority of project awards — underscores the importance of early engagement with dominant hull integrators, turret suppliers and major shipyards. Our vendor risk heatmaps and capacity trackers are built to inform binding procurement windows.
-
Decarbonization and technical risk: major operators and charterers are specifying all‑electric topsides and emissions‑reduction features for pre-salt and other high‑profile programs. Our report translates these technical requirements into procurement checklists, incremental cost drivers, and likely impacts on lead times and lifecycle OPEX.
What is inside — practical deliverables for 2026 planning
The study was constructed as an operational toolkit, not just a desk study. Key deliverables included with the report are:
-
Market sizing and scenario models: base-year calibration for 2025, plus three sector scenarios (base, downside, upside) through 2032. Each scenario includes topline revenue trajectories, short- and long-lead procurement calendars, and stress-tested CAPEX/OPEX sensitivities that reflect oil-price and supply-chain shocks.
-
Project pipeline intelligence: a curated and scored project pipeline informed by primary interviews, public FIDs, AIS/port analytics, and proprietary backlog tracking. Projects are scored for sanction probability, timing risk, and local-content exposure to fuel prioritization of sales and resourcing plans.
-
Contract and commercial playbooks: negotiation templates and term comparators for lease-and-operate, build-operate-transfer (BOT), and full EPCI engagements. These playbooks include clauses tied to local-content obligations and decarbonization requirements so legal and commercial teams can expedite contract close in 2026.
-
Supply-chain and yard capacity maps: a heatmap of global fabrication and conversion capability, long-lead equipment suppliers, and a two-year slot forecast by major yard. These are coupled with vendor scorecards that quantify technical fit, delivery reliability, and counterparty credit risk.
-
Investment decision tools: NPV templates, unit-cost models, and break-even band analyses calibrated to current commodity prices and regulatory cost adders. These tools help sponsors translate market signals into sanction-ready business cases under differing contract structures and fuel-price assumptions.
-
Risk registries and mitigations: project-level and portfolio-level risk matrices covering commodity volatility, local-content compliance, regulatory change, and supply-chain bottlenecks — each mapped to practical mitigations and insurance/guarantee instruments.
Competitive landscape — who matters and why
The ecosystem remains a mixture of integrated FPSO players, specialist turret and topside suppliers, major shipyards and national champions. Our analysis focuses on the operators and contractors that shape award dynamics and execution risk:
-
Integrated FPSO providers (e.g., established lease-and-operate specialists) continue to secure a large share of new awards through standardized hull concepts and flexible commercial models. Their scale, backlog and financing structures make them natural partners for sponsors seeking to de-risk schedule and commissioning.
-
EPCI contractors and system integrators remain critical for topsides and subsea integration. Their ability to coordinate complex interfaces and manage long-lead procurement is a differentiator on technically demanding projects.
-
Shipyards and heavy fabrication centres drive schedule risk: capacity allocation decisions at shipyards can become the binding constraint for multibillion-dollar programmes. Early slot booking and definitive contracting are therefore strategic levers we recommend pursuing in 2026.
-
Operators and national oil companies are both customers and strategic partners: changing operator procurement preferences, such as a move towards decarbonized production concepts, alter technical specifications and therefore supplier selection and cost curves.
Our report examines these players across capability, balance-sheet strength, and portfolio fit — and provides playbooks for forming joint ventures, alliance agreements, or competitive sourcing strategies.
Recent developments and immediate implications
-
Sanction and award momentum: a wave of project activity in 2025–2026 has shifted vendors’ and yards’ forward loadings. We discuss cases where recent FIDs and contract awards have already triggered supply-chain reallocation, and we quantify the knock‑on lead‑time impacts for long‑lead equipment procurement.
-
Local content and cost inflation: region-specific local-content rules continue to increase headline project budgets in places like Brazil, typically adding double-digit percentage pressure while supporting substantial local employment. Our guidance shows how sponsors can structure vendor partnerships to balance compliance with cost control.
-
Commodity and macro pressures: elevated oil prices and episodic supply disruptions have improved project economics across many offshore plays, shortening payback timelines and increasing sanction probability for borderline projects — but they also raise input-cost volatility that must be managed through contractual protections and procurement staging.
-
Commercial model shift: our primary research confirms a significant shift toward lease-and-operate structures in recent years. This alters credit exposure, insurance requirements, and lifecycle revenue streams, all of which are covered in our comparative commercial simulations.
Strategic recommendations for 2026
-
Lock long-lead orders now if you are sanctioning in 2026–2027. The market’s growth trajectory means lead‑times will continue to be a primary schedule risk; delaying orders is materially more expensive than accelerating procurement under most scenarios.
-
Favor flexible contracting that aligns incentives across the hull, topsides and mooring supply chain. Hybrid contracts that allocate performance risk while preserving operator optionality on commissioning timing will be a competitive advantage.
-
Build a local-content execution plan as an early deliverable to control cost creep. Our templates demonstrate how to convert regulatory obligations into staged local-supply commitments rather than front-loaded budget inflators.
-
Embed decarbonization requirements into technical design early. Specifying all‑electric or low‑emissions technologies late in engineering drives scope creep and rework costs.
-
Stress-test sanction cases against oil-price scenarios and supply-chain outages. Use the report’s scenario models to set internal hurdle rates and contingency reserves that reflect both upside and downside volatility.
Market structure and concentration — implications for competition
The industry exhibits moderate-to-high concentration: the three largest participants account for a meaningful share of market activity, and the top five together capture a majority. This concentration affects negotiating leverage, financing terms for charterers and lessees, and the availability of yard slots for new entrants. We provide playbooks for smaller vendors and new entrants on how to win carve‑out work through niche technical differentiation, strategic alliances, or financing partnerships.
How to use the full report
This briefing demonstrates the depth and orientation of PW Consulting’s deliverable without exposing the underlying granular segmentation or proprietary figures that deliver commercial advantage. Subscribers to the full Worldwide FPSO Equipment Market report receive the complete datasets, downloadable scenario models, vendor scorecards, contract templates and a live project-tracker that updates as FIDs and awards are announced. The full package is designed to be deployed immediately in procurement, investment committees, and front-end engineering decisions.
Final word from PW Consulting
As companies align their 2026 capital and contracting plans, the difference between value capture and value erosion will be determined by foresight in procurement timing, contract structure and supply‑chain orchestration. Our 2026-oriented toolkit transforms market noise into decisive, actionable steps: it tells you when to press, when to hedge, and when to partner. For teams preparing sanction-ready packages and board approvals this year, the report is a practical roadmap — and the dataset behind it is the operational edge.
For detailed analysis of this topic, please visit the official page: Worldwide Floating Production Storage and Offloading Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Smart Carry-on Bags Market to Rise from USD 1,450.0 Million in 2025 to USD 3,501.03 Million by 2032 at a 13.42% CAGR (2026–2032) — GPS/Bluetooth & Online E‑commerce Lead
By pmarketresearch, 2026-07-15
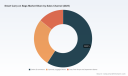
Worldwide Smart Carry-on Bags Market: Strategic Outlook for 2026
As travel rebounds and consumer expectations converge around convenience, connectivity, and safety, the smart carry-on bag market has quietly transitioned from niche novelty to strategic category. PW Consulting’s latest market study — the Worldwide Smart Carry-on Bags Market Report (base year 2025, forecast 2026–2032) — equips executives with the forward-looking, operationally actionable intelligence they need to make high-consequence decisions in 2026 and beyond.
Worldwide Smart Carry-on Bags Market
Why 2026 Is an Inflection Point
Our analysis shows that market momentum has accelerated sharply over the past five years, with global industry revenue moving from a sub‑billion niche in 2020 to approximately USD 1,450 Million in 2025. The near‑term outlook is robust: the market is forecast to expand further in 2026 and grow at a compound annual growth rate (CAGR) of 13.42% through our 2032 horizon, where total revenues approach the USD 3.5 billion mark. These macro dynamics create a narrow window for market-shaping moves — product roadmaps, channel restructuring, regulatory compliance investments, and M&A activity — that will determine market leadership for the remainder of the decade.
Worldwide Smart Carry-on Bags Market
What Matters Strategically for 2026
- Regulatory compliance is now a competitive prerequisite: 2026 introduced more restrictive dangerous-goods guidance from aviation authorities regarding lithium batteries. IATA and major regulators require removable batteries for checked luggage acceptance, and several carriers have tightened policies on non‑removable batteries for carry‑on units. These changes raise design and certification stakes: product teams must prioritize removable power modules, documented safety testing, and transparent labeling to mitigate go‑to‑market friction.
- Battery architecture will determine accessibility: The industry’s winners will be those who marry modular battery systems with retail-friendly installation and robust documentation. Airlines’ evolving policies (including outright bans by some carriers on non‑removable cells) make immutable battery design choices risky from both compliance and distribution standpoints.
- Feature sets are maturing — value lies in orchestration, not novelty: Consumers expect basic smart features (location tracking, charging, digital weighing, secure locking) as table stakes. The next value layer is seamless interoperability (app ecosystems, OTA firmware updates, data privacy) and proven reliability across multiple travel scenarios.
- Distribution is bifurcating: Direct‑to‑consumer brands that master online storytelling and lifetime service ecosystems will compete alongside legacy brands that leverage wholesale, airport, and specialty retail footprints. Channel strategy must therefore be tailored: premium, service‑led SKUs for DTC; certified, airline‑friendly SKUs for travel retail and duty‑free.
What the Report Delivers (Practical, Executable)
- Top‑line market sizing and a detailed seven‑year forecast calibrated to 2025 base metrics — enabling revenue and capex planning for 2026.
- Scenario models that stress‑test product and channel choices against regulatory shock events (battery rule tightening, airline prohibitions).
- Go‑to‑market playbooks for incumbents and new entrants — SKU rationalization, channel roll‑out timing, pricing ladders, and service models.
- Competitive benchmarking and capability matrices that identify feature gaps, margin levers, and partnership opportunities.
- Supplier maps and component‑level risk assessments for critical subassemblies (battery systems, tracking modules, and locks), plus suggested supplier diversification strategies.
- M&A and partnership scouting: target archetypes, valuation heuristics, and integration checklists for acquiring technology enablers (GPS/IoT platforms, battery management firms, mobile app developers).
- Retail and after‑sales strategies, including warranty policies, battery replacement programs, and airport service models to reduce friction at the point of travel.
- Regulatory and certification playbook: a checklist for product compliance across leading aviation jurisdictions and recommendations for third‑party test houses to accelerate approvals.
Competitive Landscape: Who’s Shaping the Category
The smart carry-on arena is structurally moderate in concentration: our CR3 and CR5 metrics show that the three largest firms account for under half of market sales, and the top five approach roughly half. This distribution implies meaningful opportunity for nimble challengers while underscoring the defensive advantages of incumbents with scale, brand resonance, and multi‑channel footprints.
Worldwide Smart Carry-on Bags Market
- Samsonite International S.A. (Luxembourg) — A large, diversified incumbent that leverages deep retail reach and multiple smart SKUs offering weighing, biometric locking, trackers, and integrated charging. Samsonite’s scale allows it to invest in cross‑channel service programs and certification throughput, making it a default partner for travel retailers seeking airline‑compliant options.
- Away Travel Inc. (United States) — A DTC native that built a premium brand around thoughtfully engineered baggage. Away’s strengths are product storytelling, customer lifecycle marketing, and modularity in features — a useful case study for conversion of online brand equity into service subscriptions.
- TUMI (United States), Rimowa (Germany), Delsey (France) — Premium legacy brands that differentiate on materials, design pedigree, and business traveler features. Their strategic challenge is balancing premium pricing with the added cost and logistics of compliant battery systems.
- Travelpro, Heys, Horizn Studios, Samsara, Arlo Skye, Samsara Luggage — A mix of specialized and growth-oriented players that compete on innovation (rideable designs, app‑native alerts, proprietary aluminum shells). These firms are acquisition and partnership targets for larger brands wanting to accelerate feature roadmaps.
- Airwheel Holding Ltd. (China) — Represents an adjacent mobility play, blending rideable capabilities with luggage functions; illustrates diversification paths that combine personal mobility and baggage.
Recent industry events — from trade show surges in new product launches to editorial testing and consumer reviews — confirm that product velocity remains high. However, new product velocity must be synchronized with certification cycles and airline policy updates to avoid commercial setbacks.
Where to Place 2026 Bets: Tactical Recommendations
- Prioritize removable, serviceable battery systems: Re‑engineer legacy integrated power packs into modular solutions that enable airline compliance and simplify aftermarket battery swaps. This reduces channel friction and expands addressable distribution.
- Invest in OTA and platform interoperability: A robust firmware and app strategy that supports remote lock updates, geofencing, and secure data handling will be a differentiator as consumers expect continuous improvement post‑purchase.
- Design for distribution diversity: Create SKU families aligned to channel needs — airline‑compliant cores for travel retail and premium feature bundles for DTC buyers — with harmonized service commitments to protect brand trust.
- Establish rapid certification lanes: Pre‑approved component suppliers, preferred testing houses, and proactive regulatory engagement reduce time-to-shelf and are material competitive advantages in a tightened regulatory environment.
- Consider bolt‑on acquisitions for capability acceleration: Target small GPS/IoT platform providers, battery management specialists, or app studios to compress time to market for integrated features.
Risk Matrix for 2026 Planning
- Regulatory risk: Sudden tightening of lithium battery rules can strand inventory and invalidate channel agreements; mitigation requires adaptable battery architectures and inventory contingency plans.
- Channel risk: A misaligned SKU strategy that ignores airline rules or retail compliance can lead to product delistings and costly recalls.
- Technology risk: Proprietary tracking systems without open standards may face consumer resistance; adopt hybrid architectures that preserve IP but support interoperability.
- Reputation risk: Battery incidents, even isolated, disproportionately harm companies in this category; invest in transparent safety programs and extended warranties to build consumer trust.
Conclusion — The Strategic Value of the Report for 2026 Decisions
For C‑suite executives, product leaders, and corporate development teams, PW Consulting’s report is designed as a decision‑support dossier: it pairs a rigorously validated market sizing baseline (USD 1,450 Million in 2025 with a 13.42% CAGR into our forecast window) with granular playbooks and scenario models that translate market dynamics into executable actions. Whether your objective is to defend share, accelerate innovation, pursue M&A, or redesign channel economics, the intelligence in this study materially shortens the learning curve and lowers execution risk.
We deliberately present this briefing as a strategic “trailer”: the report highlights what matters and why, while the proprietary segmentation matrices, supplier scorecards, and transaction‑level valuations are maintained behind our research portal. PW Consulting clients and decision‑makers seeking the full data assets, downloadable models, and bespoke workshop engagements for 2026 planning should contact our industry team or visit the PW Consulting reports page to request access.
For detailed analysis of this topic, please visit the official page: Worldwide Smart Carry-on Bags Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Drawer-Type Switchgear Cabinets Market Poised for 6.0% CAGR Through 2032
By pmarketresearch, 2026-07-15
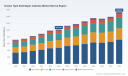
Drawer Type Switchgear Cabinets Market: A 2026 Strategic Briefing for C-Suite Decision Makers
Executive snapshot
The global drawer type switchgear cabinets market is entering 2026 from a position of steady expansion and increasing strategic complexity. Our PW Consulting benchmark shows the market surpassing the one‑billion USD threshold in the base year (2025), rising to an anticipated 1.13 billion USD in 2026, and tracking to roughly 1.53 billion USD by 2032 on a 6.0% compound annual growth rate (forecast period 2026–2032). Market concentration is moderate: the largest three players account for just under 40% of the market while the top five capture roughly 53%, underscoring both global leadership and remaining room for regional or niche challengers.
Drawer Type Switchgear Cabinets Market
Why this briefing matters for 2026 decisions
- Translate macro momentum into executable plans: With predictable growth at a mid-single-digit CAGR and accelerating opportunities in data center, industrial modernization and critical power distribution, 2026 is a pivotal planning year to convert strategic intent into capacity, product and go‑to‑market moves.
- Manage margin pressure while investing for differentiation: Raw material volatility and trade policy shifts are compressing margins at OEMs. Firms that can re‑engineer cost structures and monetize higher‑value features (safety, digital telemetry, rapid serviceability) will widen competitive gaps.
- Prioritize capital allocation with optionality: Facility expansions, automation, and software-enabled product upgrades carry different lead times and return profiles. Scenario planning now reduces exposure to execution risk over the 2026–2032 horizon.
Market dynamics shaping 2026 strategy
Three structural dynamics will define the near term:
Drawer Type Switchgear Cabinets Market
- Demand composition is shifting toward modular, withdrawable drawer architectures that enable faster maintenance, safer operations and higher service revenues. Buyers increasingly favor systems that support both traditional distribution and emerging critical loads such as AI data centers.
- Input cost and policy volatility. Copper and electrical steel cost swings and targeted tariffs are elevating procurement and product‑cost risk. Organizations that implement robust raw‑material hedging, local sourcing strategies and product redesigns to reduce material intensity will protect margin.
- Consolidation and capability play. The market’s concentration metrics reflect a dual reality: established global players control a material share, yet regional OEMs and specialists retain tactical advantages in local channels and cost positions. Expect targeted M&A, JV activity and capacity plays in 2026 as incumbents shore up service footprints and niche technology stacks.
Competitive landscape: What industry leaders are doing
Our analysis of leading suppliers shows clear, differentiated strategic postures that buyers and investors should factor into their 2026 planning.
Drawer Type Switchgear Cabinets Market
- ABB (Zurich) — Platform scale and vertical integration: ABB’s investment in a major European manufacturing facility and its continued push to pair modular drawer systems with advanced breakers and digital protection positions it to capture high‑specification demand (notably AI‑ready data centers and large industrial users). Expect ABB to compete on system integrability, digital services and scale economics.
- Siemens AG (Munich) — Systems & services bundling: Siemens continues to emphasize turnkey distribution systems and lifecycle services. Their strength is in integrating switchgear into broader electrification and automation projects, which favors clients seeking single‑vendor accountability for complex installations.
- Schneider Electric (Rueil‑Malmaison) — End‑to‑end energy management: Schneider blends modular drawer‑type hardware with energy management software and service programs, enabling premium pricing for bundled lifecycle outcomes, especially in commercial and critical power applications.
- Eaton Corporation (Dublin) — Safety and power‑handling innovation: Eaton’s product innovations (e.g., rotating contact mechanisms and arc‑flash mitigation) aim to differentiate on safety, uptime and high current ratings—attributes that command warranty and service premium margins.
- Regional and specialist OEMs — China‑based suppliers and smaller global players continue to hold relevance by offering competitive pricing, rapid local delivery and customization. These vendors are often preferred for volume and retrofit work where cost and lead time are decisive.
Recent industry moves and what they imply
- Capacity investments by global incumbents signal an expectation of premium, specification‑driven demand growth (e.g., investments supporting AI‑ready data centers). For executives, this raises the bar on product development—if you want to compete at that level, your R&D and certification roadmaps must be fully funded in 2026.
- Product launches focused on higher amperage ratings, reduced arc flash risk and increased modularity indicate an ongoing migration up the value chain. Feature parity is reducing, so differentiation will come from integration of safety, digital telemetry, and proven field reliability.
- Regional OEMs’ continued strength underscores the need for layered go‑to‑market strategies—global OEMs will push platform standardization while regional players win on channel intimacy and cost agility.
Supply chain and cost pressures you cannot ignore
Raw material and trade developments are immediate tactical considerations for 2026:
- Copper and grain‑oriented electrical steel price volatility is materially impacting BOM costs and can reduce OEM margins if not mitigated. Procurement strategies must now include longer‑term contracts, formula pricing, and material‑substitution roadmaps where technically feasible.
- Protectionist trade measures and tariffs introduce localized cost differentials and may justify near‑market production or tariff‑aware sourcing. Scenario planning should evaluate the ROI of regionalizing capacity versus accepting tariff exposure.
- Supply chain resilience investments—dual sourcing, safety stock optimization, digitized supplier scorecards—deliver disproportionate value in a market characterized by intermittent commodity shocks and lead‑time variability.
Strategic imperatives for executives in 2026
Based on our scenario modelling and client advisory engagements, PW Consulting recommends five priority actions:
- Rebalance portfolio toward modular, serviceable, higher‑margin configurations. Where feasible, accelerate certifications and interoperability capabilities demanded by hyperscalers and large industrial OEMs.
- Lock in cost and supply through creative procurement: multi‑year offtake agreements, regional supplier partnerships, and design for material efficiency to offset copper/steel pressure.
- Invest selectively in factory modernization and digital test capabilities that shorten product time‑to‑market and reduce warranty exposure—especially if you target the upper end of the market spectrum.
- Use M&A and strategic partnerships to close capability gaps (digital protection, arc‑flash mitigation, aftermarket field services) rather than building all capabilities organically.
- Formalize a 2026 commercial playbook that differentiates on lifecycle economics, not just upfront hardware cost—warranty programs, performance SLAs and remote diagnostics are rapidly becoming differentiators.
What the PW Consulting report delivers (practical content)
Our full Drawer Type Switchgear Cabinets Market report is built as an operational toolkit for 2026 decision cycles. Key deliverables include:
- A validated market model with historical (2020–2025) and forecast (2026–2032) revenue series, scenario toggles and sensitivity levers that allow you to stress test assumptions across commodity, tariff and demand scenarios.
- A detailed competitive map with capability matrices, go‑to‑market archetypes and supplier scorecards to guide sourcing and partnership decisions.
- Actionable strategic playbooks: product development roadmaps, CapEx prioritization frameworks, M&A screens, and commercial pricing strategies tailored to different customer verticals and risk appetites.
- Operational templates: SKU rationalization tools, factory modernization ROI calculators, and a two‑year implementation schedule for supply chain resilience measures.
- Risk registers and mitigation playbooks covering raw‑material exposure, regulatory shocks and channel disruption—designed for board‑level oversight and auditability.
What we intentionally withheld — and why
To preserve the report’s role as the definitive source for executable detail, we have deliberately not published the granular regional and application revenue splits or the full proprietary company-level revenue breakdowns in this briefing. Those detailed segment tables, competitor revenue lines and downloadable financial models are available in the full report and are essential for transaction diligence, detailed pricing strategy and localized capacity planning.
How to use the report in your 2026 planning cycle
- CEOs & Boards — Use the scenario model to stress test strategy choices (build vs. buy; regionalize vs. centralize). Set funding thresholds for capability development and M&A screening informed by the model’s ROI outputs.
- COOs & Supply Chain — Implement procurement and sourcing playbooks immediately; use our supplier scorecards to reprioritize suppliers and restructure contracts before commodity shocks escalate.
- Product & Engineering — Prioritize modularity, safety and digital telemetry in the 2026 roadmap; leverage the report’s feature‑value matrices to optimize BOM redesign and certification sequencing.
- Commercial & Service — Reframe go‑to‑market offers around lifecycle value. Pilot bundled service agreements with selected accounts to validate pricing and operational readiness.
Final perspective
The drawer type switchgear cabinets market in 2026 presents both a continuity of steady, predictable growth and a set of accelerating strategic inflection points—material cost pressure, demand for higher‑value modular systems, and a competitive field split between global platforms and nimble regional specialists. Firms that treat 2026 as a year to reallocate capital, shore up supply resilience, and invest in differentiated product‑service propositions will enter the 2026–2032 window with optionality and defensibility.
For the exhaustive segment datasets, competitor revenue breakdowns, downloadable financial models, and a customized briefing for your management team, consult the full PW Consulting Drawer Type Switchgear Cabinets Market report on our website.
For detailed analysis of this topic, please visit the official page: Drawer Type Switchgear Cabinets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: HDH Titanium Powder Market to Rise from USD 524.5 Million in 2025 to USD 853.3 Million by 2032 at a 7.2% CAGR
By pmarketresearch, 2026-07-15
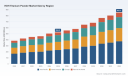
HDH Titanium Powder Market: Strategic Imperatives for 2026 — PW Consulting Insights
Executive snapshot
PW Consulting’s HDH Titanium Powder Market report (base year 2025) delivers a focused, actionable view of a market that has transitioned from niche feedstock supply to a strategic industrial commodity. Our modelling shows the global HDH titanium powder market reached approximately USD 524.5 Million in 2025 and — under a set of consensus demand and supply assumptions — is projected to grow at a compound annual growth rate (CAGR) of 7.2% through the 2026–2032 forecast period, reaching roughly USD 853.3 Million by 2032. The report couples a granular view of dynamics with transaction-grade tools to inform 2026 capital allocation, procurement, and M&A choices.
HDH Titanium Powder Market
Why this matters for 2026 decision-makers
- Supply security is now strategic: HDH titanium powder remains feedstock-dependent, with production ultimately tied to titanium sponge availability and the hydrogenation–dehydrogenation (HDH) processing route. Policy and geopolitical shifts in sponge-producing regions elevate the value of resilient sourcing strategies.
- Cost–performance trade-offs are reshaping choices: HDH powders offer a cost-competitive alternative to spherical gas-atomized powders for many powder metallurgy, metal injection molding, and thermal spray applications. Procurement teams must weigh powder morphology, downstream processing costs, and end-use specification risks — not only headline price per kilogram.
- Regulatory and standards risk is non-trivial for critical end-markets: Medical and aerospace buyers face strict standards (e.g., ISO 23301 and relevant ASTM specifications). Certification and traceability are decisive contract terms in 2026.
- Market structure enables targeted plays: Concentration metrics show a moderately concentrated supplier market (CR3 ≈ 42.5%, CR5 ≈ 58.3%), which creates room for both incumbent scale plays and focused niche entrants to capture differentiated margins.
What the PW Consulting HDH Titanium Powder Market report contains
- Comprehensive market sizing and forecast (2020–2032): Historical reconciliation, driver-based forecasts, scenario workstreams, and sensitivity modelling to inform 2026 budgeting and capital plans.
- Methodology and data pack: Transparent assumptions, source laddering, confidence bands, and an Excel model for custom scenario analysis and integration into client financial models.
- Value-chain mapping and cost stack analysis: From sponge procurement through hydrogenation, crushing, dehydrogenation, sieving, and post-processing, with unit-cost drivers and break-even maps for vertical integration decisions.
- Pricing deck and benchmark comparators: Market price ranges by grade and particle size, comparative economics versus gas-atomized powders, and margin waterfall for typical producers and consumers.
- Demand-by-application playbooks: End-market demand drivers (aerospace, medical implants, additive manufacturing, powder metallurgy, coatings), use-case risk matrices, and adoption curves — with executable commercial tactics for suppliers and buyers.
- Supplier intelligence and competitive mapping: Transaction-ready profiles for incumbent producers, capacity maps, capability heatmaps, and a M&A watchlist.
- Regulatory, geopolitical and raw-material risk assessment: Scenario-based impact analysis of export controls, tariffs, and domestic content rules on sourcing and pricing.
- Commercial diligence toolkit: Supplier scorecards, sampling and testing checklists (oxygen/hydrogen content, PSD, morphology), contract templates, and quality audit playbooks tailored to 2026 procurement cycles.
Note: the report intentionally aggregates sensitive subsegment tables and supplier capacity schedules behind our data room. This executive briefing highlights key insights while directing practitioners to the full dataset for transaction-level decisions.
HDH Titanium Powder Market
Competitive landscape — what to watch in 2026
The HDH market is shaped by diversified players: legacy refiners and sponge integrators in East Asia; specialized powder manufacturers in North America and Europe; and high-volume producers from China that serve global industrial chains. Strategic moves in 2025–2026 underscore several themes:
HDH Titanium Powder Market
- Vertical integration and consolidation: Recent corporates actions — including a share exchange that will bring a major Japanese HDH producer into a larger metals group effective mid-2026 — illustrate a push toward upstream control of feedstock and enhanced product portfolios. Expect further consolidation in response to supply-security imperatives.
- Long-term offtakes and aerospace tie-ups: Expanded long-term agreements between titanium material suppliers and major OEMs reinforce how aerospace demand secures higher-value, certified flows of powder and sheet. These contracts raise the hurdle for new entrants seeking aerospace approvals.
- Quality and certification as market access gates: Suppliers that secure aerospace and medical certifications, and demonstrate low-impurity control, are capturing premium segments. Independent quality credentials are becoming determinative in supplier selection.
- Chinese producers remain pivotal: Large producers based in China continue to supply significant volume to global markets, offering broad PSD options and competitive pricing. Buyers must balance short-term cost advantages versus medium-term geopolitical and regulatory risk.
- Specialized Western suppliers: Select firms in North America and Europe focus on higher-spec alloys and engineered powders tailored to medical implants and additive manufacturing, positioning themselves on quality and service rather than commodity pricing.
Supply-chain risks and mitigation playbook for 2026
- Feedstock concentration: Titanium sponge production concentration makes feedstock strategies (dual-sourcing, local inventory pools, backward integration) essential. Commodity hedging alone is insufficient given non fungible specifications and certification requirements.
- Quality drift: Control of oxygen and hydrogen content is paramount for medical and aerospace. Buyers should establish inline testing, third-party validation, and contractual acceptance criteria tied to lot-based traceability.
- Geopolitical contingencies: Prepare scenario playbooks for export restrictions, tariffs, and domestic content mandates. Scenarios should include time-to-fill windows, alternate routing, and contractor substitution playbooks.
- Commercial levers: Structured, multi-year offtake agreements with performance-based pricing, capacity reservation clauses, and ramp schedules protect OEMs while providing revenue visibility to producers making capital investments.
Commercial implications & go-to-market strategies
- For suppliers: Prioritize certified product lines (medical/aerospace), augment quality management systems, and consider small-scale atomization or surface modification services to capture higher-value AM markets. Geographic diversification of customers mitigates concentration risk.
- For buyers: Rebalance procurement from lowest-cost spot buys to strategic blends of contracted volumes plus validated spot sourcing. Invest in incoming inspection capabilities and create supplier development programs to align material specifications with in-house processing constraints.
- For investors and M&A teams: Focus on targets with defensible certifications, proven low-impurity processes, and flexible particle-size distribution capabilities. The mid-market remains ripe for bolt-on plays that extend value chains into pre-alloying, blending, or downstream finishing.
How to use this report in 2026 planning
- Integrate our forecast scenarios directly into capex and inventory modelling to quantify upside and downside from feedstock disruptions.
- Use the supplier scorecards and audit templates to re-run procurement RFIs and shorten supplier qualification lead times.
- Employ our price decks and cost stacks to stress-test supplier bids and structure multi-year contracts with indexed pricing and quality KPIs.
- Apply the M&A screening checklist to prioritize acquisition targets that deliver immediate capability upgrades (certifications, specialty alloys, PSD flexibility).
Access and next steps
PW Consulting’s HDH Titanium Powder Market report is designed as an operational decision tool for 2026. It combines a validated macro forecast with drill-down analytics, supplier intelligence, and executable playbooks. For access to the full dataset — including detailed segmentation tables, supplier capacity schedules, price decks, and the interactive Excel model — please visit our report page or contact PW Consulting’s industry team to arrange a briefing and data-room access. The executive briefing above provides the strategic framing; the licensed report supplies the transaction-ready detail you will need to act this year.
For detailed analysis of this topic, please visit the official page: HDH Titanium Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide RF Chip Inductors Market Valued at USD 1,794.54 Million in 2025, Set to Grow at a 7.5% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide RF Chip Inductors Market: Strategic Imperatives for 2026
Executive summary
As RF front-ends and mixed-signal architectures proliferate across telecom, automotive, industrial IoT and consumer devices, the global RF chip inductors market is entering a sustained growth phase. Our latest PW Consulting market study — with a 2025 base year and a 2026–2032 forecast horizon — quantifies a clear expansion trajectory underpinned by a 7.5% compound annual growth rate (CAGR). By 2025 the addressable market reached roughly USD 1.8 billion (million-USD units), and our scenario base case anticipates a near-USD 3.0 billion market by 2032. For executives planning product roadmaps, procurement strategies, and M&A activity in 2026, the implications are immediate: growth is real, but margin and supply risks are asymmetric across product families, geographies and vendor capabilities.
Worldwide RF Chip Inductors Market
Why this report matters for 2026 decision-making
- Actionable forecasts: Our historical baseline (2020–2025) combined with seven-year forward projections give leadership teams a defensible demand curve to underpin capital allocation, capacity planning and inventory strategies.
- Decision-focused diagnostics: Instead of broad market narration, the report provides profit-impact analysis, supplier risk heatmaps, and go-to-market checklists that convert market growth into executable plans for 2026.
- Stress-tested scenarios: We model shocks that matter in 2026 — raw-material price spikes, ferrite-core supply disruptions, regulatory tightening — and translate each into P&L, lead-time and NPI (new product introduction) outcomes.
Market outlook — the big picture (no spoilers)
The RF chip inductors market’s mid-decade momentum is driven by concurrent secular themes: 5G densification, in-vehicle connectivity and radar, edge compute in industrial IoT, and a refresh cycle in premium consumer wireless devices. Under our central case (7.5% CAGR), the market expands materially from the 2025 base into the 2030s, creating attractive topline opportunities for suppliers who can deliver high-frequency performance, automotive qualifications and reliable supply. Importantly, market concentration is meaningful: top-tier suppliers command a sizable share of the industry’s commercial value, setting structural barriers for newcomers while creating niche windows for focused specialists.
Worldwide RF Chip Inductors Market
What the PW Consulting report contains (practical, executable modules)
- Integrated demand model (2020–2032): Granular unit and value projections by product family and application cluster, with sensitivity levers for penetration, substitution and module-level BOM (bill-of-material) shifts.
- Supply-side intelligence: Supplier mapping, capacity overlays, lead-time matrices and supplier scorecards that quantify technical fit, volume capability, quality certifications and geopolitical exposure.
- Cost and pricing playbooks: Total cost of ownership (TCO) models, pass-through templates, and price-elasticity simulations to support commercial negotiations and index-linked contracts.
- Regulatory & materials risk toolkit: Compliance matrices for key geographies (including EU directives), and mitigation playbooks for raw-material constraints and recycling mandates.
- Competitive benchmark and product roadmaps: Comparative technical dossiers for incumbent leaders and emerging challengers, including RF performance metrics (Q, SRF), packaging trends and AEC-Q/automotive readiness indicators.
- M&A and partnership screens: Criteria and a prioritized short-list of targets, plus integration playbooks for technology tuck-ins, capacity buyouts, and distribution alliances.
- Scenario playbooks: Four rapid-response strategies aligned to mid-2026 market shocks — raw-material inflation, ferrite conduct shortage, regional demand swings, and accelerated regulatory change.
Competitive landscape — who matters and why
The industry’s structural configuration rewards both scale and technical differentiation. Leading global module and passive manufacturers retain advantages through deep process know-how, qualified automotive product lines and global distribution. A short synthesis of core competitors — and the strategic significance of their positioning — follows.
Worldwide RF Chip Inductors Market
- Murata Manufacturing Co., Ltd. — A frontrunner in multilayer and wire‑wound RF chip inductors, Murata’s high-Q product lines (including compact AEC‑Q200‑qualified devices) signal a deliberate push into automotive telematics and in-vehicle communication modules. Their mass-production capabilities and automotive certifications make them a preferred partner for OEMs seeking short lead-time, qualified sources.
- TDK Corporation — TDK’s portfolio emphasizes high-frequency optimization for consumer and communication applications. Their R&D cadence and global manufacturing footprint make them a reliable anchor for product families where high SRF and miniaturization are decisive.
- Taiyo Yuden — Known for mobile and 5G-focused multilayer inductors, Taiyo Yuden is a go-to for designers requiring constrained form factors and consistent RF performance in handset and small-form-factor modules.
- Bourns, Inc. — With recent multilayer product launches and a focus on monolithic construction for high SRF and compact footprints, Bourns exemplifies the mid-sized supplier strategy: targeted technical advances to penetrate mobile and RF frontend segments.
- Coilcraft, Vishay, Würth Elektronik and specialist US/Taiwan players — These firms collectively serve niches from high-performance microwave to military/medical-grade inductors. Their strength is vertical specialization, quality certifications, and close integration with tier‑1 system houses.
Recent product moves — including new multilayer series introductions and AEC‑Q qualified micro‑devices — underscore a shift: suppliers are racing to combine miniaturization, high-Q performance and automotive readiness. Our competitive chapters include vendor scorecards, product-matrix crosswalks and supplier negotiation levers to help buyers and strategists differentiate true competitive advantage from marketing claims.
Supply chain, raw-materials and regulatory context
Several supply-side realities will influence decision-making in 2026:
- Raw-material pressure: Metals and specialty powders used in multilayer and ferrite cores have experienced price and availability stress. These cost dynamics are already influencing supplier pricing strategies and should be incorporated into 2026 procurement contracts through indexation clauses or hedging mechanisms.
- Ferrite and high‑purity powders: Delivery cycles have lengthened for certain ferrite-based products, creating longer lead-times for specific inductive architectures. Buyers should prioritize alternative form factors or place rolling orders tied to staggered release schedules to mitigate NPI delays.
- Regulatory drive toward recyclability: European directives continue to push manufacturers toward low-toxicity and recyclable materials, impacting design-for-recycling and cost structures. Products without clear end‑of‑life strategies may face market access headwinds in key regions.
- Geopolitical material risk: Dependence on a concentrated supplier base for rare earths and ferrite precursors makes regional sourcing strategy a core resilience lever in 2026 planning.
Strategic recommendations for 2026 (priority playbook)
- Embed scenario thinking into procurement: Implement layered contracts with volume collars, indexation to key alloys and defined surge capacity options to preserve margin without overpaying under normal conditions.
- Fast-track qualification of alternate suppliers: Create a two-tier approved vendor list with clear technical gating criteria and accelerated test labs to reduce qualification time from months to weeks for critical SKUs.
- Product architecture decisions: Favor modular RF subassemblies and platform-level standardization to reduce SKU proliferation and enable last‑mile substitution if a micro‑in‑demand component becomes supply-constrained.
- Drive co-development with strategic suppliers: Negotiate shared-cost development programs for automotive-grade and high-Q devices, tying roadmap milestones to co-investment and protective offtake agreements.
- M&A and partnerships: Prioritize targets that add either automotive qualifications, capacity in low-geopolitical-risk jurisdictions, or unique RF performance (e.g., very high Q/SRF), and insist on realistic synergies indexed to integration timelines.
How PW Consulting supports your 2026 agenda
Our market report is designed as a practitioner’s toolkit: beyond charts and forecasts, it contains ready-to-use templates, negotiation decks, supplier scorecards and scenario dashboards you can deploy immediately. For boards and executive teams, we offer a condensed strategy workshop that converts the report’s insights into an actionable 90‑day plan: supplier re‑qualification, contract redesign, and targeted R&D partnerships.
Closing — the trailer invitation
We have shown the contours of growth, the structural winners, and the key risks executives must manage in 2026. To preserve the value of our primary research and model assets, this release intentionally omits detailed segment-level tables, region-by-region splits and granular vendor market-shares — data we reserve for the full report and client workshops. If your 2026 planning requires the underlying datasets, supplier-by-supplier scorecards, or bespoke scenario runs calibrated to your BOM, the full PW Consulting Worldwide RF Chip Inductors Market report and accompanying advisory services provide those deliverables.
Contact PW Consulting to schedule a briefing or to license the full report and model — equip your leadership team with the forecasts, playbooks and supplier intelligence needed to convert RF chip inductor market growth into profitable, resilient outcomes in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide RF Chip Inductors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Topical Dispenser Market Set to Expand at 6.92% CAGR as Pharmaceuticals and Skincare Drive Demand
By pmarketresearch, 2026-07-15
Worldwide Topical Dispenser Market — Strategic Implications for 2026
PW Consulting’s newest market study on the Worldwide Topical Dispenser Market provides a focused, actionable intelligence brief for senior executives planning product, commercial, and M&A strategies in 2026. The report synthesizes proprietary modelling, supplier-level diligence, regulatory mapping, and practical scenario playbooks to translate market momentum into boardroom decisions. Below we outline the high-level takeaways and the specific ways leaders should use this research to sharpen 2026 execution — while reserving the detailed segment-level tables and supplier metrics for the full report.
Worldwide Topical Dispenser Market
Executive summary: a market in predictable acceleration
The topical dispenser market has moved from a niche medical-dermal accessory arena into a strategic component of therapeutic delivery and patient experience. PW Consulting’s base-year analysis (2025) captures robust expansion from 2020–2025 and a continuation of that trajectory into our forecast window. On a macro basis, the market grows at a compound annual growth rate (CAGR) of 6.92% through our forecast period, reflecting durable demand from pharmaceutical compounding, dermatology therapeutics, and premium cosmetic and personal-care applications. Total market value rises from roughly USD 1.04 billion in 2020 to approximately USD 1.44 billion in 2025, and our model projects steady growth to a multi-billion-dollar market by the conclusion of the forecast horizon.
Worldwide Topical Dispenser Market
Why 2026 is a decision inflection point
- Commercial channel transitions accelerate. Pharmacy compounding practices, specialty dermatology clinics, and contract manufacturers are standardizing dispenser formats — creating winners for scale-focused producers and opening tactical windows for niche innovators.
- Regulatory and reimbursement clarity crystallizes. Recent device clearances and evolving Medicare guidance have materially changed adoption economics for certain topical therapies and their applicators; companies that align product design with regulatory expectations in 2026 can shorten time-to-market and raise uptake.
- Consolidation dynamics offer optionality. Market concentration is moderate: a handful of suppliers capture a meaningful share without forming a tightly closed oligopoly. In practice, this creates opportunities for both bolt-on acquisitions and premium valuations for differentiated technology owners.
- Product differentiation matters more than ever. Metered-dose accuracy, preservative protection, patient ergonomics, and scalable manufacturing are the axes on which 2026 competitive battles will be fought.
What the report delivers (practical content for 2026 planners)
PW Consulting’s report is structured to support fast, evidence-based decisions. The deliverables include:
Worldwide Topical Dispenser Market
- Overarching market sizing and a calibrated growth model with scenario sensitivity for input variables (regulation, compounding adoption rates, end-market therapeutic cycles).
- Supplier dossier pack: strategic profiles, product roadmaps, manufacturing footprints, quality certifications, and commercial strengths/weaknesses for the meaningful incumbent and challenger set.
- Regulatory & reimbursement playbook: device classification mapping, 510(k) precedents, ISO 13485 implications for outsourcing, and payer guidance that can influence product design and go-to-market timing.
- Buy-side decision tools: acquisition target screeners, technology valuation heuristics, and integration checklists for manufacturing and quality systems.
- Commercial tactics & pilots: channel segmentation frameworks, recommended clinical evaluation designs to demonstrate dose uniformity or patient preference, and pricing strategies aligned to payer dynamics.
Key market dynamics and strategic risks
- Regulatory segmentation increases product value. Recent device clearances highlight that topical applicators can be regulated pathways into therapeutic markets. Conformity to 21 CFR device classifications and adherence to ISO 13485 for design/production are preconditions for scaling into regulated therapeutic workflows.
- Clinical performance differentiates procurements. Independent evaluations have demonstrated measurable differences in dose uniformity between metered-dose mechanisms and alternative airless designs for certain formulations; suppliers that can provide robust performance data gain procurement leverage.
- Reimbursement nuances constrain some adjacencies. Not all topical agents used with dispensers qualify for surgical-dressing benefits under public payers; understanding payer categorizations affects commercial models for therapeutic versus cosmetic applications.
- Supply chain and quality systems are entry hurdles. ISO- and FDA-compliant manufacturing, validated molding and assembly, and managed supply of critical components are determinants of partner selection, especially for pharmaceutical customers.
Competitive landscape — who to watch and why
The competitive field comprises specialized device innovators, global dispensing platforms, and contract manufacturers that provide end-to-end solutions. Several companies merit attention for distinct strategic reasons:
- DoseLogix (Cordica Medical / TEAM Technologies) — A focused innovator in metered dosing applicators for compounding pharmacies. DoseLogix’s recent product introductions underscore a strategy of improving pharmacist and patient experience through device ergonomics and container-compatibility; ideal partners for compounding-centric rollouts.
- Aptar Pharma — A global dispensing platform with strong capabilities in airless and semi-solid metering systems. Aptar’s emphasis on product protection, hygiene, and validated dosing positions it well for pharmaceutical-grade collaborations and large-scale supply agreements.
- Medisca — A compounding-focused supplier bridging sterile and non-sterile preparation use-cases. Their positioning favors clinical pharmacy channels where breadth of compounding-compatible formats is a procurement criterion.
- SpecializedRx Products, Health Care Logistics (HCL), Lucas Packaging Group — These suppliers address metered-dose needs across compounding and clinical settings; they are often selected for configurable dosing solutions and service-level responsiveness.
- Porex Corporation — A components play — porous plastics and reservoir technologies — that can be a differentiation lever for drug-device designs requiring controlled flow or breathable membranes.
- Silgan Dispensing and HTI Plastics — Manufacturers with precision healthcare dispensing expertise and quality certifications. HTI’s ISO 13485 registration highlights the strategic value of certified contract manufacturing when pharmaceutical customers demand device-level controls.
Recent industry developments reinforce these dynamics: targeted product launches optimized for machine compounding workflows and regulatory clearances for adjacent topical devices demonstrate the twin forces of product innovation and formal medical-device paths shaping adoption. Firms that combine repeatable dosing performance with regulatory readiness will gain privileged access to pharmaceutical channels in 2026.
Strategic playbook for 2026
Executives should consider the following prioritized actions:
- Accelerate regulatory alignment. If your product is intended for therapeutic delivery, allocate engineering and regulatory resources in H1 2026 to map device classification and prepare predicates or design dossiers. Early alignment shortens sales cycles with institutional purchasers.
- Demonstrate performance with real-world evidence. Invest in comparative dose-uniformity trials and user-experience studies. Data wins procurement decisions with pharmacists and clinicians; a demonstrable advantage allows premium positioning.
- Lock in quality-certified manufacturing. Whether through contract manufacturing partnerships or in-house upgrades, ensuring ISO 13485-compliant processes will be a deciding factor for pharmaceutical customers and increases enterprise valuation for exit scenarios.
- Calibrate go-to-market by end-use economics. Differentiate channels (pharmacy compounding vs. dermatology clinics vs. premium cosmetics) with distinct pricing, packaging, and clinical messaging aligned to payer and buyer incentive structures.
- Be opportunistic on M&A. Use the moderate concentration environment to pursue bolt-ons that add proprietary metering mechanisms, critical component technologies, or regulatory-ready manufacturing capacity rather than broad geographic scale alone.
How to use PW Consulting’s report in 90, 180, and 365 days
- 90 days: Run a supplier gap analysis using our supplier dossiers; prioritize short-list partners for clinical validation pilots.
- 180 days: Execute a regulated pilot (or 510(k)-aligned design refinement) and initiate procurement conversations with pharmaceutical customers using our performance benchmarks as negotiation anchors.
- 365 days: Close an M&A or strategic partnership that secures manufacturing capacity or a differentiated dispensing technology, and roll out a commercial program informed by our channel-specific guidance.
What we are intentionally withholding in this summary
In keeping with PW Consulting’s “trailer” approach, this public summary surfaces strategy, risk, and supplier direction while intentionally withholding the granular segment splits, region-by-region financial tables, and the full supplier scorecards that form the core operational intelligence. These datasets are essential for transaction-level or launch planning and are provided only with the full report and accompanying data licence.
Concluding recommendation
The topical dispenser market offers a clear, data-backed growth path for strategic entrants and incumbents who can combine clinical-grade performance, regulatory preparedness, and manufacturing quality. For executives setting resource allocation in 2026, our guidance is straightforward: prioritize validated metering performance, secure quality-certified production, and use targeted M&A to acquire missing technology or capacity rather than chasing broad geographic expansion. Those moves convert the sector’s steady CAGR into defensible, near-term commercial wins.
Next steps
Executives who require the complete analytical model, supplier scorecards, and tailored M&A/partnership recommendations should request PW Consulting’s full Worldwide Topical Dispenser Market report and data package. The full report contains the segment-level breakouts, scenario tables, and deal-level diligence tools needed to operationalize the strategies summarized here.
For detailed analysis of this topic, please visit the official page: Worldwide Topical Dispenser Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Video Inspection Robot Market at USD 2,450 Million in Base Year 2025, Poised to Reach USD 4,158.6 Million by 2032 on a 7.85% CAGR
By pmarketresearch, 2026-07-15
Video Inspection Robot Market Outlook 2026: Strategic Imperatives for Decision-Makers
PW Consulting's latest market research brief on the Video Inspection Robot market presents an actionable intelligence package designed to inform high-stakes procurement, R&D prioritization, and M&A decisions in 2026. Anchored on a 2025 base year, the study projects a compound annual growth rate (CAGR) of 7.85% over the 2026–2032 forecasting window. That trajectory underscores a market expanding from roughly USD 2.45 billion in 2025 to a multi-billion-dollar opportunity by 2032 — a scale that compels incumbent vendors, infrastructure owners, and private equity to re-evaluate strategy this year.
Video Inspection Robot Market
Why the 2026 decision window is decisive
-
Acceleration of replacement and inspection demand: Aging civil infrastructure, expanding utility networks, and stricter service-level mandates are increasing the frequency and scope of visual inspections. Organizations that commit budget and technical direction in 2026 will capture the most favorable deployment timelines over the next funding cycle.
Video Inspection Robot Market -
Technology inflection: The industry is shifting from simply capturing video to delivering actionable intelligence — through AI-assisted defect recognition, sensor fusion (laser profiling + sonar + video), and autonomy for large-diameter and confined spaces. Early adopters of integrated platforms will lock in operational efficiencies and higher ASPs for service models.
Video Inspection Robot Market -
Supply-chain and regulatory headwinds: Recent trade policy inquiries and tariffs affecting camera and sensor imports, together with continued supplier-side disruptions for high-precision optical components, are increasing lead times and input costs. Firms that pre-emptively adjust sourcing or secure component inventory in 2026 will reduce project risk.
-
Commercial model evolution: Buyers are moving toward outcome-based procurement (inspection-as-a-service), creating recurring revenue opportunities but demanding stronger data platforms and lifecycle support from equipment vendors.
What the report delivers — practical, decision-ready content
The PW Consulting report is deliberately built to be operational. It combines rigorous market sizing and trend analysis with executable tools for commercial teams, product leaders, and investors. Highlights include:
-
Methodology and data foundation — transparent assumptions, primary interviews, and reconciled supply-side shipment data that justify the headline sizing and growth rate.
-
Market drivers and restraints — deep qualitative and quantitative analysis of the push-pull forces shaping adoption, from labor constraints to regulatory compliance costs.
-
Technology deep dives — comparative assessments of AI-assisted video analytics, laser profiling, sonar integration, and wireless vs. tethered architectures, with deployment suitability by use case.
-
Vendor scorecards and procurement playbooks — evaluation matrices that map vendor capabilities to buyer requirements, suggested RFP language, and negotiation levers for 2026 purchasing cycles.
-
Use-case ROI models and TCO calculators — modular templates that allow asset owners to quantify inspection-as-a-service vs. capital procurement across different pipe sizes and operating environments.
-
Scenario planning and stress tests — three alternative market trajectories that model tariff shocks, sensor supply interruptions, and an accelerated shift to autonomous inspection.
-
Deal flow and M&A themes — identification of acquisition targets (software platforms, sensor specialists, service integrators) and valuation heuristics relevant to today’s private equity appetite.
Note: This press overview highlights the report’s scope and executive tools. Detailed regional and application-level splits, plus full-year-by-year segment projections, are available only in the complete report to preserve the proprietary value of PW Consulting’s modeling.
Competitive landscape — who matters and why
The market is moderately fragmented: the top three vendors account for roughly a quarter of the market by revenue, while the top five approach close to two-fifths — a structure that leaves meaningful room for consolidation and regional champions. This concentration profile implies an active battleground for technology leadership and service expansion.
-
Envirosight LLC (Randolph, NJ, USA) — A leader in sewer and pipeline crawler systems; recent product evolution emphasizes HD video capture and AI-assisted defect recognition to speed inspection workflows.
-
Deep Trekker Inc. (Kitchener, ON, Canada) — Builds pipe crawlers and underwater ROVs focused on confined-space video inspection with modular payloads for multi-environment deployments.
-
Wuhan Easy-Sight Technology (Wuhan, China) — High-volume manufacturer of pipeline CCTV systems with capabilities optimized for long-distance and sonar-augmented inspections.
-
IBAK Helmut Hunger GmbH & Co. KG (Kiel, Germany) — Noted for modular platforms that integrate panoramic video and 3D laser profiling for high-fidelity documentation of asset condition.
-
CUES Inc. (Orlando, FL, USA) — Offers truck-mounted and crawler systems tailored to municipal sewer programs; strong service ecosystem for public-sector procurement.
-
RedZone Robotics (Pittsburgh, PA, USA) — Active in autonomous and semi-autonomous inspection for large-diameter pipelines; a focus on automation is attracting utility customers seeking scale.
-
Mini-Cam Ltd. (United Kingdom) — Specialist in compact crawlers for drains and small-diameter pipelines, emphasizing portability and fast deployment.
-
iPEK International GmbH (Germany) — Known for rugged robotic CCTV systems for detailed pipeline inspection, with strong OEM and rental channels in Europe.
-
Waygate Technologies (Baker Hughes; USA/Germany) — Supplies remote visual inspection (RVI) robotics with industrial-grade video for energy and petrochemical customers.
-
Inspector Systems (Germany) — Provider of modular video and laser inspection robots spanning a wide diameter range; positions itself on flexibility and customization.
Recent vendor moves underscore two short-term imperatives: (1) embedded analytics and AI are table stakes, and (2) certified solutions for hazardous environments are unlocking energy and offshore opportunities. Representative developments include Envirosight’s 2025 launch of an AI-assisted ROVVER X HD, IBAK’s late-2025 release of panoramic 3D profiling robots, and early-2026 deployments of explosion-proof inspection robots by major industrial players.
Strategic plays for 2026 — six recommended actions
-
Prioritize platform + software integration: Buy, partner, or build analytics platforms that turn video into defect calls and maintenance tickets. Service-led models that include SaaS analytics command higher lifetime value.
-
Hedge supply-chain risk: Establish dual-sourcing for critical optics and sensors, negotiate longer-term supply contracts in 2026, and evaluate partial localization for high-volume components to mitigate tariff exposure.
-
Certify for industrial markets: For vendors pursuing energy and petrochemical segments, ATEX/IECEx and equivalent certifications will unlock higher-margin contracts; plan certification roadmaps now.
-
Design modular roadmaps: Product leaders should architect modular robots (swap-in sensors, wireless/tether options) to broaden addressable use cases without heavy internal re-engineering.
-
Target M&A selectively: Infra owners and PE should assess acquisitions that accelerate AI analytics, add inspection services in target geographies, or secure critical sensor IP.
-
Pilot outcome-based contracts: Run controlled pilots for inspection-as-a-service with clear KPIs (inspection throughput, defect detection accuracy, cost-per-meter) to build proof cases for scale.
Risks, scenarios, and mitigation
-
Tariff and trade policy shocks: Ongoing trade measures impacting camera and sensor components can raise BOM costs. Scenario planning suggests a near-term increase in COGS and longer lead times; mitigation includes pass-through pricing and inventory buffering.
-
Sensor supply disruptions: Continued shortages for high-precision optics and MEMS sensors will favor vendors with diversified supply chains or internal sourcing agreements.
-
Standards and compliance divergence: Fragmented regional safety standards could raise go-to-market complexity. Invest in modular certification strategies and global compliance expertise.
-
Competitive consolidation: A wave of M&A is plausible as larger equipment OEMs and service firms seek to consolidate software and autonomous capabilities; buyers should prepare defensive and acquisitive playbooks.
How PW Consulting’s intelligence supports your 2026 decisions
For executive teams, the report functions as both compass and toolkit. The headline market trajectory and our 7.85% forecasted CAGR provide the macro context to allocate capital, but the true value lies in the diagnostic modules — vendor scorecards, ROI calculators, and scenario-based procurement guidance — that convert market understanding into executable steps. Whether you are a municipal utility designing a five-year inspection program, a vendor defining a product roadmap, or an investor sizing acquisition opportunities, the report reduces uncertainty and prioritizes options for 2026.
To access the full dataset, segment-level forecasts, and the complete set of practical templates (including downloadable TCO models and vendor RFP language), request PW Consulting’s complete Video Inspection Robot Market report. The full package contains the proprietary tables and segment breakdowns that underpin the strategic recommendations summarized here.
For detailed analysis of this topic, please visit the official page: Video Inspection Robot Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Thickeners and Vegetable Gums Market Set to Grow at a 5.85% CAGR, New Report Says
By pmarketresearch, 2026-07-15
Worldwide Thickeners and Vegetable Gums Market: Strategic Imperatives for 2026 Planning
PW Consulting — Executive Briefing on our 2026-Focused Market Intelligence
PW Consulting’s newest market study, Worldwide Thickeners and Vegetable Gums Market (base year 2025; forecast 2026–2032), delivers the rigorous, transaction-grade perspective that executives and investment committees need as they set strategy for 2026. The global market — measured on a USD revenue basis and tracked across 2020–2025 — has established a clear growth trajectory. Our modeling indicates a mid-single-digit compound annual growth rate (CAGR) of roughly 5.85% into the forecast horizon, with total market value expanding substantially from the 2025 base. For market participants, that growth translates into tangible choices on capacity, product mix, and go-to-market investments in the coming 12–18 months.
Worldwide Thickeners and Vegetable Gums Market
Why this report matters for 2026 decisions
- Actionable foresight for planning cycles: The study aligns market projections to typical corporate planning horizons and provides scenario-based demand curves that feed directly into CAPEX, procurement, and commercialization decisions for 2026.
- Risk and resilience lens: With raw material volatility, regulatory shifts, and geopolitical trade frictions accelerating, the analysis surfaces where supply fragilities exist and which mitigants — from dual-sourcing to vertical integration — deliver the best risk-adjusted returns.
- Commercial blueprint: Beyond high-level forecasts, PW’s deliverables include commercialization playbooks (pricing levers, formulation pathways, and customer segmentation guidance) that translate market trends into revenue-capture actions.
Data-driven context — growth, scale and structure
Our top-line modeling synthesizes historical data (2020–2025) with proprietary demand drivers and price assumptions to produce a full financial view for 2026–2032. The market in 2025 serves as the strategic reference point for budgeting and capacity planning; from there, the report projects steady expansion through 2032 under our baseline scenario. Importantly, concentration metrics reveal a market that is fragmented relative to many specialty ingredient sectors: the three- and five-firm concentration ratios (CR3 and CR5) indicate meaningful incumbent presence but also substantial opportunity for mid-sized players and new entrants to scale through targeted vertical moves or product innovation.
Worldwide Thickeners and Vegetable Gums Market
What’s inside the report — practical content for operators and investors
- Market sizing and forecast engine: A transparent modeling workbook that maps demand drivers (by application and type) to volumetric and revenue forecasts, including sensitivity analyses and alternate macro scenarios tailored for 2026 planning.
- Supply-chain and raw-material forensic: Traceable maps of feedstock origins, conversion economics, common bottlenecks, and an indexed price tracker built from primary-sourced purchase data and trade flows.
- Regulatory and standards matrix: Region-by-region regulatory intelligence, anticipated labeling trends, and decision trees that quantify the commercial impact of potential restrictions on specific gum classes.
- Competitive playbooks and M&A scorecards: Actionable diligence templates, synergy calculators, and a playbook for bolt-on versus platform M&A that can be executed under 90–180 day transaction timelines.
- Product and formulation roadmaps: Prioritized innovation pathways — including fermentation-derived gums, modified starch blends, and hybrid gum systems — with expected time-to-market, required development spend, and margin implications.
- Commercial diligence bundles: Customer willingness-to-pay studies, price elasticities by application cluster, and route-to-market effectiveness benchmarks for ingredients distributors, co-manufacturers, and end-brand customers.
- Operational risk register: Mitigation options (contractual, inventory, and sourcing), stress-test scenarios, and an implementation timeline for resilience measures aligned to 2026 procurement cycles.
Competitive landscape — players, moves and what they signal for 2026
The report’s competitive analysis profiles the leading and influential firms across starch, hydrocolloid, and vegetable gum domains. Key corporate actors, which we examine in depth, include global agribusiness and specialty-ingredient players such as Cargill, Ingredion, Tate & Lyle (and the integrated CP Kelco business), DuPont, Kerry Group, ADM, Ashland, Roquette, Jungbunzlauer, and several regional leaders. Our assessment focuses on strategic positioning — product portfolios, vertical integration, and route-to-market models — and recent strategic moves that will shape 2026 competitive dynamics.
Worldwide Thickeners and Vegetable Gums Market
- Tate & Lyle / CP Kelco integration: The consolidation completed in 2025 created a more vertically integrated hydrocolloid platform; our report quantifies the operational synergies and outlines scenarios where combined R&D and supply capabilities can compress competitor reaction windows.
- Roquette’s pharmaceutical push: A late-2025 acquisition to expand pharma excipients highlights a deliberate upstream-to-specialty focus; we assess how this trend accelerates the segmentation of thickeners into commodity versus high-value specialty streams.
- New product and fermentation-led entries: Jungbunzlauer’s launch of a high-acyl gellan variant in recent years is illustrative of an innovation vector that enables formulators to replace multi-ingredient systems with single-sourced solutions — a theme we project to become a differentiator for 2026 R&D pipelines.
- Regional & niche producers: Suppliers in India and China continue to assert cost and feedstock advantages for commodity gums. The report evaluates the economics and regulatory risk of relying on such suppliers for strategic volumes in 2026.
Market dynamics shaping 2026 strategy
Several cross-cutting dynamics emerge as particularly salient for the upcoming planning cycle:
- Raw material volatility and sourcing concentration: Feedstock markets have shown pronounced sensitivity to weather, input costs, and trade policy. For instance, traditional vegetable gum feedstocks experienced notable price movement and supply pressure in 2024–2025; PW’s sourcing scenarios quantify the cost exposure for different procurement strategies.
- Regulatory uncertainty: Certain gums remain under intensified scrutiny in multiple jurisdictions. Potential tightening of usage limits or labeling requirements creates downside demand risk for exposed formulations; our scenario work models the commercial impact and timelines for mitigation or reformulation.
- Clean-label and functionality trade-offs: End-brand priorities continue to shift toward plant-based, “short-label” ingredient lists. The premium opportunity for clean-label thickeners is real, but requires R&D investment to balance sensory and stability requirements without eroding margins.
- Geopolitics and trade policy: The 2025 trade landscape featured targeted tariff actions and exemptions that affected agricultural and ingredient flows. For 2026, companies must re-evaluate sourcing footprints, especially where single-origin exposure intersects with supply chain risk.
Strategic playbook for 2026 — prioritized recommendations
Based on the market modeling and risk analysis, PW Consulting recommends the following prioritized actions for companies planning their 2026 agenda:
- Secure strategic volumes and diversify origins: Implement a two- to three-source procurement strategy for critical gums and starches, coupled with incremental safety stock policies that are economically justified by our scenario analyses.
- Invest selectively in specialty segments: Allocate R&D and commercial resources to fermentation-derived gums and clean-label botanicals where product premium and margin expansion are achievable within a 12–24 month horizon.
- Prepare regulatory contingency plans: Develop reformulation playbooks and labeling strategies now, mapping out tolerances and substitution matrices to ensure swift response if regional regulators change limits.
- Pursue bolt-on acquisitions or partnerships that close capability gaps: Target M&A opportunities that deliver either unique functionality (e.g., a novel gelling agent) or secure upstream feedstock control. Our M&A scorecards identify the most accretive profiles for 2026 execution.
- Monetize sustainability: Demonstrate traceability and lower-carbon sourcing in customer contracts to capture pricing premium from major brand owners focused on ESG metrics.
- Digitize procurement & traceability: Deploy cloud-based supplier visibility and inventory optimization tools to convert market intelligence into first-mover procurement advantages.
What we’re intentionally withholding (and why)
True to the “trailer” principle of this release, PW Consulting is publishing a high-fidelity overview of trends, competitive moves, and strategic recommendations while intentionally withholding core granular segmentation tables and sensitive unit-cost assumptions that underpin transaction-level decisions. Those detailed datasets — including the full breakdowns by application, region, and type, plus customer-level price elasticities and the model workbook — are included in the full report and financial model available on our website. This approach preserves the value of the primary research while providing executives with a precise path to the specific intelligence they need to act in 2026.
Next steps for executives and investors
- For commercial leaders: Use the report’s reformulation playbooks and supplier scorecards to begin Q1 2026 negotiations and pilot launches.
- For procurement heads: Adopt the PW sourcing scenarios to finalize 2026 supply contracts and hedging structures before mid-year purchasing cycles.
- For corporate development teams: Leverage the M&A scorecards and synergy calculators in target screening and early diligence conversations.
PW Consulting’s Worldwide Thickeners and Vegetable Gums Market study is designed to be a decision-ready tool for 2026. If your 2026 plan hinges on supply resilience, margin protection, or targeted growth in specialty thickeners, this report converts market complexity into a prioritized, executable roadmap. For access to the full dataset, modeling workbook, and proprietary appendices, visit our report page to obtain the complete intelligence package and book a briefing with our senior industry analysts.
For detailed analysis of this topic, please visit the official page: Worldwide Thickeners and Vegetable Gums Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com