

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
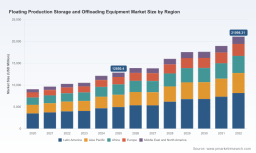
PW Consulting: Worldwide Floating Production Storage and Offloading (FPSO) Equipment Market to Grow from USD 12,850.4 Million in 2025 to USD 21,098.31 Million by 2032 at a 7.34% CAGR

Worldwide Floating Production, Storage and Offloading (FPSO/FPSO-Equipment) Market — Strategic Outlook for 2026
Executive snapshot
PW Consulting’s latest market study on Worldwide Floating Production, Storage and Offloading Equipment offers a practitioner-focused strategic playbook for energy executives, project sponsors, investors, and supply‑chain leaders planning decisions in 2026. The market has expanded materially from the start of the decade: after recovering from pandemic-era disruptions, global equipment revenues surpass USD 12.8 billion in our 2025 base year and are modeled to exceed USD 21.1 billion by 2032 under our base scenario. Between 2026 and 2032 the sector grows at a compound annual growth rate (CAGR) of 7.34%, a pace driven by newbuild activity, lease-and-operate contracting trends, and accelerated investment in deepwater basins.
Worldwide Floating Production Storage and Offloading Equipment Market
Why this report matters for 2026 decision cycles
-
Timing and capital allocation: the market inflection captured in our models shows a near-term surge in sanctioning and long-lead ordering across multiple project corridors. For CFOs and programme directors, understanding the shape and timing of equipment demand materially affects hedging strategies, yard slot allocations, and working-capital planning.
Worldwide Floating Production Storage and Offloading Equipment Market -
Contracting strategy: lease-and-operate commercial structures are now the default for a majority of awards, materially changing risk distribution between operators and service providers. Our analysis quantifies the operating-lease premium against traditional CAPEX models and provides decision matrices that guide whether to pursue owner-operated or chartered structures in 2026 negotiations.
Worldwide Floating Production Storage and Offloading Equipment Market -
Supplier and yard engagement: the market’s moderate concentration — with the top-three players accounting for a substantial share of market activity and a top-five cluster controlling a majority of project awards — underscores the importance of early engagement with dominant hull integrators, turret suppliers and major shipyards. Our vendor risk heatmaps and capacity trackers are built to inform binding procurement windows.
-
Decarbonization and technical risk: major operators and charterers are specifying all‑electric topsides and emissions‑reduction features for pre-salt and other high‑profile programs. Our report translates these technical requirements into procurement checklists, incremental cost drivers, and likely impacts on lead times and lifecycle OPEX.
What is inside — practical deliverables for 2026 planning
The study was constructed as an operational toolkit, not just a desk study. Key deliverables included with the report are:
-
Market sizing and scenario models: base-year calibration for 2025, plus three sector scenarios (base, downside, upside) through 2032. Each scenario includes topline revenue trajectories, short- and long-lead procurement calendars, and stress-tested CAPEX/OPEX sensitivities that reflect oil-price and supply-chain shocks.
-
Project pipeline intelligence: a curated and scored project pipeline informed by primary interviews, public FIDs, AIS/port analytics, and proprietary backlog tracking. Projects are scored for sanction probability, timing risk, and local-content exposure to fuel prioritization of sales and resourcing plans.
-
Contract and commercial playbooks: negotiation templates and term comparators for lease-and-operate, build-operate-transfer (BOT), and full EPCI engagements. These playbooks include clauses tied to local-content obligations and decarbonization requirements so legal and commercial teams can expedite contract close in 2026.
-
Supply-chain and yard capacity maps: a heatmap of global fabrication and conversion capability, long-lead equipment suppliers, and a two-year slot forecast by major yard. These are coupled with vendor scorecards that quantify technical fit, delivery reliability, and counterparty credit risk.
-
Investment decision tools: NPV templates, unit-cost models, and break-even band analyses calibrated to current commodity prices and regulatory cost adders. These tools help sponsors translate market signals into sanction-ready business cases under differing contract structures and fuel-price assumptions.
-
Risk registries and mitigations: project-level and portfolio-level risk matrices covering commodity volatility, local-content compliance, regulatory change, and supply-chain bottlenecks — each mapped to practical mitigations and insurance/guarantee instruments.
Competitive landscape — who matters and why
The ecosystem remains a mixture of integrated FPSO players, specialist turret and topside suppliers, major shipyards and national champions. Our analysis focuses on the operators and contractors that shape award dynamics and execution risk:
-
Integrated FPSO providers (e.g., established lease-and-operate specialists) continue to secure a large share of new awards through standardized hull concepts and flexible commercial models. Their scale, backlog and financing structures make them natural partners for sponsors seeking to de-risk schedule and commissioning.
-
EPCI contractors and system integrators remain critical for topsides and subsea integration. Their ability to coordinate complex interfaces and manage long-lead procurement is a differentiator on technically demanding projects.
-
Shipyards and heavy fabrication centres drive schedule risk: capacity allocation decisions at shipyards can become the binding constraint for multibillion-dollar programmes. Early slot booking and definitive contracting are therefore strategic levers we recommend pursuing in 2026.
-
Operators and national oil companies are both customers and strategic partners: changing operator procurement preferences, such as a move towards decarbonized production concepts, alter technical specifications and therefore supplier selection and cost curves.
Our report examines these players across capability, balance-sheet strength, and portfolio fit — and provides playbooks for forming joint ventures, alliance agreements, or competitive sourcing strategies.
Recent developments and immediate implications
-
Sanction and award momentum: a wave of project activity in 2025–2026 has shifted vendors’ and yards’ forward loadings. We discuss cases where recent FIDs and contract awards have already triggered supply-chain reallocation, and we quantify the knock‑on lead‑time impacts for long‑lead equipment procurement.
-
Local content and cost inflation: region-specific local-content rules continue to increase headline project budgets in places like Brazil, typically adding double-digit percentage pressure while supporting substantial local employment. Our guidance shows how sponsors can structure vendor partnerships to balance compliance with cost control.
-
Commodity and macro pressures: elevated oil prices and episodic supply disruptions have improved project economics across many offshore plays, shortening payback timelines and increasing sanction probability for borderline projects — but they also raise input-cost volatility that must be managed through contractual protections and procurement staging.
-
Commercial model shift: our primary research confirms a significant shift toward lease-and-operate structures in recent years. This alters credit exposure, insurance requirements, and lifecycle revenue streams, all of which are covered in our comparative commercial simulations.
Strategic recommendations for 2026
-
Lock long-lead orders now if you are sanctioning in 2026–2027. The market’s growth trajectory means lead‑times will continue to be a primary schedule risk; delaying orders is materially more expensive than accelerating procurement under most scenarios.
-
Favor flexible contracting that aligns incentives across the hull, topsides and mooring supply chain. Hybrid contracts that allocate performance risk while preserving operator optionality on commissioning timing will be a competitive advantage.
-
Build a local-content execution plan as an early deliverable to control cost creep. Our templates demonstrate how to convert regulatory obligations into staged local-supply commitments rather than front-loaded budget inflators.
-
Embed decarbonization requirements into technical design early. Specifying all‑electric or low‑emissions technologies late in engineering drives scope creep and rework costs.
-
Stress-test sanction cases against oil-price scenarios and supply-chain outages. Use the report’s scenario models to set internal hurdle rates and contingency reserves that reflect both upside and downside volatility.
Market structure and concentration — implications for competition
The industry exhibits moderate-to-high concentration: the three largest participants account for a meaningful share of market activity, and the top five together capture a majority. This concentration affects negotiating leverage, financing terms for charterers and lessees, and the availability of yard slots for new entrants. We provide playbooks for smaller vendors and new entrants on how to win carve‑out work through niche technical differentiation, strategic alliances, or financing partnerships.
How to use the full report
This briefing demonstrates the depth and orientation of PW Consulting’s deliverable without exposing the underlying granular segmentation or proprietary figures that deliver commercial advantage. Subscribers to the full Worldwide FPSO Equipment Market report receive the complete datasets, downloadable scenario models, vendor scorecards, contract templates and a live project-tracker that updates as FIDs and awards are announced. The full package is designed to be deployed immediately in procurement, investment committees, and front-end engineering decisions.
Final word from PW Consulting
As companies align their 2026 capital and contracting plans, the difference between value capture and value erosion will be determined by foresight in procurement timing, contract structure and supply‑chain orchestration. Our 2026-oriented toolkit transforms market noise into decisive, actionable steps: it tells you when to press, when to hedge, and when to partner. For teams preparing sanction-ready packages and board approvals this year, the report is a practical roadmap — and the dataset behind it is the operational edge.
For detailed analysis of this topic, please visit the official page: Worldwide Floating Production Storage and Offloading Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com