

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Bromoacetic Acid Market Poised for 4.4% CAGR as Asia‑Pacific Emerges as Dominant Market
By pmarketresearch, 2026-07-15
PW Consulting Strategic Brief — Worldwide Bromoacetic Acid Market Outlook: What 2026 Decisions Need to Know
Executive summary
PW Consulting’s newest market intelligence note on the Worldwide Bromoacetic Acid market synthesizes historical performance, 2026–2032 projections, regulatory shifts, feedstock dynamics, and supplier positioning into a single operational playbook for executives. Built on a 2025 base year with historical tracking from 2020–2025 and bottom‑up scenario modeling through 2032, the study concludes that the market is on a steady expansion path with a compound annual growth rate (CAGR) of 4.4% for the forecast period. In monetary terms, total industry revenue crossed the USD 176.5 Million mark in 2025 and is forecast to grow to approximately USD 187.0 Million in 2026, continuing toward mid‑to‑late‑hundreds by the early 2030s under the central scenario.
Worldwide Bromoacetic Acid Market
Why 2026 is a strategic inflection point
-
Regulatory momentum and transport reclassification in 2025–2026 are reshaping compliance costs and go‑to‑market timelines for intermediates and formulations that use bromoacetic acid.
Worldwide Bromoacetic Acid Market -
Upstream feedstock volatility — most notably in acetic acid pricing — is introducing fresh margin stress and creating arbitrage opportunities for agile producers and buyers.
Worldwide Bromoacetic Acid Market -
Market concentration is meaningful: the top three and top five suppliers capture a material share of the market, signaling both the benefits of scale and the potential for consolidation plays.
Market trajectory and what the numbers mean for strategy
Our base‑case forecast, anchored to the 2025 base year, shows a durable market expansion consistent with mid‑single‑digit CAGR dynamics (4.4% through 2032). This is driven by steady demand in pharmaceutical intermediates, agrochemical synthesis and selected specialty chemical applications. For corporate strategists, the headline takeaways are straightforward: volume growth exists, but margin resilience depends on three controllable levers — feedstock cost management, regulatory preparedness, and differentiated product positioning (e.g., reagent/technical vs. pharmaceutical grades).
Key dynamics shaping 2026 decisions
-
Regulation and compliance: The European Commission’s Implementing Decision in early 2025 extended approval timelines for certain biocidal uses — a short‑term relief for some market participants, but the inclusion of bromoacetic acid esters in the 2025 REACH Restricted Substances List creates medium‑term reformulation and substitution pressure in select end markets.
-
Transport & logistics: Bromoacetic acid’s hazardous goods classification (UN 3425, Class 8, Packing Group II) introduces higher logistics costs and handling protocols for cross‑border shipments. Procurement and operations teams must revalidate carrier approvals and insurance arrangements ahead of volume commitments.
-
Feedstock exposure: Acetic acid price swings are now a leading margin driver. For example, Northeast Asia acetic acid prices spiked to roughly USD 0.58/kg in April 2026 (a significant recent increase), while other regions show divergent trajectories. Buyers and integrated producers must implement pass‑through mechanisms or hedging strategies earlier in contract cycles.
Commercial implications — procurement, production, and product strategy
-
Procurement playbook: Shift from annual spot negotiations to dynamic sourcing frameworks. Incorporate formula‑based contracts tied to acetic acid indices and a two‑tier supplier portfolio — primary long‑term partners for continuity plus a set of opportunistic secondary suppliers to capture regional arbitrage.
-
Operational playbook: Rationalize inventory buffers to balance higher transport/handling costs against supply interruption risk. Evaluate tolling and contract manufacturing arrangements in lower‑cost geographies, but prioritize suppliers that can demonstrate compliance with hazardous goods protocols and REACH registration where relevant.
-
Product playbook: Invest selectively in grade differentiation. Producers with dual capability across technical and pharmaceutical/reagent grades command pricing premiums and access to higher‑margin niches — but that requires investment in quality systems and traceability.
Competitive landscape: practical reading of supplier positioning
The market combines a set of specialized reagent suppliers from mature markets with high‑volume exporters and bulk producers primarily located in cost‑competitive manufacturing hubs. PW Consulting’s assessment of named players yields tactical insights for sourcing, alliances, and M&A screening:
-
Vandana Chem (India) — A volume‑oriented manufacturer and exporter. Strengths: cost competitiveness, export infrastructure. Strategic implication: attractive as a secondary supplier for volume needs and flexible order sizes; less differentiated on reagent grade credentials.
-
Central Drug House (CDH) (India) — ISO‑certified producer serving both lab and industrial organic synthesis markets. Strengths: certification pedigree and established pharma supply channels. Strategic implication: suitable partner for companies requiring documented quality systems without the premium of global reagent brands.
-
Tokyo Chemical Industry (TCI) (Japan) — Global supplier focused on high‑purity reagent grades and distribution reach. Strengths: brand trust for R&D and pharma intermediates. Strategic implication: preferred for accredited research and development supply chains; premium pricing justified by reliability and documentation.
-
Merck KGaA / Sigma‑Aldrich (Germany) and Thermo Fisher Scientific / Alfa Aesar (United States) — Global reagent brands with extensive regulatory and compliance capabilities. Strengths: quality, global logistics, regulatory support. Strategic implication: default suppliers for regulated R&D and critical intermediate applications; selected for risk‑averse buyers despite higher cost.
-
Chemical Bull, Manasa Life Sciences, Ottokemi, Simson Pharma (India) and Nanjing Baijingyu (China) — Regional producers and bulk suppliers with varied specialization. Strengths: scale and regional responsiveness. Strategic implication: candidates for spot volumes, regional distribution, and cost optimization; require due diligence on compliance, batch traceability and transport readiness.
Risk matrix and scenario planning for 2026
The report includes an actionable risk matrix tailored to three near‑term scenarios: (1) Accelerated regulatory tightness, (2) Persistent feedstock inflation, and (3) Supply consolidation via M&A. For 2026 decisions, we advise companies to stress‑test P&L models against a feedstock shock of similar magnitude to the recent acetic acid swings, and to model incremental logistics cost on top of price volatility. In combination, these risks can compress margins even when top‑line volumes grow at the forecast CAGR.
What PW Consulting’s report delivers (and why you need the full study)
The publicly available summary highlights strategic directions. The full report — built for corporate decision‑makers — provides:
-
Proprietary demand forecasts (2026–2032) with scenario bands and sensitivity to raw material indices.
-
Supplier scorecards covering compliance credentials, product grade breadth, cost position, and logistics readiness — enabling rapid shortlist creation for sourcing tenders.
-
Regulatory impact matrices mapping REACH, EU biocidal decisions, and transport classification to practical timelines, remediation costs, and product substitution risks.
-
Commercial negotiation templates and price‑indexation clauses tailored to acetic acid volatility and hazardous‑goods logistics surcharges.
-
M&A and partnership screening framework identifying the most attractive targets by strategic fit (technology, quality systems, market access), and modeled synergies under multiple integration assumptions.
Consistent with our “trailer” principle, this brief demonstrates analytic depth while intentionally withholding detailed segment‑by‑segment shares and granular pricing tables that are included in the full study. Those core segmentation outputs are the strategic assets companies rely on to reconfigure sourcing footprints and to bid confidently in procurement cycles.
Immediate strategic actions for executives (90‑day playbook)
-
Initiate a rapid supplier due‑diligence sweep focused on hazardous goods compliance and REACH status; prioritize dual‑sourcing agreements where single‑source exposure exists.
-
Lock in a procurement indexation approach with major suppliers to align price pass‑throughs to acetic acid movements; negotiate caps and collars to limit downside risk.
-
Conduct a product portfolio review to identify SKUs that will be most affected by ester restrictions and transport classification changes; accelerate reformulation plans where required.
-
Explore strategic partnerships and minority investments in regional producers with logistics strength to secure capacity for medium‑term demand growth.
Conclusion — how PW Consulting supports your 2026 agenda
For companies that source, produce, or use bromoacetic acid in regulated specialty chains, 2026 is the year to convert market visibility into defensive and offensive moves: shore up compliance, redesign procurement contracts to insulate against feedstock shocks, and pursue targeted partnerships that secure access to differentiated grades. PW Consulting’s full report equips leadership teams with the quantitative forecasts, supplier assessments and contractual templates required to execute those moves decisively. For access to the complete dataset, segment tables, supplier scorecards and actionable modeling tools, please consult the full Worldwide Bromoacetic Acid Market report on our website.
For detailed analysis of this topic, please visit the official page: Worldwide Bromoacetic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rack‑mounted Full Liquid CDU Market Poised for a 9.85% CAGR — A New Era in Data Center Cooling
By pmarketresearch, 2026-07-15
Rack-mounted Full Liquid CDU Market: Strategic Imperatives for 2026 Decision‑Makers
As hyperscale cloud operators, colocation providers and high‑performance compute (HPC) adopters accelerate the shift to direct liquid cooling, rack‑mounted Coolant Distribution Units (CDUs) have moved from niche enablers to foundational infrastructure. PW Consulting’s latest market study — the Rack‑mounted Full Liquid CDU Market Report (base year 2025, forecast 2026–2032) — synthesizes five years of historical data and a forward model that forecasts sustained double‑digit expansion in installed base value. The market reached USD 105.0 Million in 2025 and, under our central scenario, expands to USD 203.45 Million by 2032, representing a compound annual growth rate (CAGR) of 9.85% across the 2026–2032 forecast window.
Rack-mounted Full Liquid CDU Market
Why this report matters for 2026 strategy
-
Timing matters: 2026 is the inflection year for many operators who committed to liquid cooling pilots through 2023–2025. The window for locking in preferred CDU architectures, supplier relationships and thermal‑electrical co‑design practices is now.
Rack-mounted Full Liquid CDU Market -
Investment trade‑offs are complex: the report quantifies the tradeoffs between centralized plant scaling and rack‑level distribution, and translates thermal performance into realistic CAPEX/OPEX scenarios for next‑generation AI and HPC deployments.
Rack-mounted Full Liquid CDU Market -
Risk and compliance vectors are intensifying: updated ASHRAE guidance and testing addenda, together with supply‑chain dynamics from global refrigerant policies, will reframe procurement and service contracts.
Market trajectory and what the numbers mean
PW Consulting’s modeling integrates vendor shipment data, validated field deployments and component cost trends to produce an annualized view of market value and growth. The market climbed from a measured base in 2020 through rapid adoption during 2021–2024, culminating in USD 105.0 Million in 2025. Our forecast indicates a continuation of that trend, more than doubling market value by 2032 under the central growth scenario (CAGR 9.85% for 2026–2032).
For technology buyers this translates into three operational realities: first, a growing aftermarket and service economy for CDU maintenance and spare‑parts; second, accelerating innovation around modular, hot‑swap, and high‑temperature water systems that alter site PUE and water‑side integration; and third, a maturing procurement market where buyers can leverage competitive supplier tiers for risk mitigation and lifecycle cost optimization.
Competitive landscape: established OEMs and fast movers
The rack‑mounted CDU ecosystem is characterized by a mix of specialized thermal OEMs, legacy power & thermal suppliers, and turn‑key systems integrators. Our vendor analysis highlights capabilities and strategic positioning across the supplier set:
-
CoolIT Systems (Calgary, Canada) — deep in‑rack liquid‑to‑liquid expertise with compact CHx series solutions tuned for high‑density HPC and AI racks.
-
Super Micro Computer / Supermicro (San Jose, USA) — integrates redundant, hot‑swappable pump architectures into in‑rack and in‑row CDUs, focusing on high‑availability AI and HPC installations.
-
DCX Liquid Cooling Systems (Warsaw, Poland) — pursues a compact, high‑capacity 4U form factor aimed at dense AI deployments.
-
LiquidStack (Carrollton, USA) — targets ultra‑high capacity and narrow approach temperature use cases with thin‑gap direct‑to‑chip strategies and elevated water temperatures.
-
Flex (via JetCool, Austin, USA) — recently launched a modular rack‑level CDU platform designed to scale across multi‑hundred‑kilowatt to megawatt‑class racks, signaling a systems integrator play into GPU‑dense deployments.
-
Motivair (Schneider Electric, Lancaster, USA) — leveraging Schneider’s channel and service footprint with scalable in‑rack to floor variants for AI factory use cases.
-
Asetek (Denmark, global operations) — provides warm‑water InRack CDU solutions optimized for energy efficiency and simplified plumbing.
-
nVent (Minneapolis, USA) — focuses on reliability and chilled‑coolant delivery systems for high‑uptime environments.
-
Dell Technologies (Round Rock, USA) — brings OEM server/CDU integration with a rack‑mount CDU for dense AI and HPC racks, leveraging installed base relationships with enterprise buyers.
-
Eaton (Dublin/US operations) — positions CDU capability as part of broader thermal and power management portfolios for data center OEM customers.
Competitive dynamics are shifting quickly. Recent product activity — including Flex’s modular JetCool launch (Sept 2025), Motivair’s MCDU‑70 scaled offering (Jan 2026), and Dell’s continued promotion of higher‑capacity rack CDUs — underscores a race for both feature differentiation and scale economics. PW Consulting’s vendor matrices in the full report evaluate these suppliers across technology fit, integration risk, serviceability, and TCO impact to help procurement teams prioritize pilots and rollouts.
Consolidation and concentration: market power matters
The market exhibits moderate concentration by value: the three largest vendors account for a significant share of the market’s commercial value, and the top five participants establish a clear second tier. This structure creates both negotiating leverage for large buyers and a bifurcated channel where specialist integrators and OEMs compete on service depth versus scale. Our competitiveness heatmaps and procurement playbook help buyers navigate preferred‑supplier selection while preserving optionality for future architecture shifts.
Standards, regulation and supply‑chain shocks
-
Standards: ASHRAE Technical Committee updates — notably the inclusion of liquid‑to‑liquid CDU test methods in Standard 127 and guidance from ASHRAE TC 9.9 on isolating facility water from technology cooling loops — are raising the bar for performance certification and installation practice. Compliance will increasingly be table stakes in enterprise RFPs.
-
Regulatory and materials pressure: global refrigerant phase‑down measures (Kigali Amendment) and related certification requirements are increasing production and compliance costs across thermal components. Suppliers with diversified coolant strategies and robust materials sourcing will be advantaged.
-
Operational risk: as liquid cooling moves deeper into mission‑critical stacks, failure modes, service SLAs and spare parts logistics become material to availability. The full report quantifies downtime dollar exposures and models maintenance contract structures suitable for different risk appetites.
Report practicalities: what’s inside and how it helps buyers in 2026
PW Consulting’s study is designed as a practical director‑level toolkit rather than a purely descriptive market brief. Key deliverables inside the report include:
-
Market sizing and scenario models — transparent inputs and sensitivity analysis for CAPEX/OPEX tradeoffs across 2026–2032.
-
Vendor scorecards — comparative evaluation of technical fit, integration risk, service footprint, and supplier financial resilience.
-
Deployment playbooks — step‑by‑step checklists for pilot planning, site plumbing & mechanical integration, commissioning and lifecycle maintenance.
-
TCO and ROI tools — downloadable calculators that convert thermal metrics (approach temp, delta‑T, pumping energy) into financial outcomes under multiple electricity and water price scenarios.
-
Procurement templates — RFP language, SLA constructs, and acceptance test plans that align with ASHRAE test addenda and industry best practices.
-
Risk & compliance matrix — mapping of regulatory drivers, product certification needs, vendor mitigation options, and contractual language to manage transition risks.
Deliberately, the report follows a “trailer” principle in its public outputs: we demonstrate analytical depth and operational rigor, but we withhold the full granular segmentation tables, confidential supplier scoring and unit‑level pricing models from the public summary. These datasets are integral for procurement negotiations and scenario planning; qualified buyers are invited to access the full data package via our report portal.
Actionable recommendations for 2026
-
Convert pilots into modular rollouts where possible. The economics of rack‑level CDUs improve materially at scale when paired with predictable maintenance contracts and integrated monitoring.
-
Embed ASHRAE‑aligned acceptance tests into procurement. Demand vendor certification against the updated test methods to de‑risk integration and operational performance.
-
Negotiate spare‑parts and hot‑swap agreements. Given the criticality of pump assemblies and heat‑exchange modules, defined MTTR targets and logistically enabled spares will reduce exposure to costly downtime.
-
Stress‑test total cost scenarios against water and electricity sensitivity. Our TCO tools show threshold points where liquid cooling achieves decisive cost advantage — these should be used to set internal gating criteria for wider adoption.
-
Prioritize vendors with demonstrable system‑level experience. Firms that can manage both server integration and facility interfacing reduce project friction and accelerate time‑to‑value.
Next steps
Organizations preparing procurement strategies, capital plans or technical roadmaps for 2026 should treat rack‑mounted CDUs not as peripheral accessories but as strategic components that influence server architecture, site planning and long‑term energy strategy. PW Consulting’s Rack‑mounted Full Liquid CDU Market Report supplies the modeling, vendor intelligence and operational playbooks required to convert opportunity into measurable business outcomes.
To request the full report package, detailed vendor scorecards, and access to our interactive TCO models, visit PW Consulting’s research portal or contact our industry team for a briefing tailored to your deployment profile.
For detailed analysis of this topic, please visit the official page: Rack-mounted Full Liquid CDU Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Cordless Telephone Battery Market Seen Sliding at -0.51% CAGR to 2032 from 2025 Base of USD 485.5 Million — Europe, Ni‑MH and Aftermarket Lead as Top‑5 Hold 52.2%
By pmarketresearch, 2026-07-15
Worldwide Cordless Telephone Battery Market — Strategic Briefing for 2026 Decision‑Makers
Executive summary
PW Consulting’s new market report on the Worldwide Cordless Telephone Battery Market provides an actionable bridge between industry nuance and boardroom decisions for 2026. The global market has exhibited a muted, slightly negative compound annual growth rate (CAGR) across the 2020–2032 horizon (reported CAGR: -0.51%), with short‑term volatility and pockets of recovery in our baseline forecast. That pattern—stability around a modest base with episodic rebounds—frames the choices facing OEMs, aftermarket specialists, component suppliers and private equity groups preparing to deploy capital or reconfigure operations this year.
Worldwide Cordless Telephone Battery Market
Why this report matters for 2026 strategy
- Decision timing: 2026 is the inflection window for players who must reconcile lingering legacy product footprints (predominantly NiMH-based handset batteries) with accelerating regulatory and standards shifts—most notably recent EU ecodesign rules and emerging DECT NR+ capabilities.
- Risk management: The market’s near‑flat long‑term trajectory masks concentrated supplier dynamics and episodic raw‑material and regulatory shocks; the report translates those macro patterns into company‑level stress tests and procurement playbooks.
- Value capture: While headline volumes are stable, aftermarket and service monetization opportunities, product upgrade cycles and selective regional rollouts offer differentiated margin expansion for firms that act with calibrated timing and channel focus.
Market trajectory and key macro data
Across the historical 2020–2025 period, the cordless telephone battery market has shown limited net movement with periods of decline and recovery. Our base‑case forecast for 2026 shows a short‑term uptick followed by modest year‑to‑year fluctuations across the 2026–2032 window. The overall long‑run CAGR is mildly negative (-0.51%), indicating a market that is mature and subject to substitution pressures, but not collapsing.
Worldwide Cordless Telephone Battery Market
For 2026 planning this implies a two‑track approach: protect core revenue pools tied to installed base replacement cycles while selectively investing in technology, compliance and service innovations that refresh product relevance. The numbers in the full report underpin scenario models that quantify revenue, margin and inventory implications for multiple operational plays; executives can run “what if” permutations for regulatory tightening, raw‑material price shocks and accelerated DECT NR+ adoption.
Worldwide Cordless Telephone Battery Market
Dynamics shaping the near term (2026)
- Regulatory acceleration: The EU’s ecodesign requirements that took effect in June 2025 raise minimum expectations on energy efficiency, standby power and battery cycle life. For 2026 this results in accelerated attrition of non‑compliant legacy models and elevated compliance costs for manufacturers and importers in affected markets.
- Standards and product evolution: DECT NR+ availability and spectrum decisions create pathways for next‑gen cordless handsets with different power and battery management profiles. These technology shifts influence handset form‑factor, battery chemistry choice and service models.
- Raw material and supply chain noise: While cordless handset batteries historically rely on NiMH chemistry (with Li‑ion relevance limited in this low‑power category), broader rechargeable battery market dynamics—and geopolitical pressure on critical minerals—continue to shape supplier terms, lead times and contingency costs.
- Aftermarket resilience: Replacement and service channels remain a structural revenue anchor even as OEM refresh cycles slow. Companies that optimize distribution, warranty economics and refurbishment capture disproportionate share of lifetime handset economics.
Competitive landscape — what we observed
The sector is moderately concentrated: the top three and five players control a meaningful share of market revenues (our concentration metrics are included in the full report). Competitive dynamics are heterogeneous across the value chain:
- Retail and specialist aftermarket players (examples include national battery chains and ecommerce specialists) compete on inventory breadth, in‑store service and rapid fulfillment capabilities. Their strategic advantage lies in brand trust, channel density and aftermarket warranty services.
- Large cordless handset OEMs maintain integrated supply lines for original batteries and benefit from product bundling, but they face exposure to compliance costs and to the declining absolute growth of the handset base.
- Component and pack manufacturers—including global Chinese contract suppliers and established rechargeable battery firms—operate across OEM and aftermarket channels. Their bifurcated business models create both volume scale and specialized niche opportunities (e.g., custom packs for DECT handsets or higher‑cycle replacements for enterprise deployments).
Profiles of the major firms reviewed in the report include strengths, distribution reach, channel strategies and vulnerability mapping. We analyze U.S. aftermarket specialists known for replacement compatibility and retail presence, regional handset brands with proprietary pack integration, and global cell/pack manufacturers with export footprints. The report evaluates where each firm is positioned on the spectrum from commoditized replacement products to differentiated system suppliers.
Recent developments and strategic implications
- EU Ecodesign (effective June 2025): Short‑term winners are firms that rapidly certify models and offer retrofit/upgrade paths; losers are supply‑chain constrained OEMs with large inventories of non‑conforming models. Practical action: prioritize compliance testing, develop trade‑in/refurb programs, and pre‑empt enforcement via voluntary labeling.
- DECT NR+ standard updates (2025): Opens new product pathways for higher‑value handsets; practical action for OEMs and battery suppliers: align roadmaps on energy management, fast charging profiles, and handset power budgets.
- Product launches (e.g., portable DECT devices introduced in 2025): Signal continued niche innovation and point to opportunities for battery suppliers to co‑develop packs tailored to evolving handset capabilities.
What the report delivers — practical, operational outputs
This is not a descriptive study. The report is structured as a decision tool for 2026 executives and includes:
- A flexible financial model (Excel) that allows users to run sensitivity analyses across demand, price and raw‑material inputs and project P&L and working capital impacts under alternative regulatory and technology scenarios.
- Actionable go‑to‑market playbooks for OEMs, aftermarket retailers and specialist pack manufacturers covering inventory optimization, warranty economics, refurbishment programs, and channel pricing strategies.
- Supply‑chain heatmaps and supplier scorecards that prioritize dual‑sourcing, quality audits and nearshoring levers—each with step‑by‑step mitigation tactics and estimated implementation timelines.
- Competitive scorecards and acquisition targets: risk‑adjusted valuation heuristics for potential M&A targets, plus integration checklists to accelerate value capture post‑deal.
- Regulatory matrix: country‑by‑country compliance checkpoints, testing timelines and cost envelopes to help procurement and regulatory teams plan certification and labeling programs in 2026.
- Scenarios calibrated to the reported market forecast and concentration metrics, showing paths under faster DECT NR+ adoption, aggressive ecodesign enforcement, or raw‑material price escalation.
Strategic recommendations for 2026
- Prioritize compliance and warranty redesign: Treat ecodesign compliance as a market access and customer‑retention initiative. Design replacement and refurbishment programs that monetize regulatory upgrades and reduce trade‑in friction.
- Segment channel strategies: Protect aftermarket revenue with faster fulfillment, certified replacement SKUs and turnkey warranty services; for OEMs, selectively pursue premium DECT NR+-enabled handsets that justify higher ASPs and recurring accessory sales.
- De‑risk supply chains: Actionable steps include dual‑sourcing key pack assemblies, negotiating price‑index clauses for key raw materials, and piloting regionalization for critical SKUs to reduce tariff and logistics exposure.
- Invest in product differentiation where it pays: In low‑growth markets, differentiation beat scale—battery vendors should offer validated higher‑cycle packs, extended‑warranty programs and co‑branded service offerings with handset OEMs and retailers.
- Use M&A tactically: Acquire access to distribution or complementary service capabilities rather than pure cell capacity; small bolt‑on acquisitions can accelerate aftermarket penetration and provide immediate customer insight for cross‑sell.
How PW Consulting can accelerate your 2026 program
Clients who engage PW Consulting receive tailored scenario workshops, model recalibration to reflect their portfolio and a two‑week rapid audit of their supply chain and certification posture. For teams preparing 2026 budgets, we translate the report’s scenario outputs into an executable 90‑day action plan with KPIs, estimated capex/Opex impact and prioritized vendor shortlists.
Next steps — where to find the missing detail
This briefing outlines the strategic contours and operational implications for 2026. To preserve the high value of our proprietary segmentation work and the detailed tables that underpin targeted plays, we have deliberately omitted granular regional and application splits here. The full report contains those segment tables, unit and revenue breakouts, company scorecards and the downloadable financial model referenced above. Visit the PW Consulting report page to access the complete dataset, appendices and implementation toolkit.
For executive briefings, model walkthroughs or to commission a bespoke scenario tailored to your portfolio and supply chain footprint, contact PW Consulting’s industry practice. Our team will help you convert the market’s modest headline movement into differentiated, defensible value in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Cordless Telephone Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Trichomonas Rapid Testing Market Poised for 6.3% CAGR (2026–2032)
By pmarketresearch, 2026-07-15
Worldwide Trichomonas Rapid Testing Market: Strategic Preview for 2026 Decision‑Making
As PW Consulting’s Senior Strategy Advisor and Head of Industry Analysis, I present an executive preview of our latest market study — Worldwide Trichomonas Rapid Testing Market (Base Year: 2025). This briefing distills the report’s most consequential strategic takeaways for 2026 planning cycles while intentionally withholding core segment-level figures to direct executive readers to the full report for transaction‑grade intelligence.
Worldwide Trichomonas Rapid Testing Market
Market at a Glance: Growth Trajectory and Structural Signals
The Trichomonas rapid testing market is at an inflection point. Our model — which synthesizes historical performance (2020–2025), primary interviews with clinical decision makers, regulatory filings, and product commercialization timelines — projects growth from an estimated USD 685.4 Million in 2025 to roughly USD 1,051.2 Million by 2032, reflecting a compound annual growth rate (CAGR) of 6.3% for the 2026–2032 forecast window.
Worldwide Trichomonas Rapid Testing Market
- Momentum drivers: faster point-of-care molecular platforms achieving CLIA classification shifts, expanding at‑home diagnostic authorization, and improved clinical awareness of the epidemiologic burden of trichomoniasis.
- Structural features: a moderately concentrated vendor landscape (CR3 ≈ 58.4%; CR5 ≈ 72.15%) that favors well‑capitalized incumbents with regulatory and reimbursement footholds.
Why This Matters for 2026 Strategy
For commercial, clinical, and investor stakeholders contemplating moves in 2026, three strategic realities should determine priorities.
Worldwide Trichomonas Rapid Testing Market
- Regulatory & reimbursement positioning is a primary barrier to rapid adoption. The market rewards products that combine robust clinical performance with clear regulatory pathways and coding/reimbursement clarity. Notably, the OSOM Trichomonas Rapid Test benefits from CLIA waiver status and a Medicare reimbursement association — advantages that materially shorten sales cycles for point-of-care adoption. Similarly, recent clearances for point‑of‑care PCR platforms underscore the premium placed on regulatory clarity.
- Technological bifurcation shapes go‑to‑market plays. Rapid antigen lateral flow tests remain attractive for low‑cost, high‑throughput screening; meanwhile, isothermal and cartridge‑based molecular formats are carving clinical niches that demand higher margins but require different commercialization constructs (instrument placement, service, and operator training).
- Clinical validation and real‑world performance are deal catalysts. Meta‑analytic evidence published in mid‑2025 reports pooled sensitivities around the high 80s and specificities nearing the high 90s for rapid antigen tests — data that materially inform provider adoption thresholds and payer coverage decisions. Strategic investors and partners will prioritize access to clinical datasets and head‑to‑head performance comparisons.
Competitive Landscape: Who Matters and Why
The competitive map is characterized by a mix of specialized diagnostics vendors and broader molecular-platform players. Our research highlights distinct competitive archetypes and tactical implications.
- Sekisui Diagnostics (Burlington, MA) : The company’s OSOM® Trichomonas Rapid Test represents a strategic template — a CLIA‑waived lateral flow antigen product that pairs rapid time‑to‑result with established reimbursement signals. Its market positioning demonstrates how regulatory classification can substitute for heavy marketing spend in clinician segments where simplicity and coding are decisive.
- QuidelOrtho (San Diego, CA) : With isothermal molecular assays (e.g., Solana™) and a history of acquiring rapid molecular capabilities, QuidelOrtho exemplifies the vendor pursuing mid‑complexity laboratories and urgent‑care networks. Their playbook emphasizes bundled solutions and channel partnerships to drive instrument utilization.
- Cepheid (Sunnyvale, CA) : The GeneXpert TV assay shows how cartridgeized molecular platforms can expand specimen types and clinical workflows — enabling symptomatic and asymptomatic testing across female and male specimens. Cepheid’s installed base remains one of the most defensible commercialization moats for molecular Trichomonas testing.
- Regional and emerging vendors (e.g., Liming Bio, Vitrosens Biotechnology) : These firms compete primarily on cost, localized regulatory approvals, and distribution partnerships. Their presence matters most in price‑sensitive channels and emerging markets, and they are frequent acquirers or targets in roll‑up strategies aiming to consolidate decentralized procurement.
Recent industry events reinforce competitive dynamics: in March 2025, Visby Medical’s at‑home sexual health test obtained FDA clearance (including CLIA waiver), opening an addressed market for consumer‑directed molecular testing. Coupled with the July 2025 meta‑analysis showing substantial specificity for antigen tests, 2026 will be a year of product differentiation based on use case (POC vs. at‑home vs. lab‑based), specimen flexibility, and validated clinical performance.
Practical, Tactical Insights Contained in the Full Report
Our Worldwide Trichomonas Rapid Testing Market report is intentionally action‑oriented. For executives preparing 2026 budgets, M&A screens, or commercialization roadmaps, the full deliverable contains:
- Scenario models (conservative, base, aggressive) that translate the 2026–2032 CAGR into revenue sensitivities under alternative reimbursement and regulatory outcomes.
- Go‑to‑market playbooks by customer segment (diagnostic laboratories, hospitals/clinics, and home/consumer channels), including recommended pricing architecture, distributor economics, and sample instrument placement strategies.
- Regulatory pathway matrices mapping likely approval routes and timelines for antigen, isothermal, and PCR‑based offerings — including checklist items to accelerate CLIA waiver submissions and payer coverage requests.
- Reimbursement and coding intelligence that outlines current code associations, payer behavior indicators, and templated messaging to support coverage negotiations.
- Competitive due diligence packets for the leading vendors and a roll‑up target shortlist by capability and geography (note: granular segment revenue splits are not disclosed here in this press preview).
- Clinical evidence synthesis with guidance on study design that will most effectively shift clinical guidelines and payer policies (including sample size and comparator recommendations informed by the latest meta‑analysis).
What 2026 Priorities Should Commercial Leaders Set?
Based on scenario testing and primary research, we recommend three immediate priorities for teams that want to convert market potential into realized revenue in 2026:
- Lock regulatory advantage or partner to access it. If your product can achieve CLIA waiver or an equivalent point‑of‑care classification, prioritize that pathway and align clinical trials to the tolerances payers use for coverage decisions.
- Build a hybrid commercial model. Expect demand to be heterogeneous: some customers will prioritize low unit cost and simplicity (favoring antigen lateral flows), while others will adopt molecular assays for higher sensitivity and multi‑pathogen panels. Dual channel strategies — direct for higher complexity accounts and distributor/channel for high‑volume low‑touch accounts — are the optimal compromise.
- Invest in clinical data that matters to payers. Payers increasingly require real‑world evidence and health economic models. Early budget‑impact analyses and claims data partnerships will accelerate coverage decisions and widen clinical uptake.
How Investors and M&A Teams Should Read the Market
The mid‑2020s market is ripe for consolidation and bolt‑on acquisitions that can rapidly increase addressable markets or add regulatory approvals. Targets with any of the following characteristics will command premium valuations:
- Validated CLIA‑waived diagnostics or a credible near‑term path to CLIA waiver.
- Installed instrument bases with high cartridge pull‑through economics or sticky service contracts.
- Clinical data demonstrating superior sensitivity/specificity in head‑to‑head or real‑world studies, especially across asymptomatic screening cohorts.
Buyers should price in the time required to secure payer coverage and integrate distribution networks; our scenario work provides runway and ROI timelines tailored to deal structures.
Conclusion — Why PW Consulting’s Intelligence Is a Must for 2026
The Trichomonas rapid testing market presents a classic tradeoff for 2026 planners: near‑term opportunity from expanded point‑of‑care and at‑home testing balanced against execution risk tied to regulatory classification and payer coverage. Our study quantifies the opportunity at the market level, outlines practical pathways to deploy capital and commercial resources, and provides the clinical and regulatory playbooks that materially reduce strategic risk.
To preserve the strategic value of the dataset and to encourage fulsome decision support, this preview does not disclose the report’s granular regional and end‑user splits. The full report contains those segment details, exhaustive vendor profiles, and downloadable model files that will enable executives to run bespoke scenarios for 2026 board decisions.
For access to the complete Worldwide Trichomonas Rapid Testing Market report and to commission a tailored briefing for your leadership team, please visit our report page or contact your PW Consulting account director.
For detailed analysis of this topic, please visit the official page: Worldwide Trichomonas Rapid Testing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Multifunction Baby Monitors Market to Grow at 8.12% CAGR Through 2026–2032
By pmarketresearch, 2026-07-15
Worldwide Multifunction Baby Monitors Market — Strategic Preview for 2026 Decision-Making
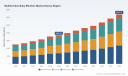
As brands, investors, and supply‑chain leaders set priorities for 2026, our new PW Consulting market study on Worldwide Multifunction Baby Monitors provides a focused, executable perspective on where to allocate R&D, manufacturing capacity, go‑to‑market investment, and compliance resources. The global market for multifunction baby monitors is at an inflection point: after reaching a reported USD 1,850.25 Million in 2025, PW Consulting’s forecast shows the market accelerating to roughly USD 3,195.75 Million by 2032, representing a compound annual growth rate (CAGR) of 8.12% across the 2026–2032 horizon. 2026 is the first full forecast year in which several structural shifts — AI-enabled sensing, supply‑chain rebalancing, and heightened regulatory scrutiny — will materially change competitive positioning. This preview outlines the strategic stakes for 2026 while reserving the granular segment matrices for subscribers who require the full dataset and tactical models.
Worldwide Multifunction Baby Monitors Market
Why 2026 Is a Strategic Pivot Year
- Demand maturation with technology premiumization. Consumers increasingly expect multifunction monitors that combine high‑resolution video, contactless respiratory and movement sensing, and app‑based analytics. Vendors that can credibly bundle AI insights with privacy‑first architectures will capture the premium segment as parents trade up from basic video models.
- Supply-chain and component pressure. Semiconductor lead times and cost pressures, driven in part by broader AI demand, are extending procurement cycles for MCUs and sensors — affecting time‑to‑market for Wi‑Fi and AI‑enabled units. Separately, camera module demand in adjacent markets remains a significant influence on availability and pricing of key optical components.
- Regulatory and safety risk as a differentiator. High‑profile recalls and growing scrutiny of connected childcare devices mean that risk management and compliance will be front‑and‑center in purchasing decisions by major retailers and distributors.
Data Snapshot — Market Trajectory
PW Consulting’s model uses a 2025 baseline of USD 1,850.25 Million and applies scenario‑tested drivers to project a 2026 market near USD 1,991.97 Million on the way to USD 3,195.75 Million in 2032 (CAGR 2026–2032: 8.12%). These results are reinforced by cross‑checks against component market trends and consumer electronics adoption curves; the full report provides payer‑level price elasticity curves and demand sensitivity to feature bundles for 2026 planning.
Worldwide Multifunction Baby Monitors Market
Key Market Dynamics Shaping Strategy
- AI and sensing innovation. Market leaders are integrating AI to detect breathing patterns, face covering, and rollover risks, and coupling this with sleep analytics. This wave favors companies that control both hardware design and the analytics stack or that secure robust partnerships for edge‑to‑cloud processing.
- Channel shifts and omnichannel merchandising. Online retail continues to broaden reach, but specialty and big‑box channels remain influential for trust and after‑sales service. Retailers are placing higher emphasis on certified safety records and clear privacy documentation when selecting branded assortments for 2026.
- Component concentration and geopolitical friction. Export controls on advanced semiconductors and negotiations around critical minerals have raised the stakes for manufacturers with single‑source supply. Contract manufacturers and in‑house sourcing strategies will be decisive for maintaining production continuity and margin stability.
- Regulatory events create asymmetric risk. Recent safety actions have shown how quickly product recalls can reset consumer trust. Companies must embed product safety validation and transparent recall protocols into product roadmaps to protect brand equity and retail partnerships.
Competitive Landscape — What 2026 Looks Like
The multifunction baby monitor space blends startups with deep‑pocketed consumer electronics players. Market concentration statistics point to a moderately fragmented landscape: the top three players account for roughly 32.4% of market share, while the top five approach 48.65%. That structure leaves room for focused challengers that execute on product differentiation, channel strategy, or margin engineering.
Worldwide Multifunction Baby Monitors Market
- Innovation leaders. Firms that combine vision‑grade video, contactless respiratory sensing, and robust analytics (examples in the report) are competing on feature depth and data experience. Recent product introductions and AI camera rollouts have materially altered brand perceptions and pricing power.
- Scale incumbents. Established consumer electronics and childcare brands continue to leverage distribution breadth and retail trust, pairing tried‑and‑true hardware reliability with incremental smart features to defend mainstream segments.
- Value challengers. Low‑price, multifunction video monitors retain a role through aggressive channel pricing and simplified feature sets — a dynamic particularly relevant for retailer private‑label strategies.
- Reputational and regulatory survivors. Brands that weather recalls or product actions through transparent remediation maintain a competitive advantage with large retailers; conversely, unresolved safety exposures materially limit shelf access and promotional support.
PW Consulting’s full competitive chapter evaluates selected firms across product architecture, firmware update cadence, cloud privacy posture, manufacturing footprint, and retail channel support. We include vendor risk‑heat maps and an M&A watchlist that identifies likely consolidation targets and acquirers for 2026–2027.
Recent Industry Events — Strategic Implications
- Product safety incident (early 2026). A recall affecting a prominent movement‑monitor model underscored the operational cost of safety lapses, from direct recall expense to retail delisting risk. For 2026, manufacturers must factor product safety assurance and recall readiness into product‑cost modelling.
- AI product rollouts (2025–2026). Several players announced or launched AI‑enabled cameras and wearable pairings that elevate multifunction claims beyond simple audio/video. These moves accelerate consumer expectations and raise the bar for software maintenance and OTA update strategies.
- Component market signals. Camera module demand and semiconductor pricing dynamics are pushing manufacturers to secure multi‑tier suppliers and hedge contracts; this is an actionable priority for both OEMs and private‑label partners planning 2026 inventory buys.
What This Means for 2026 Corporate Decisions
- Product roadmap and feature prioritization. Companies should prioritize contactless sensing and AI features that can be demonstrated in third‑party testing and that align with emerging regulatory expectations. Our report supplies a prioritized feature‑ROI matrix tailored to low, medium, and high price tiers.
- Supply‑chain resilience investments. Build redundancy in MCU and camera supply, consider near‑sourcing certain modules, and negotiate capacity clauses. PW Consulting’s supplier stress tests quantify the trade‑offs between cost and lead‑time risk for 2026 procurement cycles.
- Retail and channel playbook. Secure assortment by aligning product SKUs to retailer risk thresholds for safety documentation and warranty handling. The report includes an actionable checklist for getting back‑on‑shelf after safety events.
- M&A and partnership tactics. Given the middling concentration, targeted bolt‑ons can accelerate capabilities in sensing or cloud analytics. Our M&A playbook highlights candidate profiles and post‑deal integration priorities focused on firmware, cloud, and customer support consolidation.
- Compliance and privacy posture. Strengthen firmware update mechanisms, document data flows, and publish transparent privacy impact assessments to maintain consumer trust and retail access.
Report Deliverables — Practical Content for Executives
PW Consulting’s full report is designed as an executable toolset for 2026 planning. Among the deliverables:
- Market forecast model (2026–2032) with scenario toggles and sensitivity to component cost and adoption curves.
- Feature ROI frameworks and prioritized product roadmaps for three price tiers.
- Supplier risk heat maps and procurement playbooks to manage semiconductor and camera module exposure.
- Retail channel assessment and shelf‑access checklist tied to safety and privacy expectations.
- Competitive profiles with strategic implications, M&A watchlists, and readiness checklists for post‑recall remediation.
To preserve the strategic value of these analyses for our clients, the public summary intentionally omits the granular regional and product‑type revenue splits and SKU‑level pricing tables; subscribers receive full access to those layers and interactive models that operational teams can drop directly into planning workflows.
How PW Consulting Can Support Your 2026 Plan
- Custom scenario modelling. Rapid turn‑around scenario builds to stress‑test inventory, pricing, and promotional plans against supply interruptions or regulatory events.
- Vendor due diligence. Technical and compliance audits for potential partners or acquisition targets, including firmware lifecycle and cloud privacy assessment.
- Go‑to‑market acceleration. Channel negotiation support, retailer readiness kits, and post‑recall relaunch playbooks tailored to major global retailers.
Conclusion — The Imperative for 2026
Multifunction baby monitors will remain a growth category through the end of the decade, but 2026 is the year when product architecture, supplier strategy, and regulatory preparation will determine winners and losers. PW Consulting’s Worldwide Multifunction Baby Monitors Market report arms executives with the forecasts, tactical playbooks, and competitive intelligence needed to make fast, defensible choices in product development, sourcing, and commercial execution. For access to the complete dataset, interactive models, and supplier‑level analyses that underpin the findings summarized here, please consult the full report on our website.
For detailed analysis of this topic, please visit the official page: Worldwide Multifunction Baby Monitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide International Freight Forwarding Market to Grow at 4.55% CAGR (2026–2032) as Asia‑Pacific Drives Demand
By pmarketresearch, 2026-07-15
Worldwide International Freight Forwarding Services Market — Strategic Outlook for 2026
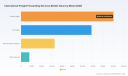
PW Consulting today publishes the executive briefing for our new market intelligence product, "Worldwide International Freight Forwarding Services Market (Base year: 2025; Forecast: 2026–2032)". The analysis synthesizes five years of historical performance (2020–2025) with forward-looking scenario modeling to support executive decision-making in 2026. At the macro level, the global market reached approximately USD 200 billion in 2025 and — under our central scenario — is expected to grow at a compound annual growth rate (CAGR) of roughly 4.55% through 2032, approaching an aggregate in the low‑to‑mid‑hundreds of billions by the end of the forecast period.
Worldwide International Freight Forwarding Services Market
Why this report matters for 2026 decisions
- Market sizing you can act on: granular topline trajectories and stress-tested demand scenarios to inform budget cycles, procurement commitments, and capital allocation.
- Risk-to-opportunity translation: we convert industry headwinds — from fuel and regulation to geopolitics — into prioritized operational and commercial responses.
- Competitive playbooks: our profiles and capability mapping let you benchmark service partners and design procurement scorecards tied to measurable KPIs.
- Implementation-ready: the report is specifically constructed to feed RFPs, network-optimization projects, and board-level strategy reviews in 2026.
Market dynamics shaping 2026 strategy
The freight forwarding sector is operating in a period of simultaneous structural and cyclical forces. After a volatile 2020–2025 period characterized by demand swings and periodic supply chokepoints, the industry is settling into a growth path underpinned by steady global trade expansion and modal diversification. That said, several proximate dynamics will materially affect commercial outcomes and should be central to any 2026 planning conversation.
Worldwide International Freight Forwarding Services Market
- Regulatory and fuel cost pressure. New emissions regimes and tightening environmental rules — combined with elevated bunker/fuel prices — are increasing delivered cost volatility. Carriers and forwarders are adjusting rate-management engines and fuel-pass-through clauses; shippers should expect accelerated cost indexing and new compliance surcharges over the next 12–24 months.
- Route risk and resiliency. Recent Red Sea disruptions and shifting trade lanes have shown how fragile certain chokepoints remain. Forwarders and shippers are re-evaluating contingency routing, capacity buffers, and multi-modal diversification to preserve service continuity.
- Labour and capacity constraints. Rising logistics labour costs in developed markets and localized port congestion are compressing margins and complicating punctuality metrics. The consequence is a renewed focus on productivity-enhancing investments and capacity partnerships.
- Tariff and trade policy volatility. New tariff measures and bilateral trade policy shifts create localized demand elasticities; leading organizations are embedding tariff-scenario capabilities into their network-planning tools.
- Digital acceleration and platform differentiation. Technology is now a primary competitive axis. Late‑cycle platform updates and AI-driven rate management are rapidly re-pricing the service offering, elevating firms that can deliver transparent, real‑time control towers.
Competitive landscape — who moves markets in 2026
The industry is a mix of global integrators, regional champions and nimble digital natives. Our report includes deep strategic profiles for the market’s most influential players, assessing go-to-market models, digital differentiation, asset-versus-asset-light strategies and lane-level competitiveness. Highlights in recent developments reveal the pace of change:
Worldwide International Freight Forwarding Services Market
- DSV completed a transformational acquisition of DB Schenker in late 2025, reshaping scale economics and route coverage for global forwarders.
- Kuehne + Nagel launched an upgraded version of its myKN platform with AI-driven rate management capabilities, signaling a renewed emphasis on dynamic pricing and customer self-service.
- DHL Global Forwarding entered a strategic partnership with Microsoft to integrate AI into supply-chain resilience and visibility solutions.
- Expeditors secured a major strategic client for air freight services, underscoring the ongoing premium on reliability for time-sensitive cargo.
Where we see differentiation emerging in 2026: technology-enabled orchestration (control towers and AI rate engines), bespoke project-logistics expertise, and the ability to provide contract structures that transparently allocate regulatory and fuel risk.
What’s inside the report — practical modules for 2026 execution
Designed as a toolbox for commercial and operations leaders, the report combines insight with implementation. Core deliverables include:
- Executive dashboards: topline market trajectories, scenario ranges and sensitivity analyses designed for board decks.
- Strategic playbooks: carrier-selection templates, procurement scorecards, and negotiation levers tied to current market constructs.
- Network and cost models: total cost of ownership (TCO) calculators, rerouting scenarios, and capacity-cost trade-off matrices.
- Digital-vendor assessment: scorecards to evaluate forwarding platforms on data integration, rate automation, and end‑to‑end visibility.
- Compliance and sustainability roadmap: practical steps to meet near-term regulatory obligations and embed decarbonization into carrier selection.
- Competitive profiles: concise but actionable analyses of leading forwarders — their strengths, recent strategic moves, and capability gaps.
Companies profiled (select)
- Kuehne + Nagel — global leader with integrated digital platforms (myKN) for end-to-end logistics.
- DSV — comprehensive air, sea and road forwarding with strong project logistics capabilities; recent consolidation activity has reshaped scale dynamics.
- DB Schenker — worldwide freight forwarding presence with vertical expertise in automotive and healthcare sectors.
- DHL Global Forwarding — time-critical air and ocean forwarding, investing in AI-enabled resilience tools.
- Expeditors — technology-driven forwarder with proprietary EDI systems and contract wins in high-reliability segments.
- CEVA Logistics, UPS Supply Chain Solutions, FedEx Trade Networks, Nippon Express, Sinotrans, C.H. Robinson, Hellmann, Geodis, Bolloré Logistics, Agility — each assessed on modal strength, digital maturity and regional positioning.
How executives should act in 2026 — six prioritized recommendations
- Rebalance procurement horizons. Combine short-term spot capacity for critical lanes with longer-term indexed contracts to hedge fuel and regulatory pass-throughs.
- Embed scenario triggers into contracts. Build dynamic clauses tied to credible trigger events (fuel indices, regulatory thresholds, force majeure routing) to reduce renegotiation risk.
- Accelerate rate-management capabilities. Invest in or partner with forwarders that offer AI-enabled rate engines and real-time booking transparency to reduce hold-ups and improve margin capture.
- Prioritize resiliency in network design. Redesign logistics networks to include alternative routings, multi-modal options and regional transhipment hubs to reduce single‑point dependencies.
- Make M&A and partnerships a strategic lever. Whether to acquire niche capabilities or partner with scale players, scenario-driven M&A screening will be a key source of competitive advantage in 2026.
- Operationalize sustainability and compliance. Treat emissions and regulatory reporting as operational questions requiring data pipelines and verified carrier partners — not just policy statements.
Why PW Consulting’s approach is different
Our methodology couples traditional market sizing with tactical, implementation-focused outputs: decision trees for contracting, lane-level stress tests, and a modular playbook you can deploy in procurement or operations projects. The report balances commercial benchmarking with executable tools so teams can move from insight to action rapidly in 2026.
Next steps: where to get the full intelligence
This briefing intentionally highlights strategic implications while preserving the proprietary segmentation tables, lane-level forecasts and the complete competitive-scorecard dataset for subscribers. The full report includes downloadable models, lane dashboards and negotiation templates that executives will use directly in 2026 planning cycles.
For access to the complete dataset, interactive dashboards and implementation templates, please visit our report page or contact the PW Consulting industry team. Our analysts are prepared to run bespoke scenario workshops tailored to your network and commercial objectives as you enter the 2026 budget and execution cycle.
For detailed analysis of this topic, please visit the official page: Worldwide International Freight Forwarding Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide High‑Power CW Laser Market to Expand at 8.5% CAGR Through 2032 as Asia‑Pacific Leads Growth
By pmarketresearch, 2026-07-15
Worldwide High Power CW Laser Market: Strategic Imperatives for Corporate Decision-Making in 2026
Executive summary
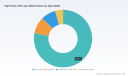
PW Consulting’s new market brief, Worldwide High Power Continuous-Wave (CW) Laser Market — 2026 Preview, synthesizes five years of historical intelligence and a forward-looking forecast through 2032 to equip executives with the commercial and technical context they need to act decisively this year. Our baseline assessment shows the market scaling from roughly USD 2.15 billion in 2020 to about USD 3.4 billion by 2025, and continuing on an accelerated trajectory to exceed USD 6.0 billion by 2032. This expansion, underpinned by an 8.5% compound annual growth rate across the forecast window, is reshaping supplier strategies, capital allocation, and go-to-market plays across industrial, automotive, aerospace, and datacenter end markets.
Worldwide High Power CW Laser Market
Why this report matters for 2026 planning
- Timing decisions: With visible momentum and accelerating demand drivers, 2026 is a critical inflection year for committing to capacity upgrades, strategic partnerships, or targeted R&D investments.
- Risk calibration: The brief quantifies near-term supply and input risks (including gallium/indium supply dynamics) and pairs these with mitigation options — from diversified sourcing to design-for-recycling strategies.
- Competitive positioning: We map technology, manufacturing footprint, and margin levers for incumbent and rising suppliers, enabling business leaders to translate market movements into defensible product roadmaps and M&A screens.
Market trajectory and structural takeaways
The high-power CW laser market is no longer a niche engineering play — it is a scalable industrial technology category with multiple adjacent growth pathways. Our modelling shows a near-term uplift in demand driven by intensified automation (Industry 4.0), EV battery joining processes, and precision additive manufacturing in aerospace. Equally important are nascent yet strategic opportunities in datacenter and silicon-photonics co-packaged optics, where high-reliability CW sources are being reassessed for new thermal and wavelength-management requirements.
Worldwide High Power CW Laser Market
Consolidation dynamics are mature: market leadership is concentrated among a handful of global players who combine system-level capabilities, component mastery, and installed-service footprints. The market structure rewards scale in R&D and manufacturing, but there remains opportunity for differentiated entrants that win on cost-performance, localization, or specialized beam-shaping capabilities.
Worldwide High Power CW Laser Market
Competitive landscape — what to watch
- Established global leaders are doubling down on both power scaling and beam quality. Firms with deep fiber-laser portfolios continue to extend continuous-wave output while optimizing energy efficiency and compactness for factory-floor adoption.
- Systems integrators and diode specialists are pushing the boundaries of custom beam shaping and thermal management to serve automotive and aerospace welding applications. The competitive set blends multinational incumbents and aggressive regional players that offer cost-effective multi-kilowatt solutions.
- New vectors of competition are emerging from the datacenter and silicon-photonics arena, where sub-watt to high-mW class CW sources (and the production processes that create them) are becoming strategic. This is prompting cross-domain partnerships between industrial laser makers and photonics foundries.
Recent product and program activity exemplifies these dynamics. In early 2026, a leading fiber-laser OEM showcased a new compact single-mode 8 kW source and secured industry recognition for innovation in beam quality and reliability. Another major supplier is actively sampling high-power CW devices tailored for datacenter optical subsystems, indicating an intent to bridge industrial lasers and photonics manufacturing. At the same time, high-efficiency InP DFB developments in 2025 underscore an accelerating push toward compact, high-reliability CW transmitters for communications and co-packaged optics.
Technology and product strategy implications
- Beam quality and energy efficiency will be primary differentiation vectors. Buyers are increasingly specifying not just nominal power but defined M², back-reflection resilience, and overall wall-plug efficiency when locking procurement plans.
- Modularity and thermal design reduce total cost of ownership. Systems that simplify serviceability, spare module replacement, and field-upgrade paths create durable value for contract manufacturers and OEMs.
- Cross-domain product roadmaps matter. Suppliers that can leverage photonics manufacturing techniques for mass-producible CW sources — or that collaborate with semiconductor foundries — will unlock new addressable markets.
Supply chain, raw materials, and regulatory dynamics
Supply-side factors are an operational reality for 2026 decision-makers. Concentration of critical materials (notably gallium and indium) in specific geographies has translated into price volatility and sourcing risk over the past 24 months. While recycling and recovery initiatives in the region have eased price pressure toward late‑2025, procurement strategies that assume stable cost inputs are exposed. Tactically, firms should evaluate dual-sourcing, longer purchase horizons for strategic materials, and design changes that reduce dependence on constrained elements.
Regulatory and safety requirements for high-power CW lasers demand specialized investments in product development and service training. Thermal management, non-linear optical effects, and standards compliance pose both engineering hurdles and market access gates. Companies that treat regulatory readiness and field-support capabilities as market enablers — not merely cost centers — will gain higher lifetime value from key industrial accounts.
Actionable plays for 2026
- Prioritize selective capacity investments tied to demonstrable demand corridors. Avoid broad-based, undifferentiated expansion; instead, align capital expenditure with validated end-user commitments and multi-year service contracts.
- Fast-track partnerships with photonics foundries and materials recyclers. Securing upstream inputs and manufacturing know-how reduces exposure to raw material cycles and accelerates product cost-down.
- Differentiate on service and integration. Offerability that bundles laser modules with standardized control, diagnostics, and field-service contracts shortens buyer evaluation cycles and protects margins.
- Refine M&A screens to target beam-shaping IP, thermal systems, and regional production capacity. Look for tuck-ins that rapidly expand addressable markets without large greenfield spends.
- Embed regulatory and safety certification costs into time-to-market scenarios. Early certification planning reduces launch risk and avoids costly redesigns after customer qualification milestones.
What PW Consulting’s report delivers (practical contents)
- Robust market sizing and forecasting model (2020–2032) with base-year calibration and scenario toggles for upside/downside demand shocks.
- Decision-oriented competitor dossiers: technology positioning, manufacturing footprints, go-to-market channels, and an M&A heatmap.
- Technology roadmap analysis that connects beam architecture, diode advances, and system-level trade-offs to buyer economics.
- Supply-chain stress-testing, including raw material exposure analysis and mitigation playbooks (sourcing, inventory strategy, and design-for-recovery).
- Commercial playbooks: channel segmentation, pricing ladders, and contract structures that accelerate enterprise procurement acceptance.
- Regulatory and safety compliance checklists, field-service staffing models, and total cost of ownership calculators tailored to high-volume industrial adoption.
- Executive-ready scenario decks and investment decision trees that managers can slot directly into CAPEX committees and strategy sessions.
How leaders are already responding
Leading vendors are exhibiting three parallel responses: aggressive product innovation to push beam quality and efficiency, strategic moves into adjacent photonics and datacenter applications, and supply-chain measures to dampen raw-material volatility. The most successful adopters of these responses are not just spending more on R&D; they are reallocating R&D and commercial resources toward validated, near-term revenue streams while preserving optionality for emerging segments.
Conclusion — strategic read for 2026
For executives charting 2026 roadmaps, the imperative is clear: move from hypothesis to commitment where demand is proven, but maintain structural flexibility for emerging opportunities. The high-power CW laser market’s secular growth (8.5% CAGR across the forecast horizon) creates ample room for value creation — but competitive advantage will accrue to organizations that pair disciplined capital allocation with supply-chain resilience and product differentiation rooted in beam performance and system integration.
PW Consulting’s Worldwide High Power CW Laser Market brief is constructed as a decision-support tool — offering both the macro clarity and the tactical depth required to set priorities, size investments, and choose partners with confidence. For a guided tour of the report’s proprietary models, scenario decks, and competitive heatmaps, visit our report page and request the executive extract.
For detailed analysis of this topic, please visit the official page: Worldwide High Power CW Laser Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Metal Facade Cladding Market to Reach USD 24,616.42 Million in 2025, Growing at a 5.42% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Metal Facade Cladding Market: Strategic Outlook for 2026 — PW Consulting Intelligence Brief
Executive snapshot
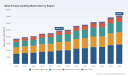
PW Consulting’s new market study on the Worldwide Metal Facade Cladding sector provides a decision-grade strategic roadmap for companies preparing for 2026 and beyond. The global market — valued at approximately USD 24.6 billion in the report’s base year (2025) — is forecast to expand at a compound annual growth rate (CAGR) of 5.42% through the 2026–2032 horizon, reaching a projected market scale in excess of USD 35.6 billion by 2032. While headline growth is steady, underlying forces — raw material volatility, tightening safety and energy regulations, and evolving customer expectations for performance and aesthetics — create a complex operating context where timely strategic choices will determine winners and laggards.
Worldwide Metal Facade Cladding Market
Why this report matters for 2026 decision-making
-
Actionable foresight: The study translates macro-growth projections into practical strategic options — prioritizing where to invest, when to de-risk, and how to structure go-to-market approaches under mid-cycle inflationary pressure.
Worldwide Metal Facade Cladding Market -
Risk calibration: Material cost shocks and regulatory updates are no longer episodic concerns but primary determinants of margin and specification choices. The report quantifies sensitivity to metal price shifts and models the impact on supplier margins and tender outcomes.
Worldwide Metal Facade Cladding Market -
Competitive clarity without data overload: We map manufacturer capabilities, distribution models, and innovation trajectories to help executives identify the most viable partnership and M&A targets, while preserving detailed segment-level tables for licensed users.
What the report contains — practical intelligence for 2026
-
Market sizing and forecast framework: Annualized market values from 2020 through our base year (2025) and a year-by-year projection to 2032, with scenario overlays for inflationary and deflationary inputs.
-
Price and cost modeling: Dynamic models incorporating recent raw material moves, including recorded aluminum price upticks and supplier price actions, enabling rapid recalibration of procurement and pricing strategies.
-
Regulatory and specification playbook: Impact analysis of energy codes, fire-safety rules and sustainability certifications (e.g., LEED/BREEAM, EPBD implications), plus an operational checklist for compliance-driven product development and specification wins.
-
Supply-chain and commercial stress tests: Supplier concentration, lead-time sensitivity, and logistics risk matrices tailored to manufacturing and fabricating partners in metal cladding value chains.
-
Competitive landscaping: Profiles and strategic assessment of the market’s principal players, including their product emphases, vertical integration, and routes to market — enabling shortlists for JV partners, acquisition targets or procurement alternatives.
-
Scenario-driven playbooks: Three executable strategic pathways for OEMs, fabricators and distributors — “Protect & Optimize” (cost discipline and contract renegotiation), “Differentiate & Command” (product innovation and premiumization), and “Scale & Integrate” (roll-up and supply assurance) — with milestone-driven KPIs and investment benchmarks.
-
Commercial toolkit: Tender templates, RFP language for energy- and fire-compliant cladding, and a concise ROI calculator to evaluate material choice, lifetime maintenance and energy savings under different code assumptions.
Competitive landscape — who is shaping the market
The market remains broadly fragmented by revenue share (a low combined share of the top three and top five players), signaling continued space for regional specialists and new entrants. That fragmentation sustains competitive pressure on price but also creates opportunities for consolidation where scale and integrated capabilities matter.
-
Kingspan Group (Ireland) — Known for insulated metal panels and high-performance cladding systems, Kingspan is positioned to capture specification-driven demand in commercial and industrial projects emphasizing energy efficiency.
-
Alucobond (3A Composites; Germany/Switzerland) — A leader in aluminum composite panels (ACP), Alucobond’s strengths are lightweight, fire-rated, and highly customizable solutions that appeal to contemporary architectural programs.
-
Arconic Corporation (United States) — With established brands for high-rise facades, Arconic competes on coating technology and structural performance for tall buildings where durability and finish consistency are critical.
-
Tata Steel Limited (India) — Focused on pre-finished steel and aluminum offerings, Tata’s value proposition includes scale and sustainability messaging for cost-sensitive markets pursuing long-life building envelopes.
-
Alucoil (Spain) — Specializes in advanced ACM and lacquered aluminum systems tailored for façade, transport and industrial cladding applications where controlled aesthetics are paramount.
-
ALPOLIC (Mitsubishi Chemical) — Offers metal composite materials known for architectural versatility; strength in R&D and brand recognition supports high-end specification wins.
-
ArcelorMittal (Luxembourg) — Provides steel-based facade solutions through a building-envelope focus, leveraging integrated steelmaking and coatings know-how.
-
PAC-CLAD (Petersen Aluminum; United States) — A leading architectural panel supplier with recent commercial actions reflecting raw material cost pressure.
-
Zahner (United States) — A niche, design-led fabricator for bespoke projects relying on high craftsmanship and specialty metals such as stainless steel and copper.
-
BlueScope Steel (Australia) — Delivers pre-painted steel systems suited to large-scale commercial and industrial projects in regional markets.
-
Reynaers Aluminium (Belgium) — Focused on curtain wall and high-performance aluminium systems for energy-efficient façades.
-
Americlad (United States) — Specializes in architectural cladding fabrication and modular solutions that speed installation and reduce on-site risk.
Recent developments and market signals
-
Supplier price actions: Some fabricators announced material price increases in late 2025, reflecting upstream metal cost pressure. Procurement teams must assume base-case cost drift when negotiating 2026 contracts.
-
Pricing volatility: Independent pricing datasets recorded quarter-on-quarter aluminum price rises in Q4 2025, underscoring supply tightness in certain regions and the need for hedging or long-term supply agreements.
-
Regulatory tailwinds: Revised building-energy directives and heightened fire-safety requirements are accelerating specification shifts toward low-maintenance, fire-resistant metal systems — a structural demand driver for the forecast period.
-
Industry convenings: Key trade shows and exhibitions scheduled in 2026 will function as concentrated windows for product launches, specification capture, and alliance-building; active engagement there is a near-term commercial imperative.
Key dynamics and strategic implications
-
Margin management in a commodity-inflated environment — Tactical levers such as localized inventory buffers, index-linked contracts, and selective value-engineering can protect margins without sacrificing spec compliance.
-
Specification-driven premiumization — As energy and safety codes tighten, manufacturers that invest in validated, high-performance systems can command a price premium and secure longer-spec retention.
-
Consolidation opportunities — Low combined market shares among top players create M&A windows for firms seeking scale, particularly for fabricators with technical capability or regional distribution networks.
-
Supply-chain resilience as competitive moat — Firms that integrate upstream supply agreements, diversify metal sourcing, or develop recycled-content offerings will reduce procurement shocks and align with sustainability mandates.
Recommended strategic actions for 2026
-
Immediate: Implement short-term hedges and renegotiations to address raw material price moves; update tender templates to reflect probable cost corridors.
-
Near-term (0–12 months): Prioritize product certification and third-party testing aligned with the newest energy and fire-safety codes to preempt regulatory-based specification shifts.
-
Medium-term (1–3 years): Pursue targeted partnerships or bolt-on acquisitions that add fabrication capacity or specialized alloys; develop a differentiated “low-life-cycle-cost” product narrative grounded in validated energy performance.
-
Organizational: Strengthen commercial analytics with scenario-based pricing playbooks and embed procurement KPIs that explicitly account for lead-time and quality trade-offs.
How PW Consulting’s report helps executives act
This study is designed as a working document rather than a descriptive ledger. Alongside headline market figures and a clear 2026 strategic agenda, the deliverable includes modular tools (cost-sensitivity dashboards, negotiation playbooks, and a shortlist methodology for M&A or partnerships) that teams can deploy immediately. To preserve commercial value for clients, detailed segment-level tables, regional splits, and proprietary unit-cost templates are available exclusively in the licensed report package.
Next steps
For manufacturing executives, fabricators, investors and procurement leaders planning for 2026, PW Consulting’s Worldwide Metal Facade Cladding Market report provides the intelligence and playbooks necessary to convert market visibility into profitable action. Request access to the full report to obtain the segment-level analytics, supplier scorecards and scenario models that inform tactical procurement, product development and M&A decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Metal Facade Cladding Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com