

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Cordless Telephone Battery Market Seen Sliding at -0.51% CAGR to 2032 from 2025 Base of USD 485.5 Million — Europe, Ni‑MH and Aftermarket Lead as Top‑5 Hold 52.2%

Worldwide Cordless Telephone Battery Market — Strategic Briefing for 2026 Decision‑Makers
Executive summary
PW Consulting’s new market report on the Worldwide Cordless Telephone Battery Market provides an actionable bridge between industry nuance and boardroom decisions for 2026. The global market has exhibited a muted, slightly negative compound annual growth rate (CAGR) across the 2020–2032 horizon (reported CAGR: -0.51%), with short‑term volatility and pockets of recovery in our baseline forecast. That pattern—stability around a modest base with episodic rebounds—frames the choices facing OEMs, aftermarket specialists, component suppliers and private equity groups preparing to deploy capital or reconfigure operations this year.
Worldwide Cordless Telephone Battery Market
Why this report matters for 2026 strategy
- Decision timing: 2026 is the inflection window for players who must reconcile lingering legacy product footprints (predominantly NiMH-based handset batteries) with accelerating regulatory and standards shifts—most notably recent EU ecodesign rules and emerging DECT NR+ capabilities.
- Risk management: The market’s near‑flat long‑term trajectory masks concentrated supplier dynamics and episodic raw‑material and regulatory shocks; the report translates those macro patterns into company‑level stress tests and procurement playbooks.
- Value capture: While headline volumes are stable, aftermarket and service monetization opportunities, product upgrade cycles and selective regional rollouts offer differentiated margin expansion for firms that act with calibrated timing and channel focus.
Market trajectory and key macro data
Across the historical 2020–2025 period, the cordless telephone battery market has shown limited net movement with periods of decline and recovery. Our base‑case forecast for 2026 shows a short‑term uptick followed by modest year‑to‑year fluctuations across the 2026–2032 window. The overall long‑run CAGR is mildly negative (-0.51%), indicating a market that is mature and subject to substitution pressures, but not collapsing.
Worldwide Cordless Telephone Battery Market
For 2026 planning this implies a two‑track approach: protect core revenue pools tied to installed base replacement cycles while selectively investing in technology, compliance and service innovations that refresh product relevance. The numbers in the full report underpin scenario models that quantify revenue, margin and inventory implications for multiple operational plays; executives can run “what if” permutations for regulatory tightening, raw‑material price shocks and accelerated DECT NR+ adoption.
Worldwide Cordless Telephone Battery Market
Dynamics shaping the near term (2026)
- Regulatory acceleration: The EU’s ecodesign requirements that took effect in June 2025 raise minimum expectations on energy efficiency, standby power and battery cycle life. For 2026 this results in accelerated attrition of non‑compliant legacy models and elevated compliance costs for manufacturers and importers in affected markets.
- Standards and product evolution: DECT NR+ availability and spectrum decisions create pathways for next‑gen cordless handsets with different power and battery management profiles. These technology shifts influence handset form‑factor, battery chemistry choice and service models.
- Raw material and supply chain noise: While cordless handset batteries historically rely on NiMH chemistry (with Li‑ion relevance limited in this low‑power category), broader rechargeable battery market dynamics—and geopolitical pressure on critical minerals—continue to shape supplier terms, lead times and contingency costs.
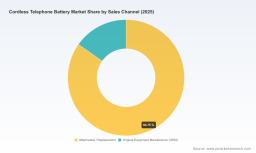
- Aftermarket resilience: Replacement and service channels remain a structural revenue anchor even as OEM refresh cycles slow. Companies that optimize distribution, warranty economics and refurbishment capture disproportionate share of lifetime handset economics.
Competitive landscape — what we observed
The sector is moderately concentrated: the top three and five players control a meaningful share of market revenues (our concentration metrics are included in the full report). Competitive dynamics are heterogeneous across the value chain:
- Retail and specialist aftermarket players (examples include national battery chains and ecommerce specialists) compete on inventory breadth, in‑store service and rapid fulfillment capabilities. Their strategic advantage lies in brand trust, channel density and aftermarket warranty services.
- Large cordless handset OEMs maintain integrated supply lines for original batteries and benefit from product bundling, but they face exposure to compliance costs and to the declining absolute growth of the handset base.
- Component and pack manufacturers—including global Chinese contract suppliers and established rechargeable battery firms—operate across OEM and aftermarket channels. Their bifurcated business models create both volume scale and specialized niche opportunities (e.g., custom packs for DECT handsets or higher‑cycle replacements for enterprise deployments).
Profiles of the major firms reviewed in the report include strengths, distribution reach, channel strategies and vulnerability mapping. We analyze U.S. aftermarket specialists known for replacement compatibility and retail presence, regional handset brands with proprietary pack integration, and global cell/pack manufacturers with export footprints. The report evaluates where each firm is positioned on the spectrum from commoditized replacement products to differentiated system suppliers.
Recent developments and strategic implications
- EU Ecodesign (effective June 2025): Short‑term winners are firms that rapidly certify models and offer retrofit/upgrade paths; losers are supply‑chain constrained OEMs with large inventories of non‑conforming models. Practical action: prioritize compliance testing, develop trade‑in/refurb programs, and pre‑empt enforcement via voluntary labeling.
- DECT NR+ standard updates (2025): Opens new product pathways for higher‑value handsets; practical action for OEMs and battery suppliers: align roadmaps on energy management, fast charging profiles, and handset power budgets.
- Product launches (e.g., portable DECT devices introduced in 2025): Signal continued niche innovation and point to opportunities for battery suppliers to co‑develop packs tailored to evolving handset capabilities.
What the report delivers — practical, operational outputs
This is not a descriptive study. The report is structured as a decision tool for 2026 executives and includes:
- A flexible financial model (Excel) that allows users to run sensitivity analyses across demand, price and raw‑material inputs and project P&L and working capital impacts under alternative regulatory and technology scenarios.
- Actionable go‑to‑market playbooks for OEMs, aftermarket retailers and specialist pack manufacturers covering inventory optimization, warranty economics, refurbishment programs, and channel pricing strategies.
- Supply‑chain heatmaps and supplier scorecards that prioritize dual‑sourcing, quality audits and nearshoring levers—each with step‑by‑step mitigation tactics and estimated implementation timelines.
- Competitive scorecards and acquisition targets: risk‑adjusted valuation heuristics for potential M&A targets, plus integration checklists to accelerate value capture post‑deal.
- Regulatory matrix: country‑by‑country compliance checkpoints, testing timelines and cost envelopes to help procurement and regulatory teams plan certification and labeling programs in 2026.
- Scenarios calibrated to the reported market forecast and concentration metrics, showing paths under faster DECT NR+ adoption, aggressive ecodesign enforcement, or raw‑material price escalation.
Strategic recommendations for 2026
- Prioritize compliance and warranty redesign: Treat ecodesign compliance as a market access and customer‑retention initiative. Design replacement and refurbishment programs that monetize regulatory upgrades and reduce trade‑in friction.
- Segment channel strategies: Protect aftermarket revenue with faster fulfillment, certified replacement SKUs and turnkey warranty services; for OEMs, selectively pursue premium DECT NR+-enabled handsets that justify higher ASPs and recurring accessory sales.
- De‑risk supply chains: Actionable steps include dual‑sourcing key pack assemblies, negotiating price‑index clauses for key raw materials, and piloting regionalization for critical SKUs to reduce tariff and logistics exposure.
- Invest in product differentiation where it pays: In low‑growth markets, differentiation beat scale—battery vendors should offer validated higher‑cycle packs, extended‑warranty programs and co‑branded service offerings with handset OEMs and retailers.
- Use M&A tactically: Acquire access to distribution or complementary service capabilities rather than pure cell capacity; small bolt‑on acquisitions can accelerate aftermarket penetration and provide immediate customer insight for cross‑sell.
How PW Consulting can accelerate your 2026 program
Clients who engage PW Consulting receive tailored scenario workshops, model recalibration to reflect their portfolio and a two‑week rapid audit of their supply chain and certification posture. For teams preparing 2026 budgets, we translate the report’s scenario outputs into an executable 90‑day action plan with KPIs, estimated capex/Opex impact and prioritized vendor shortlists.
Next steps — where to find the missing detail
This briefing outlines the strategic contours and operational implications for 2026. To preserve the high value of our proprietary segmentation work and the detailed tables that underpin targeted plays, we have deliberately omitted granular regional and application splits here. The full report contains those segment tables, unit and revenue breakouts, company scorecards and the downloadable financial model referenced above. Visit the PW Consulting report page to access the complete dataset, appendices and implementation toolkit.
For executive briefings, model walkthroughs or to commission a bespoke scenario tailored to your portfolio and supply chain footprint, contact PW Consulting’s industry practice. Our team will help you convert the market’s modest headline movement into differentiated, defensible value in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Cordless Telephone Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com