

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Veterinary Glucometers Market to Expand from USD 545.6 Million in 2025 to USD 926.01 Million by 2032 at a 7.85% CAGR
By pmarketresearch, 2026-07-15
Worldwide Veterinary Glucometers Market: Strategic Imperatives for 2026 — PW Consulting Preview
PW Consulting today releases a strategic preview of our upcoming Worldwide Veterinary Glucometers Market report. Built from a multi-year primary and secondary research program and grounded in a rigorous financial model, this analysis synthesizes market performance through 2025 and projects commercial dynamics across a 2026–2032 forecast window. The aim of this preview is to equip executive teams with the high‑level signals they need to prioritize investments, partnerships, and product strategies in 2026—while reserving detailed segment-level tables and proprietary scenario outputs for the full report.
Worldwide Veterinary Glucometers Market
Executive summary: why 2026 matters
The veterinary glucometers market has moved from niche clinical utility to a mainstream component of companion‑animal diabetes care, driven by rising diagnosis rates, growing owner willingness to manage chronic conditions at home, and accelerating clinic adoption of continuous glucose monitoring (CGM) modalities. Our market model shows steady expansion between 2020 and 2025 and anticipates continued growth through 2032 at a compound annual growth rate (CAGR) that underscores attractive returns for focused investors and incumbents alike.
Worldwide Veterinary Glucometers Market
For 2026 specifically, several convergent forces create a window of strategic opportunity: (1) technological maturation of pet‑specific CGMs that shift value from episodic point‑of‑care testing to ongoing data streams; (2) growing commercial acceptance of veterinary‑calibrated meters versus off‑label human devices; and (3) a consolidating vendor landscape that rewards scale in distribution, clinical validation, and companion software ecosystems. Companies that move decisively on validation, channel partnerships, and differentiated service layers in 2026 are positioned to capture disproportionate share as the market expands.
Worldwide Veterinary Glucometers Market
Market trajectory: headline macro metrics
- Established base and recent performance: Our model tracks the market from 2020 through 2025, documenting consistent growth and a clear inflection toward broader clinical and home adoption in the last two years.
- Forecast posture: The marketplace is forecast to expand through 2032 at a mid‑single‑digit to high‑single‑digit CAGR, reflecting both unit growth and increasing ASPs for clinic‑grade continuous monitoring solutions and integrated data services.
- Structure: Market concentration is meaningful—top regional and global providers collectively command a majority share, creating both barriers to entry and attractive consolidation targets for buyers seeking scale.
Note: This preview conveys high‑level macro metrics and directional analysis. Detailed segment, regional, and sub‑product financials are proprietary and available in the full PW Consulting report.
What the full report delivers (practical, executable content)
- Transparent methodology and model inputs: line‑by‑line assumptions, primary interview summaries, and sensitivity scenarios for differing adoption curves.
- Market sizing and forecast model (2020–2032) with downloadable spreadsheets and scenario toggles for pricing, adoption, and clinical reimbursement shifts.
- Commercial playbooks by product class (handheld meters, clinic‑direct CGMs, hybrid models) describing go‑to‑market routes, pricing stratification, and promotions that move the needle in 12–24 months.
- Regulatory and validation roadmap: practical checklists and study designs that vendors should execute to substantiate species‑specific accuracy claims and to accelerate clinic adoption.
- Competitive profiles and capability maps for leading manufacturers, distributors, and emerging CGM specialists—covering product claims, channel strategy, IP posture, and recent commercial moves.
- M&A and partnership heatmap with recommended target archetypes by strategic objective (technology, channel, clinical validation, geographic expansion).
- Service and data monetization frameworks capturing recurring revenue levers from apps, telemetry, population analytics, and integrated care programs.
Competitive landscape: what incumbents and newcomers are doing
The competitive picture is a blend of traditional animal health majors, specialized diagnostic firms, and technology‑first CGM entrants. Leaders differentiate on three axes: species‑specific calibration and accuracy, clinic vs. home usability, and software/data ecosystems that connect pet owners with veterinarians.
- Zoetis has positioned its AlphaTrak line with species‑specific algorithms and a companion mobile app—anchoring clinical credibility and owner engagement. This combination strengthens its defensibility in companion‑animal markets where clinical accuracy and small sample requirements matter.
- Specialized meter manufacturers (regional and global players) focus on veterinary calibration, sampling ergonomics for pets, and multi‑pet profile management—attributes that matter to high‑volume clinics and specialty practices.
- CGM newcomers are converging on clinic‑direct deployments and partnership distribution through major animal health distributors. Several CGM systems designed specifically for pets are transitioning from pilot to broader clinic release, representing a potential inflection point in chronic care management.
- Cross‑market noise persists: human flash sensors are used off‑label in practice, but lack formal veterinary approvals and manufacturer support; this creates intermittent demand leakage but also regulatory and liability debate that savvy companies can exploit by emphasizing veterinary certification.
Recent industry moves illustrate these themes. A leading CGM developer completed internal manufacturing testing at the end of 2025 and plans controlled relaunches into Canada and the US in early 2026, signaling that high‑quality pet CGMs are entering scaled commercialization. Earlier product launches with integrated mobile applications set the template for vendor value‑propositions that blend accuracy, owner engagement, and clinic workflows.
Regulatory and clinical validation dynamics
Regulatory and technical validation is now table stakes. Devices intended for veterinary use must demonstrate species‑specific accuracy validated against laboratory reference methods—often referencing human standards where applicable but with animal‑matrix verification. Expectations for small sample volumes, robust repeats in clinic conditions, and clearly documented performance across common companion species are rising. For vendors, investing in head‑to‑head clinical studies, published validation, and third‑party verification will accelerate adoption and mitigate off‑label substitution.
2026 strategic playbook — recommendations by priority
- Prioritize clinical validation now: Accelerate species‑specific accuracy studies and publish outcomes. Buyers and clinics reward documented performance over marketing claims.
- Move from product to platform: Pair hardware with software capabilities that enable shared decision‑making between owners and veterinarians—data visualization, alerts, and population analytics create lock‑in and recurring revenue potential.
- Choose distribution partners deliberately: Clinic‑direct channels and specialist distributors dominate CGM rollouts; negotiate co‑marketing, training, and data‑sharing agreements to secure preferential placement.
- Segment go‑to‑market based on use case: Offer clear clinical bundles for diabetes management in high‑acuity clinics and simplified, lower‑friction options for home use to capture the full care pathway.
- Consider M&A or partnership to bridge gaps: With market concentration substantial among the top players, acquiring niche technology or securing exclusive distribution can leapfrog organic scale constraints.
- Prepare manufacturing and supply chain resilience: Plan for component lead times and validation cycles; early capacity commitments reduce time‑to‑market risks for 2026 launches.
Investment and M&A outlook
Market consolidation and technology differentiation create a compelling environment for private equity and strategic acquirers. Buyers should prioritize targets that bring either validated clinical advantage (species‑calibrated CGM or meter accuracy) or distribution advantages (established clinic networks and digital customer bases). The concentration dynamics mean that carefully executed tuck‑ins and distribution partnerships can rapidly improve margin profiles and accelerate cross‑sell of consumables and software subscriptions.
Using this preview in your 2026 planning cycle
Executives should treat this preview as a decision‑support prompt: use the macro growth trajectory and adoption drivers documented here to stress‑test 2026 capital allocations, R&D roadmaps, and channel investments. For product teams and business development leaders, the immediate tactical actions are clear—accelerate clinical validation, finalize distribution pilots, and bundle software capabilities that convert passive device buyers into recurring revenue relationships.
Next steps and how to access the full analysis
PW Consulting’s full Worldwide Veterinary Glucometers Market report contains the detailed segment and regional breakdowns, vendor revenue splits, pricing curves, and downloadable models that senior teams use to build 2026 budgets and board‑level investment cases. The full dataset includes scenario outputs that model alternative adoption speeds for CGM, price erosion curves for strip‑based revenue, and sensitivity analyses for regulatory shifts.
To request the full report or arrange a briefing with our industry analysts, visit the PW Consulting website or contact our research desk. Our team can provide tailored slices of the model and a private workshop to translate findings into a 90‑day action plan for commercialization, partnership pursuit, or transaction screening.
Closing perspective
The veterinary glucometers market presents a rare combination of clinical necessity, product innovation, and consolidating distribution—creating a multi‑year runway for strategic players who move with purpose in 2026. Whether you are an incumbent seeking to defend share, a device innovator preparing a launch, or an investor evaluating M&A, the decisions made this year will determine who leads the next phase of growth. PW Consulting’s full report equips leaders with the quantitative detail and executable playbooks required to make those decisions with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Veterinary Glucometers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Conjunctivitis Ophthalmic Drugs Market to Grow from USD 5,466.5 Million in 2025 to USD 7,952.01 Million by 2032 at a 5.51% CAGR
By pmarketresearch, 2026-07-15
Worldwide Conjunctivitis Ophthalmic Drugs Market — Strategic Briefing for 2026 Decision-Makers
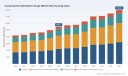
PW Consulting’s latest market study on the Worldwide Conjunctivitis Ophthalmic Drugs Market synthesizes five years of historic performance and a seven‑year forecast horizon to equip executive teams with the strategic intelligence they need for 2026. The conjunctivitis therapeutics market has expanded steadily from approximately USD 4.21 billion in 2020 to an estimated USD 5.47 billion in 2025, and our base‑case forecast (2026–2032) projects a compound annual growth rate (CAGR) of 5.51%, reaching roughly USD 7.95 billion by 2032. These headline metrics frame a resilient growth narrative — but the competitive and regulatory dynamics underneath that topline are what will determine winners and losers in the coming 18–36 months.
Worldwide Conjunctivitis Ophthalmic Drugs Market
Why this matters for 2026 planning
-
Budgeting & resource allocation: With mid‑single‑digit CAGR and clear upside to 2032, biopharma and ophthalmic device teams should prioritize initiatives that capture sustainable share versus short‑term volume plays that are vulnerable to price erosion.
Worldwide Conjunctivitis Ophthalmic Drugs Market -
M&A and licensing windows: Moderate market concentration (CR3 ≈ 42.5%; CR5 ≈ 58.8%) signals that top firms hold meaningful scale but that gaps remain for targeted acquisitions, geographic rollouts, or specialty product in‑licensing to materially move the needle.
Worldwide Conjunctivitis Ophthalmic Drugs Market -
Reimbursement & access strategy: Product form (drops vs. inserts vs. sustained‑release), pediatric labeling, and payer position will be as determinative of commercial success as clinical differentiation.
Market trajectory — reading the topline
The market’s recovery and growth since 2020 reflect both demand elasticity in allergy and infectious disease care pathways and an expanding set of therapeutic modalities (traditional drops, preservative‑free formulations, inserts, and sustained‑release systems). Growth drivers include rising allergy prevalence in urbanized populations, continued uptake of branded innovations where clinically differentiated, and steady replacement of older therapies with preservative‑free or higher‑convenience options. Against that backdrop, generics and biosimilar entrants create persistent pricing pressure in commoditized segments.
For 2026, expect continuing mid‑single‑digit compound growth — supportive of disciplined commercial investments but not of undirected broad launches. Detailed scenario modelling in our report shows that incremental market share gains from either a differentiated branded asset or a cost‑effective generic play can have asymmetric value depending on channel access and payer coverage outcomes.
Competitive dynamics — what incumbents and challengers are doing
The competitive set blends large integrated players, specialist ophthalmic firms, and agile generics manufacturers. Industry leaders continue to push on three vectors: product differentiation, delivery technology, and geographic breadth. Notable players covered in our analysis include Alcon, Bausch + Lomb (Bausch Health), AbbVie (Allergan), Novartis, Santen, Pfizer, Nicox, Sun Pharma, Alembic, and Ocular Therapeutix. Each pursues a distinct strategic posture — from Alcon’s strong allergy portfolio to Santen’s specialization in pediatric and severe allergic indications, and from Sun Pharma’s generics scale to Ocular Therapeutix’s device‑enabled delivery approach.
Recent industry developments are illustrative of momentum and disruption: generic launches of established anti‑infective agents and anti‑allergy molecules continue to compress pricing in commoditized categories; selected regulatory approvals and label expansions for novel delivery formats have opened niche clinical and commercial opportunities; and regulatory approvals in major emerging markets have created new addressable segments for specialist products. Our report integrates these events into competitive scenarios, assessing their likely impact on revenue curves, margin trajectories, and bargaining power with payers and distributors.
Regulatory, patent and reimbursement levers — implications for strategy
-
Regulatory labeling nuances (including pediatric use constraints) materially affect product positioning. For example, intracanalicular inserts offer differentiated adherence and convenience benefits, but pediatric insertion requirements and payer treatment policies limit near‑term adoption unless procedural workflows and reimbursement codes are addressed.
-
Patent expiries and generic availability are compressing value in selected molecule classes; companies with heavy exposure to those molecules must accelerate lifecycle plans (reformulation, device pairing, or new indications) to preserve pricing.
-
API supply diversity for key molecules is both a risk mitigation factor and a competitive enabler. Securing multi‑sourced APIs and manufacturing capacity should be part of 2026 operational planning to avoid shortages or cost shocks.
Key strategic moves for 2026
-
Segmented go‑to‑market: Prioritize channels and therapeutic niches where your product’s attributes (efficacy, safety, dosing convenience, pediatric label) map to payer and clinician willingness‑to‑pay. Avoid one‑size‑fits‑all launches in an environment of selective coverage.
-
Defend and extend: For brands facing imminent generic competition, accelerate lifecycle actions — Rx‑to‑OTC switches where applicable, preservative‑free reformulations, fixed‑dose combinations, or device‑enabled delivery — that create new value not easily replicated by pure generics.
-
Partnerships & bolt‑ons: Use M&A selectively to fill capability gaps (e.g., sustained‑release technologies, pediatric formulations, regional registration expertise). Given the market’s moderate top‑end concentration, well‑timed bolt‑ons can lift commercial scale meaningfully.
-
Access engineering: Invest in reimbursement dossiers and procedure code strategy for insertable and sustained‑release products. Early payer engagement and real‑world evidence generation can accelerate uptake and justify premium pricing.
-
Supply resiliency: Build redundancy across API suppliers and leverage contract manufacturing partners to manage cost volatility and fulfilment timelines, especially for sterile ophthalmic products where regulatory audits and quality issues can create supply interruptions.
What PW Consulting’s report delivers — practical outputs for teams
Our report is designed not as a pure market narrative but as an executable intelligence package for 2026 planning cycles. Deliverables include:
-
A validated topline forecast with sensitivity scenarios (base, conservative, upside) through 2032, with transparent modelling assumptions.
-
Competitive profiling and strategic heatmaps for leading and emerging players, assessing R&D pipelines, commercial footprints, and likely strategic moves.
-
Regulatory & reimbursement impact matrices, including pediatric labeling constraints, insertable device reimbursement pathways, and patent‑expiry timelines that drive risk‑adjusted cash‑flow projections.
-
Go‑to‑market playbooks tailored by product archetype (branded differentiated, generic cost leader, device‑enabled therapy), complete with launch sequencing, payer engagement templates, and HCP targeting frameworks.
-
M&A screening criteria and valuation sensitivity tables for targets across the value chain (specialty ophthalmics, delivery technology, CMOs).
-
Operational checklists covering API sourcing, sterile fill/finish readiness, and quality compliance priorities to de‑risk supply interruptions.
How different stakeholders should use the intelligence in 2026
-
Executive teams: Use the report to set portfolio prioritization and budget envelopes, aligning R&D funnel gating with commercial realities implied by the market growth path.
-
Commercial leaders: Adopt the playbooks to refine channel strategies and to shape payer value messaging, especially for products with procedural requirements or pediatric considerations.
-
Business development & M&A teams: Apply our screening filters and valuation sensitivity work to identify bolt‑on targets that de‑risk launches or accelerate entry into underserved therapeutic niches.
-
R&D and medical affairs: Leverage the regulatory and evidence roadmaps to prioritize studies that unlock label expansions and payer coverage (e.g., real‑world adherence, pediatric safety).
Limitations & where to go next
Our briefing intentionally focuses on strategic implications and high‑level market trajectory. For clients requiring granular subsegment breakdowns (by drug class, disease type, and geographic revenue splits), line‑by‑line forecasts, or custom scenario modelling tied to proprietary assets, the full PW Consulting dataset and modelling workbook provide the necessary granularity — including segment P&Ls, price‑volume elasticity assumptions, and payer‑by‑country reimbursement scenarios. This “paywall” approach is deliberate: we provide the strategic narrative here to inform 2026 decision frameworks while directing teams that need executable numbers to the full deliverable.
Conclusion — a 2026 playbook in one paragraph
Conjunctivitis therapeutics is a market of predictable growth but nuanced opportunity. With an expected mid‑single‑digit CAGR and a near‑term market size comfortably above the mid‑single‑billion USD range, 2026 is the year to convert strategic intent into operational commitments: defend franchise value against generics, pursue targeted M&A to fill capability gaps, harden supply chains, and build payer evidence that unlocks premium pricing for differentiated formulations and delivery systems. PW Consulting’s full report arms leaders with the models, scenarios, and playbooks to make those decisions with confidence.
For access to the full dataset, segment‑level forecasts, and customizable scenario modelling kits, please contact PW Consulting’s Healthcare Strategy practice to arrange a briefing and download the full Worldwide Conjunctivitis Ophthalmic Drugs Market report.
For detailed analysis of this topic, please visit the official page: Worldwide Conjunctivitis Ophthalmic Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Ovum Egg Banking Market Set to Expand at a Robust 12.48% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Ovum Egg Banking Market: Strategic Imperatives for 2026 — Executive Preview
Introduction
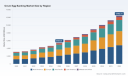
As organizations prepare their 2026 strategic plans, the ovum (egg) banking market presents a high-growth set of opportunities and operational challenges that demand disciplined, forward-looking decisions. PW Consulting’s latest Worldwide Ovum Egg Banking Market report (base year: 2025; historical: 2020–2025; forecast: 2026–2032) synthesizes market dynamics, regulatory headwinds, reimbursement realities, and competitive positioning into a pragmatic playbook for private- and public-sector stakeholders. The market is expanding rapidly — our modelling shows total industry revenue growing from USD 3,120.45 million in 2020 to USD 5,464.34 million in 2025, and we project continued acceleration through the forecast window, reaching approximately USD 12,462.51 million by 2032 at a compound annual growth rate (CAGR) of 12.48% (USD Million). This preview explains why 2026 is a pivotal year for portfolio repositioning, capability investments, and policy engagement.
Worldwide Ovum Egg Banking Market
Why 2026 Is a Pivot Point
-
Market momentum and validation: Clinical programs and outcome data reported in 2025–2026 (notably increased live-birth reports from active banking programs) are reducing the uncertainty that historically constrained broader consumer adoption. This clinical validation is helping convert early-adopter demand into mainstream patient uptake and employer-sponsored benefits.
Worldwide Ovum Egg Banking Market -
Regulatory and ethical clarity: Recent updates from professional bodies have materially changed the policy backdrop. The American Society for Reproductive Medicine (ASRM) has issued a sequence of updated opinions and practice guidance affirming planned oocyte cryopreservation as ethically permissible when disclosed informed consent addresses efficacy uncertainties. These statements reduce professional risk and open avenues for broader clinical program expansion and payer discussions.
Worldwide Ovum Egg Banking Market -
Reimbursement and coding realities: The presence of CPT codes for oocyte cryopreservation (including codes for cryopreservation and thawing procedures) creates a technical path toward standardized billing, even as donor-egg and elective services remain largely out-of-pocket today. Markets where fertility-preservation mandates exist for oncology patients already demonstrate asymmetric uptake — presenting both ready demand and a template for policy advocacy in other jurisdictions.
High-Level Market Trajectory and Strategic Consequences
Our topline modelling demonstrates a sustained step-up in total market value between 2025 and 2032, supporting a thesis that the ovum banking industry is transitioning from niche clinical service to scaled healthcare offering. For 2026 corporate planning, this trajectory implies three actionable priorities:
-
Scale and reliability: Invest in infrastructure — cryostorage capacity, validated logistics, and quality management systems — to capture volume-driven margin improvements as demand expands.
-
Regulatory-compliant commercialization: Build cross-functional programs that align clinical pathways, informed-consent frameworks, and reimbursement navigation to reduce friction for clinic partners and patients.
-
Product & service bundling: Develop bundled offerings (preservation + fertility counseling + storage + thaw/transfer coordination) to increase lifetime value and reduce churn.
What the Report Contains — Actionable Intelligence (Not Just Data)
This study is designed for decision-makers who require executable insight rather than raw tables. Key deliverables include:
-
Integrated market model (historical and forecast) with scenario variants that reflect differing adoption curves, reimbursement shifts, and pricing sensitivity.
-
Commercial due-diligence toolkits: go-to-market playbooks for clinic networks, private cryobanks, and new entrants; channel economics; and pricing elasticity guidance.
-
Regulatory and reimbursement mapping: a practice-oriented guide to CPT coding, payer engagement strategies, and advocacy roadmaps for extending mandates beyond current medical-indication use cases.
-
Competitive benchmarking: company scorecards, capability heatmaps (clinical throughput, geographic reach, digital donor search, logistics), and acquisition target shortlists.
-
M&A & partnership playbook: valuation sensitivities, operational integration checklists, and risk matrices tailored to this fragmented market structure.
-
Clinical and quality operations playbook: SOPs for vitrification and long-term storage, traceability and chain-of-custody protocols, and sample-quality monitoring frameworks.
Competitive Landscape — Fragmentation Presents Opportunity
The ovum egg banking sector remains meaningfully fragmented: the three largest players account for a relatively modest share of the market, and the top five likewise leave substantial market to specialized and regional providers. That structure creates room for multiple strategic moves:
-
Specialist cryobanks (examples include longstanding providers that focus on donor egg logistics and searchable inventories) are prime partners for fertility clinic networks and hospital systems that wish to outsource operational complexity.
-
Large fertility chains and multi-site clinic operators benefit from integrating banking services to capture referral flows and bundle peri-procedural care.
-
Cross-border distributors and international networks remain important for donor egg availability and sourcing; therefore, control over validated logistics and legal compliance is a valuable competitive moat.
Representative organizations profiled in the report include established global cryobanks, national leaders in donor egg services, clinic networks with integrated programs, and innovative entrants focusing on accessibility and consumer engagement. Each profile includes a strategic assessment of where the enterprise is positioned in the value chain, likely near-term moves, and risk exposure (regulatory, operational, reputational). The report deliberately validates these company profiles against publicly reported service portfolios and clinical milestones, offering readers a pragmatic lens for partnership or acquisition screening.
Regulatory, Clinical, and Reimbursement Dynamics
Two converging regulatory trends are central to 2026 planning. First, professional guidance has shifted towards acknowledging oocyte cryopreservation as a legitimate option for preserving reproductive potential, contingent on informed consent and transparent communication of uncertainties. Second, technical billing pathways exist (e.g., specific CPT codes for cryopreservation and thawing), but payer coverage remains fragmented — particularly for donor and elective services.
These dynamics imply a bifurcated near-term playbook: scale medical-indication programs where mandates or clear payer pathways exist, while concurrently investing in consumer marketing, employer benefits partnerships, and financing solutions to address out-of-pocket barriers for elective uptake.
Technology, Quality, and Logistical Imperatives
Operational excellence is a competitive differentiator. Key areas where the report identifies measurable ROI include:
-
Standardization of vitrification protocols and cross-lab quality controls to reduce variability in outcomes and support credible outcome reporting.
-
Investment in digital donor-search platforms and API-enabled clinic integrations to shorten lead times and improve matching efficiency.
-
Robust cold-chain logistics and contingency governance for long-term storage, transfer, and cross-border shipments — an often-overlooked source of operational risk.
Strategic Playbook — Recommended 2026 Actions
-
Pursue selective vertical integration: clinics should evaluate partial ownership or exclusive supply agreements with cryobanks to secure inventory and control margins.
-
Design payer pilots: target oncology-preservation pathways and employer-sponsored fertility benefits as initial pilots for demonstrable cost-offset studies and utilization controls.
-
Accelerate clinical outcome transparency: collect and publish reliable cohort data to reduce patient uncertainty and support marketing and payer discussions.
-
Use M&A to buy capabilities, not just capacity: prioritize targets with validated quality systems, digital donor catalogues, or regional regulatory approvals that would take longer to build organically.
Risks and Mitigants
Key risks include regulatory reversals or tightened consent standards, slow reimbursement expansion for elective services, and operational incidents affecting sample integrity. The report provides a risk-quantified mitigation matrix and operational playbooks to minimize single-point failures and accelerate time-to-recovery.
Conclusion — The Strategic Upside
PW Consulting’s analysis indicates that ovum egg banking is moving from a specialist clinical niche toward a structured, scalable healthcare segment. Revenue growth projections and clinical validation trends support investment in capacity, digital enablement, and payer engagement in 2026. At the same time, market fragmentation and modest concentration ratios create a buyer-friendly environment for consolidation, selective partnerships, and capability acquisition.
This preview is designed to guide executive prioritization. For licensed subscribers and decision-makers seeking the full granular intelligence — including downloadable model files, confidential company scorecards, scenario modeling spreadsheets, and regulatory-by-jurisdiction appendices — please consult the full report on our publication page. The full dataset contains the detailed segment and regional breakdowns, which are intentionally omitted here to preserve the strategic value of the source intelligence.
For detailed analysis of this topic, please visit the official page: Worldwide Ovum Egg Banking Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Organic Maple Syrup Market to Expand at a 7.02% CAGR — Sweet Growth Ahead
By pmarketresearch, 2026-07-15
Worldwide Organic Maple Syrup Market — Strategic Outlook for 2026
Executive summary
PW Consulting’s latest Worldwide Organic Maple Syrup Market report (base year 2025, historical series 2020–2025, forecast 2026–2032) equips senior executives and commercial teams with the forward-looking intelligence required to make high-impact decisions in 2026. The market reached approximately USD 585.5 Million in 2025 and – on the trajectory captured in our model – is projected to grow at a compound annual growth rate (CAGR) of 7.02% across the 2026–2032 forecast window, arriving near USD 941 Million by 2032 under our central-case assumptions.
Worldwide Organic Maple Syrup Market
These headline numbers mask a more nuanced competitive and operational landscape: supply-side expansion plans, evolving certification and stewardship requirements, buyer behavior shifts on organic premiums, and persistent labor and infrastructure constraints are all combining to make 2026 a pivotal year for strategic repositioning. Our report synthesizes these dynamics into an actionable playbook for market entry, procurement, product strategy, and M&A prioritization.
Worldwide Organic Maple Syrup Market
Why 2026 matters — the strategic inflection points
-
Supply reconfiguration: Larger producers in the U.S. have signaled meaningful capacity growth, with some operators planning double-digit expansions of tap count and processing capability. Notably, industry reporting indicates a significant portion of planned new production is intended to be certified organic — a structural shift that will influence supply elasticity and the availability of certified inventory in the near term.
Worldwide Organic Maple Syrup Market -
Premium compression risk: Major buyers and processors are already signaling a reassessment of organic pay premiums for 2026. As certified volumes grow, organizations that previously relied on consistent organic premiums will face margin pressures unless they refresh sourcing strategies or add differentiated consumer-facing propositions.
-
Regulatory and certification complexity: Organic maple syrup certification is not a simple label — in the U.S., it is tightly linked to forest stewardship plans, limits on synthetic inputs, and prescribed operational practices (e.g., permitted defoaming agents). Parallel governance structures in Canada — including production quotas and strategic reserves managed by producer federations — add an additional layer of supply-side modulation that will shape export flows and availability.
-
Capital and operational efficiency: The mix of labor shortages and increased investment in processing technologies (reverse osmosis, automated tapping systems, modern evaporators) is changing unit economics. Producers who accelerate technology upgrades under organic-compliant specifications will gain cost and scale advantages.
What the report delivers — practical, decision-ready content
-
Integrated market model: top-down and bottom-up views, historical validation (2020–2025), and scenario-driven forecasts for 2026–2032 including sensitivity to tap-count growth, certification conversion rates, and premium erosion.
-
Supply-demand scenarios: three actionable cases (conservative, central, upside) that model how certification adoption, quota management, and strategic reserve releases affect pricing and availability.
-
Price-formation and contract playbooks: guidance on term structures, indexation clauses, and performance KPIs for procurement teams to manage premium volatility and inventory risk.
-
Operational checklist for organic compliance: practical steps for forest stewardship planning, permitted inputs, audit readiness, and traceability systems aligned with MOFGA/VOF/MOSA and comparable certification bodies.
-
Route-to-market and SKU strategies: roadmaps for premium single-origin positioning versus co-packing/industrial blends, including recommended packaging, shelf-space tactics, and foodservice channel entry plays.
-
M&A and partnership frameworks: screens and valuation heuristics for bolt-on acquisitions, co-op partnerships, and long-term offtake arrangements with larger processors and distributor networks.
-
Risk matrix and early-warning indicators: a monitoring dashboard of 12 leading indicators (tap counts, certification applications, distributor inventory days, buyer premium signals, PPAQ reserve movements) to anticipate price inflection and supply imbalances.
-
Competitive benchmarking: strategic profiles, capability maps and scenario readiness assessments for the sector’s leading producers and processors.
Competitive landscape — strategic takeaways on the core players
-
Coombs Family Farms (Brattleboro, VT) — Multi-generational brand equity and broad retail reach are core strengths. Expect Coombs to continue leveraging brand-led premium positioning while selectively pursuing scale opportunities through contract packing and private label agreements.
-
Butternut Mountain Farm (Morrisville, VT) — Significant processing capacity and global distribution give this player an advantage in converting increased tap-count supply into commercially available certified inventory. Scale offers negotiating leverage with large buyers, but exposure to premium compression is material.
-
Crown Maple (Dover Plains, NY) — Premium single-origin positioning and tourism/brand experience create resiliency for retail price premiums. Their model is less sensitive to volume-driven price swings but depends on a sustained consumer willingness to pay.
-
Bascom Maple Farms — As a major independent buyer-processor, Bascom’s role as a consolidator of raw certified supply makes it a bellwether for bulk market dynamics and industrial channel flows.
-
Quebec Producers (e.g., Escuminac, LB Maple Treat, NuCAN) — Quebec-based processors and cooperatives remain structurally important to global supply. The federation-level quota and reserve mechanisms in Canada can quickly alter exportable certified volumes; monitoring these policies is essential for procurement planning.
-
Cooperatives and smaller specialist producers (Maple Valley Cooperative, Baird Farm, Sap Hound) — These organizations offer high traceability and local stewardship stories attractive to premium channels. They are also potential partners for co-development and secure long-term offtake.
Recent developments to watch (implications for 2026 tactics)
-
Industry reporting in early 2026 indicates sizable expansion plans among larger U.S. producers, with a significant share of that new capacity intended to carry organic certification. This will shift supply composition and may accelerate premium normalization in 2026.
-
New product certifications and trade show activity by specialist brands in 2025–2026 show continued retail innovation and category momentum. Brands converting conventional SKUs to certified organic should be treated as both competitors and potential collaborators for capacity aggregation.
-
Production statistics confirming robust output from states such as Maine underline that North American organic supply remains foundational; buyers should stress-test contracts against regional harvest cycles and cross-border logistic friction.
Recommended strategic moves for executives in 2026
-
Adopt a dual-track procurement strategy: secure near-term volumes with flexible indexed contracts while investing in strategic long-term offtake agreements with certified producers to lock in quality and traceability.
-
Negotiate premium de-risking clauses: include volume-tiered premiums, quality-adjusted rebates, and inventory carry provisions to limit exposure to rapid premium compression.
-
Invest selectively in traceability and stewardship verification to protect brand claims and command differentiated pricing for single-origin or high-stewardship SKUs.
-
Prioritize capital allocation to processing upgrades (reverse osmosis, energy-efficient evaporators) where organic-compliant practices can materially reduce per-unit cost.
-
Scan for strategic M&A or partnership targets among regional co-ops and independent processors to consolidate supply and secure access to certified volume without sole dependence on commodity spot markets.
-
Deploy a demand strategy that mixes premium retail storytelling with industrial channel penetration where higher volumes can offset narrower margins.
Market structure note and how we treat granular data
Our concentration analysis shows a moderately consolidated market: the top three players represent a material share of commercial activity, while the top five further increase sector concentration. We intentionally present our public commentary at a strategic level — the full report contains the granular regional, grade, and channel splits, buyer-level pricing matrices, and downloadable scenario models that underpin the analyses summarized here. These core segment figures are omitted from this release to preserve the report’s commercial value and to encourage direct access to the full dataset for decision-makers.
Call to action
For procurement leads, corporate strategy teams, private equity investors, and supplier management functions preparing plans for 2026, this report provides the quantitative models, operational checklists, and competitive intelligence necessary to convert market signals into decisive action. Access the full Worldwide Organic Maple Syrup Market report to obtain the detailed segment-level data, supplier scorecards, and downloadable scenario models required to finalize budgets and contract negotiations for 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Organic Maple Syrup Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Application Security Solutions Market Poised for 17.22% CAGR, New Insight Report Finds
By pmarketresearch, 2026-07-15
2026 Strategic Primer: Worldwide Application Security Solution Market — PW Consulting Insights
Executive summary
As enterprises prepare budgets and roadmaps for 2026, application security (AppSec) is moving from checkbox compliance to strategic enabler. Our latest PW Consulting market study — the Worldwide Application Security Solution Market — synthesizes five years of historical trends and a seven-year forecast to deliver a decision-grade perspective for security leaders, product executives, and investors. The market is in a high-growth phase, underpinned by regulatory mandates, developer-centric tooling shifts, and rapid adoption of AI-native security capabilities. Our analysis quantifies the expansion trajectory and translates it into practical guidance for procurement, architecture, and go-to-market choices in 2026.
Worldwide Application Security Solution Market
Market trajectory: scale, pace, and what the numbers mean
At a macro level, AppSec is no longer a niche cybersecurity adjunct — it is a multi-billion-dollar, fast-scaling market. PW Consulting’s base-year assessment (2025) places the global AppSec market firmly in the double-digit billion-dollar range (USD, revenue measured in millions), with a compound annual growth rate of 17.22% through the forecast horizon. Our model projects a sustained acceleration driven by cloud-native development patterns, the industrialization of software supply-chain controls, and the commercialization of runtime protection models.
Worldwide Application Security Solution Market
For decision-makers, the headline metrics mean three practical things: (1) budget allocations for AppSec will expand materially relative to adjacent cybersecurity line items; (2) vendor consolidation and specialty plays will coexist — creating both integration risk and targeted opportunity; and (3) the pace of technology change requires procurement processes that favor agility, measurable ROI, and tight DevOps integration.
Worldwide Application Security Solution Market
Why 2026 is a pivotal year
Several contemporaneous forces converge in 2026 to make AppSec selection strategic rather than tactical. Regulatory pressure — notably new European software product security mandates and U.S. requirements for software transparency in federal supply chains — elevates baseline expectations for vulnerability disclosure, SBOMs, and secure-by-design practices. Operationally, organizations face a bifurcated threat landscape: legacy monolithic applications exhibit markedly higher exploit risk, while modern microservices and serverless architectures introduce complex runtime considerations.
Concurrently, AppSec tooling itself is evolving. The market is witnessing a rapid shift to AI-assisted vulnerability discovery and remediation: a majority of forward-looking organizations are incorporating GenAI into developer workflows for code security, with vendors releasing purpose-built remediation and code-scanning features that can reduce fix times and increase developer productivity. These innovations change the calculus of tool selection — emphasis shifts to integration fidelity with CI/CD pipelines, the quality of remediation guidance, and demonstrable reductions in mean time to remediate (MTTR).
What’s inside the PW Consulting report (practical, implementation-focused)
- Methodology and data foundations: transparent modeling approach covering historical 2020–2025 activity and a scenario-based forecast for 2026–2032.
- Executive playbooks: procurement and SOW templates for evolving AppSec programs, including KPI frameworks tied to DevSecOps metrics.
- Integration matrices: decision trees that map platform capabilities (SAST, DAST, IAST, SCA, RASP, API security) to common SDLC patterns and deployment architectures.
- Vendor scorecards and capability heatmaps: comparative assessments across product maturity, DevOps fit, AI/automation, and enterprise readiness (note: detailed scorecards and numerical rankings are available in the full report).
- Implementation accelerators: 30-, 90-, and 180-day adoption roadmaps for enterprise, mid-market, and regulated organizations, including a pilot-to-scale checklist.
- Economics and ROI models: configurable templates to estimate TCO, productivity gains from automated remediation, and breach-avoidance value.
- Regulatory and compliance playbook: mapping of major regional regulatory expectations to operational controls and reporting artifacts, with a focus on SBOMs and vulnerability-handling obligations.
Competitive landscape — how to read vendor roles in 2026
The AppSec ecosystem is stratified by platform breadth, developer orientation, and runtime capability. PW Consulting’s qualitative synthesis of vendor positioning identifies four archetypes:
- Integrated AppSec platforms — vendors who offer a full SDLC suite (static, dynamic, SCA, and increasingly IaC and API security) and aim for enterprise standardization across development teams.
- Developer-first innovators — lightweight, developer-integrated tools that prioritize fast feedback loops, IDE plugins, and frictionless onboarding to catch vulnerabilities early in the pipeline.
- Runtime and production defenders — solutions focusing on RASP and runtime monitoring to provide real-time detection and mitigation for live systems.
- Supply-chain and SCA specialists — platforms focused on open source governance, license compliance, and dependency risk management, especially relevant given SBOM mandates.
Representative vendors span these archetypes. Some provide broad suites that map well to centralized AppSec programs; others prioritize speed-to-fix and developer experience. Recent industry developments underscore this shift: vendors have launched AI-powered remediation engines that materially reduce time-to-fix, integrations with major code-assist tools to secure AI-assisted development, and strategic M&A to bolster supply-chain security capabilities. Additionally, a number of vendors have achieved or pursued cloud security authorizations that facilitate adoption in regulated and government environments.
Market concentration metrics show a mid-level consolidation pattern: a handful of incumbents hold meaningful shares, but there remains substantial room for specialization and new entrants. This dynamic is shaping commercial models — buyers can expect both scale benefits from large platform providers and targeted value from best-of-breed specialist vendors.
Strategic imperatives for 2026 — recommendations for leaders
- Embed AppSec in developer workflows, not just gate checks. Prioritize tools with IDE and CI/CD integrations and measurable developer productivity gains.
- Adopt an outcomes-first procurement metric set: reduce exploitable vulnerabilities in production, compress MTTR, and demonstrate SBOM coverage where required.
- Balance prevention and detection. Combine SAST/SCA investments early in the pipeline with runtime defenses to manage residual risk in production.
- Plan for AI-driven change. Evaluate vendor roadmaps for GenAI remediation, LLM integrations, and the controls necessary to trust AI-assisted fixes.
- Operationalize supply-chain visibility. Ensure that procurement and third-party risk functions can consume SBOMs and enforce policy through automated gates.
- Design for regulatory adaptability. Align controls to upcoming mandates to avoid costly rework and to use compliance as an accelerator for secure development practices.
90-day tactical blueprint
For executive teams needing immediate traction, PW Consulting recommends a focused, three-step 90-day plan:
- Week 1–3: Rapid landscape audit — map current AppSec tooling, identify overlap, and quantify key metrics (scan coverage, false-positive rates, MTTR).
- Week 4–8: Pilot selection — choose two tools from different archetypes for parallel pilot: one developer-first and one runtime/SCA specialist. Measure friction and remediation velocity.
- Week 9–12: Scale decision and governance — apply procurement templates, finalize KPIs, and define automated gates for CI/CD linked to SBOM and vulnerability thresholds.
Why this report matters to procurement, security, and product teams
PW Consulting’s study is designed to be operationally useful. Beyond market sizing and trend analysis, the report supplies procurement-ready artifacts, vendor diligence checklists, and configuration-level guidance that reduce time-to-decision. Importantly, it bridges board-level risk framing with developer-facing process design — enabling cross-functional buy-in for AppSec investments. For investors and M&A teams, the report highlights where consolidation and specialization will drive valuation premiums over the next three years.
Guiding principles for interpreting our findings
- Context matters: vendor fit is a function of application architecture, team skill sets, and regulatory exposure — there is no one-size-fits-all “market leader” for every enterprise use case.
- Measure what matters: move beyond raw vulnerability counts to business-aligned KPIs such as exploitability, time-in-state, and developer remediation velocity.
- Plan for adaptability: expect iterative retooling as AI features and regulatory definitions evolve; prioritize modular contracts and APIs for toolchain flexibility.
Next steps — where to get the full intelligence
This release is a strategic primer designed to orient 2026 decisions and to surface the immediate operational implications of a rapidly growing AppSec market. The full PW Consulting report contains detailed segmentation data, vendor scorecards, model assumptions, and downloadable implementation assets—insights that will materially shorten vendor selection cycles and implementation timelines. To access the complete dataset and proprietary appendices (including our region and solution splits, and the full list of ranked vendors), please visit the PW Consulting report landing page.
PW Consulting’s Worldwide Application Security Solution Market study is tailored for leaders who need both macro clarity and hands-on execution guidance. In a market expanding at a robust CAGR and transforming under regulatory and technological pressure, proactive strategy and disciplined execution will separate leaders from laggards in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Application Security Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Electrical Systems in Ships Market to Rise from USD 6,200 Million (Base Year 2025) to USD 9,666.7 Million by 2032 at a 6.55% CAGR (Forecast 2026–2032) — Asia Pacific Leads with USD 2,479.1M; Top 5 Firms Command 58.2%
By pmarketresearch, 2026-07-15
Worldwide Electrical Systems in Ships Market — Strategic Outlook for 2026: A PW Consulting Brief
PW Consulting is pleased to announce the release of our latest market research report, Worldwide Electrical Systems in Ships Market (base year 2025, forecast 2026–2032). This briefing summarizes the strategic implications for companies making critical investment, product, and partnership decisions in 2026. The global market for shipboard electrical systems has expanded materially over the past five years and is projected to continue growing at a steady pace—our model shows a compound annual growth rate (CAGR) of 6.55% across the 2026–2032 forecast window. In monetary terms (USD, revenue unit: Million), the market has evolved from a 2020 baseline of 4,530 to an estimated 6,200 in 2025 and is projected to reach approximately 9,667 by 2032.
Worldwide Electrical Systems in Ships Market
Why this report matters to 2026 decision-makers
-
Momentum behind ship electrification is no longer niche. Decarbonization mandates, tightening energy-efficiency regulations, and fleet electrification programs are transforming power architectures across commercial, offshore and defense fleets. These structural drivers create multi-year demand visibility for integrated electrical systems, energy storage and propulsion control.
Worldwide Electrical Systems in Ships Market -
Market growth is accompanied by shifting supplier economics. Rising power requirements onboard vessels increase demand for copper and marine-grade cabling, while battery technology and power electronics become central cost and technical differentiators. Procurement strategies and supply‑chain resilience will materially affect margin capture and time-to-revenue in 2026 and beyond.
Worldwide Electrical Systems in Ships Market -
Competitive actions—partnerships, targeted divestments and new-build contracts—have accelerated. Recent transactions and contract awards signal realignment among systems integrators, OEMs and specialist battery suppliers, with knock-on effects for go-to-market tactics and M&A agendas.
What the PW Consulting report delivers (practical, actionable content)
Our report balances executive-level strategic guidance with operationally relevant tools. Key deliverables include:
-
Market sizing and an audited forecasting model (2026–2032) with scenario toggles for alternative decarbonization and regulation outcomes.
-
System‑level total cost of ownership (TCO) templates—covering power generation, distribution, propulsion control and energy management—tailored to newbuild and retrofit economics.
-
Competitive benchmarking and go-to-market playbooks: vendor scorecards, capability maps and contracting archetypes.
-
Supply‑chain risk matrix including raw‑material exposure, lead‑time sensitivities and localization levers for critical components.
-
Investment cases and M&A heatmaps identifying where consolidation, partnerships or bolt‑on acquisitions are most value accretive.
-
Regulatory scenario planning and compliance roadmaps that translate maritime safety and energy management rules into product and service requirements.
Note: This briefing highlights the report’s strategic value; segment-level tables, regional breakdowns and contract-level revenue data are intentionally reserved for the full report to support proprietary decision-making.
Market dynamics shaping 2026 strategies
-
Fleet electrification is driving demand across multiple vessel classes. Public-sector fleet programs and private operator commitments are moving from pilots to fleet-scale procurement—creating opportunities for integrated suppliers and for niche specialists to scale through partnerships.
-
Strategic repositioning among incumbent suppliers. Recent corporate moves—including the divestment of an integrated marine electrical systems business by a major engine and systems provider—demonstrate a strategic sharpening across OEMs and the entrance of non‑traditional buyers into systems integration.
-
Partnerships between systems integrators, shipyards and battery specialists are consolidating go-to-market advantage. High‑visibility contract awards for hybrid-electric ferries and collaborative R&D projects for offshore support vessels illustrate how project-level alliances can leapfrog single-vendor capability gaps.
-
Input‑cost and compliance pressures are rising in parallel. Copper and specialized cabling remain core to electrical distribution and are increasingly a procurement consideration in long-term project costing. Concurrently, updated safety and energy regulations are accelerating upgrade cycles for existing fleets.
Competitive landscape: what to watch in 2026
The market is moderately concentrated (our concentration analysis shows meaningful share held by the top firms) but remains contestable across systems and services. Leading integrators and platform suppliers bring differentiating strengths:
-
Large systems integrators and equipment OEMs: Players with end‑to‑end portfolios—covering power generation, propulsion drives, distribution and automation—are best positioned to capture complex newbuild contracts and integrated retrofit packages. Their scale enables global service networks and turnkey delivery for fleet electrification programs.
-
Specialist energy storage and battery firms: Firms focused on maritime battery systems are essential partners for electrification, and their technology roadmaps determine key performance, safety and lifecycle economics in hybrid solutions.
-
Engine and propulsion specialists: Companies combining propulsion expertise with electrical systems can offer compelling hybrid architectures, especially where high integration between prime movers and electrical controls reduces system complexity.
-
System component suppliers and niche integrators: Smaller firms focused on switchboards, shore power solutions, converters and power management bring valuable modularity to projects and can be rapid acquisition targets for larger integrators seeking capability fill.
Strategic plays by stakeholder
-
For systems integrators and OEMs: Accelerate modular product lines, lock in long‑term supply agreements for key raw materials, and pursue alliances with battery suppliers. Use pilot project wins to build standardized delivery packages that reduce design‑to‑installation timelines.
-
For shipowners and operators: Prioritize lifecycle cost modelling over first‑cost procurement. Demand interoperability and standardized interfaces to protect future upgrade options and avoid vendor lock‑in. Consider long‑term service agreements to convert CapEx into predictable OpEx where feasible.
-
For shipyards: Invest in pre‑integrated structural elements and digital twin capabilities to shorten assembly and testing cycles. Show demonstrable compliance to emerging regulatory frameworks to win public and large‑operator contracts.
-
For component suppliers and battery makers: Secure qualification programs with lead integrators and focus on maritime‑specific safety certifications. Be prepared for volume scaling by 2027–2029 as large fleet programs move into execution.
-
For investors and M&A teams: Target bolt‑on technology plays that expand system integration capability or provide proprietary energy‑storage IP. Divest non‑core, capital‑intensive operations where scale benefits are limited.
2026 timing: near-term priorities that change outcomes
Given the market’s projected trajectory—with a notable step up in absolute market size in 2026 relative to earlier years—companies must treat 2026 as a year of execution rather than observation. Tactical priorities include:
-
Locking pilot contracts that can be rapidly scaled into program wins.
-
Establishing secured supply lines for critical raw materials and batteries to avoid pricing and lead-time shocks.
-
Positioning for public fleet electrification tenders and aligning product certifications to regional regulatory timelines.
-
Accelerating integration of energy management and digital monitoring to make retrofit offers more compelling from a risk and compliance perspective.
How PW Consulting supports your 2026 roadmap
Our research combines a disciplined quantitative model (comprehensive market-size vintage and a 2026–2032 forecast with sensitivity analysis) with deal‑level intelligence and supplier benchmarking. Clients benefit from:
-
Customized scenario runs from our forecast model to stress-test capital allocation under alternative regulatory and commodity-cost assumptions.
-
Vendor selection frameworks and RFP templates that embed TCO, safety and interoperability requirements.
-
M&A advisory and target-screening informed by capability maps and market concentration dynamics.
Next steps and access to the full intelligence
This brief is a strategic preview designed to surface the imperative for decisive action in 2026. The full PW Consulting report contains the granular segmental analytics, regional demand tables, vendor revenue benchmarks and downloadable models necessary to operationalize these insights. To obtain the comprehensive dataset, scenario models, and our practitioner playbooks, please visit our website or contact your PW Consulting advisor for access to the full report and a complimentary briefing session.
PW Consulting’s team of maritime electrification and systems-integration experts stands ready to translate this market intelligence into project roadmaps, procurement strategies and M&A execution plans—helping clients capture value across a market we forecast to expand substantially through the end of the decade.
For detailed analysis of this topic, please visit the official page: Worldwide Electrical Systems in Ships Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Acetylated Starch Market to Reach USD 894.16 Million by 2032 at a 4.81% CAGR — Asia‑Pacific Leads with USD 270.3M
By pmarketresearch, 2026-07-15
Worldwide Acetylated Starch Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Acetylated Starch Market synthesizes five years of historical metrics (2020–2025) and a seven‑year forecast (2026–2032) into an actionable strategic playbook for executives preparing decisions in 2026. The sector has shown resilient expansion and structural evolution: the market reached approximately USD 644.0 Million in 2025 and, with a projected compound annual growth rate (CAGR) of 4.81% across the 2026–2032 forecast window, is expected to approach roughly USD 894.2 Million by 2032. This briefing highlights the ways senior leaders can convert that macro trajectory into durable competitive advantage while directing you to the full report for proprietary segment-level detail.
Worldwide Acetylated Starch Market
Why 2026 is a Turning Point
Three forces converge as companies prepare 2026 budgets and strategic roadmaps: supply‑side volatility, evolving regulatory clarity for modified starches, and accelerating demand for application‑specific functionality in food, pharmaceuticals and industrial uses. Collectively, these dynamics compress the window for strategic moves—whether to invest in capacity, secure feedstock, or pursue premium, clean-label formulations.
Worldwide Acetylated Starch Market
- Supply volatility: Feedstock and intermediate chemistries are driving episodic cost pressure. For example, corn commodity cycles and tariffs have reshaped global trade flows, while regional spikes in potato starch pricing and swings in acetic acid spot prices have tightened margins in some production footprints. Such upstream movement directly impacts contract negotiation leeway and inventory policies for acetylated starch producers and formulators.
- Regulatory clarity: Recent re‑evaluations by food safety authorities have reduced uncertainty in select applications of acetylated derivatives, altering risk profiles for market entry and product labeling in key markets. Companies that incorporate regulatory scenario planning into R&D and go‑to‑market timetables will shorten time‑to‑revenue for novel formulations.
- Demand sophistication: End-users increasingly require functionality over commodity—freeze‑thaw stability, clean‑label emulsification, and tailored rheology for plant‑based and convenience foods—creating opportunities for differentiated starch esters as value‑added ingredients rather than bulk binders.
What the Report Delivers — Practical, Executable Content
Our report is designed as a decision‑toolset for executives, not just a repository of numbers. It includes:
Worldwide Acetylated Starch Market
- Comprehensive market sizing and trend analysis from 2020 through 2025, with bottom‑up validation and sensitivity-tested forecasts through 2032.
- Scenario pathways that translate alternate macro inputs (commodity cost shocks, tariff shifts, and regulatory outcomes) into revenue and margin implications for producers, ingredient buyers and downstream manufacturers.
- Value‑chain diagnostics—mapping feedstock risk, processing bottlenecks, and logistics constraints—to prioritize investments in backward or forward integration.
- Commercial playbooks for five archetypal players: global integrated producers, regional specialists, toll processors, niche application formulators, and private‑label food manufacturers.
- Competitive benchmarking and capability heatmaps that juxtapose product portfolios, specialty grades, technical service, and supply reliability—enabling rapid partner selection or M&A target short‑listing.
- A regulatory and standards atlas that aligns local approvals and functional limits with product development pathways, helping R&D and regulatory teams align priorities for 2026 launches.
- Investor and procurement dashboards designed for rapid C‑suite briefing: KPIs, trigger points and a roadmap for negotiating long‑term supply agreements or hedging strategies.
Competitive Landscape — Who Matters and Why
The acetylated starch market is moderately concentrated, with the three largest firms holding a meaningful share and the top five approaching a plurality—conditions that favor scale players but leave room for agile specialists. Our competitive analysis focuses on the capabilities and strategic postures of incumbent and specialist producers:
- Cargill Inc. (Minneapolis, USA): A global leader with deep integration across starch derivatives and technical resource capability. Cargill’s strength lies in large‑scale manufacturing, global supply chains and broad application knowledge—advantages for customers seeking secure, multi‑region supply and customized grades for complex formulations.
- Ingredion Incorporated (Westchester, USA): Known for clean‑label positioning and branded ingredient systems, Ingredion competes on technical formulation support and application development, particularly for convenience foods and bakery systems.
- Tate & Lyle PLC (London, UK): Brings strong R&D around functional performance (freeze‑thaw, texture) and is positioned to capture demand in frozen and ready‑to‑eat food categories that require stability.
- Roquette Frères (Lestrem, France): A player with strengths in pharmaceutical grades and excipient applications, offering regulatory support and pharma‑grade manufacturing practices—important where tablet binding and controlled disintegration are required.
- Avebe U.A. (Veendam, Netherlands): A potato‑specialist with product lines focused on dairy and meat analog applications, well placed to serve plant‑based and specialty protein markets.
- Emsland Group (Emlichheim, Germany): Provides potato‑based acetylates with emphasis on pet food and industrial adhesives, illustrating how source specialization can unlock niche value pools.
- AGRANA Beteiligungs‑AG (Vienna, Austria): Combines corn and wheat capabilities targeted at paper and technical industries, highlighting horizontal diversification across end markets.
- KMC Kartoffelmelfabrik A/S (Hammel, Denmark): Focuses on high‑performance potato starches for extrusion and batter applications, demonstrating the premium opportunities in processing‑intensive segments.
For 2026 planning, strategic options range from doubling down on branded specialty grades and application‑centric services, to pursuing bolt‑on acquisitions that add regional capacity or specific source capabilities (e.g., potato vs. corn). The full report contains a detailed M&A scorecard and integration playbook tailored to each archetype above.
Key Strategic Imperatives for 2026
Based on the market trajectory and sector dynamics, PW Consulting recommends that executives prioritize five initiatives in 2026:
- Hedge feedstock risk and diversify sourcing: Implement multi‑tier procurement strategies that combine long‑term offtakes, strategic inventory, and geographic sourcing to cushion corn or potato price swings and tariff exposures.
- Invest selectively in functional differentiation: Prioritize R&D for formulations that command technical premiums—freeze‑thaw resilience, emulsification for low‑fat systems, and excipient grades for pharma—where margin expansion is achievable.
- Embed regulatory scenario planning into product roadmaps: Use modular regulatory dossiers and phased launches to exploit favorable re‑evaluations while reducing compliance risk across markets.
- Pursue targeted partnerships and co‑development: Collaborate with downstream OEMs (frozen foods, plant‑based proteins, tablet formulators) to co‑innovate and pre‑qualify grades, accelerating adoption cycles.
- Optimize production footprint through capacity and process improvements: Evaluate retrofits and tolling arrangements to balance capital intensity with responsiveness to demand volatility.
Scenario Sensitivities and Operational Triggers
The report provides scenario-based P&L models that show how a set of plausible macro movements—commodity price spikes, regulatory tightening or easing, and sudden shifts in end‑market demand—translate into cash flow and working capital stress points. For practical decision‑making, we identify three operational triggers that should prompt immediate executive action in 2026:
- Raw material cost variance exceeds tolerance bands—activate hedges and renegotiate long‑term supply contracts.
- Key regulatory approval delayed or tightened—prioritize markets with clearer pathways and shift commercialization timelines.
- Order book concentrated in a narrow set of customers—diversify through co‑development agreements and new channel partnerships.
Where This Report Adds Unique Value
Unlike desk studies that stop at forecasting, PW Consulting’s acetylated starch research ties market projections to operational levers and boardroom decisions. The report’s proprietary elements include:
- Validated supplier performance scores drawn from primary interviews and plant‑level audits.
- Application‑level willingness‑to‑pay curves that quantify premium pockets for differentiated functionality.
- Turnkey investment templates for capacity expansion, with sensitivity to feedstock and logistics risk.
Next Steps — How to Use This Analysis in 2026 Planning
For executive teams preparing capital allocation and product strategy in 2026, start by using the report’s dashboard to stress‑test your base case across the three scenarios provided. Then prioritize 2–3 immediate actions—procurement restructuring, targeted R&D investments, or selective partnerships—and map timelines to the operational triggers identified above. Finally, use the competitive heatmaps to refine negotiation positions with suppliers, customers and potential acquisition targets.
PW Consulting’s full Worldwide Acetylated Starch Market report contains the complete segment‑level intelligence, supplier scorecards, regulatory dossiers and detailed scenario P&L models that underpin the strategic recommendations summarized here. To access the proprietary segment breakdowns, application‑specific forecasts, and the transaction playbook for 2026, please visit our report landing page.
For detailed analysis of this topic, please visit the official page: Worldwide Acetylated Starch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Reusable Food Wrap Market Forecast to Expand at 7.15% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Reusable Food Wrap Market: Strategic Briefing for 2026 Decisions
PW Consulting’s latest market study on the Worldwide Reusable Food Wrap Market delivers a focused intelligence product for executives preparing to make decisive investments in 2026. Our analysis finds the market reached approximately USD 245.0 Million in 2025 and—absent disruptive downside shocks—is forecast to expand at a compound annual growth rate (CAGR) of about 7.15% across the 2026–2032 horizon, reaching nearly USD 397.3 Million by 2032. These headline figures frame a growth narrative driven by regulatory pressure, rising consumer sustainability demand, and evolving product innovation, and they establish the quantitative baseline that underpins the suite of practical tools contained in the full report.
Worldwide Reusable Food Wrap Market
Why this matters for 2026 strategic planning
- Regulatory inflection points make 2026 a planning hinge year. Several US states and other jurisdictions are accelerating mandates and restrictions on single-use plastics that materially raise the value proposition of reusable alternatives.
- Growing addressable demand at a steady mid-single-digit-to-low-double-digit pace creates windows for both incumbents and new entrants to lock in distribution and manufacturing advantages before the space consolidates.
- Raw material dynamics (notably beeswax pricing) and concentrated manufacturing capacity mean procurement strategy and supplier diversification will directly influence margin outcomes in the next 12–24 months.
Market dynamics shaping 2026
Policy initiatives are the single most important near-term demand multiplier. Example regulatory milestones—such as statewide measures requiring recyclable or compostable packaging and bans on specific single-use items—are catalyzing procurement changes across retail, foodservice and institutional buyers. These measures are already driving RFPs, pilot programs, and supplier evaluations that will culminate in 2026 rollouts and volume commitments.
Worldwide Reusable Food Wrap Market
On the input side, beeswax—an important raw material for a sizeable segment of reusable wraps—has shown price volatility that matters to manufacturing margins. Our desk review highlights visible trade prices in the US trading near USD 18.29 per kg in late 2025 and a reported global export average in 2024 in the low thousands of USD per metric ton—figures that emphasize the need for active procurement hedging and alternative-material development for price insulation.
Worldwide Reusable Food Wrap Market
Supply-side posture is also evolving. Mature, branded incumbents emphasize certification and traceability (organic cotton GOTS certifications, LFGB/REACH/FDA compliance pathways), while larger manufacturers—particularly in Asia—are scaling OEM/ODM capacity to absorb rising global demand. Distribution channels are bifurcating: brand-led direct-to-consumer experiences coexist with private-label scale plays targeting retail and foodservice contracts.
Competitive landscape: players to watch (and why)
The market remains fragmented. The top three and top five players account for a moderate share of revenue, leaving ample opportunity for regional champions, vertical specialists and private-label suppliers to expand. Our CR3 and CR5 measures indicate a market that is neither atomized nor tightly concentrated—an environment that favors strategic partnerships, targeted M&A and scale-driven manufacturing plays.
- Bee’s Wrap, LLC (Vermont, USA) — a pioneer and reference brand. Their emphasis on certified organic inputs, visible brand heritage and consumer trust creates a defensible premium position in developed markets. For buyers and partners, Bee’s Wrap exemplifies the premium, mission-led brand model.
- Abeego Designs Inc. (Canada) — notable for product differentiation and freshness-extension claims. Abeego’s technical positioning around breathable food preservation makes it a desirable collaborator for specialty food brands and sustainability-driven retailers.
- Etee and LilyBee Wrap — brand-focused regional players with strong zero-waste narratives. These companies are valuable case studies in community-driven growth, subscription and gifting models.
- Henan Green Wrap Products Co., Ltd and Green Wrap (China) — examples of scale-focused manufacturers offering OEM/ODM services and multi-jurisdictional compliance. They are natural partners for retailers and private-label programs seeking cost-competitive supply with certification pathways.
- Keep Leaf, U-KONSERVE, SuperBee, Khala & Company — represent differentiated distribution strategies, from sustainable kitchen lifestyle plays to institutional supply relationships.
The implication for 2026 strategy: buyers seeking margin resilience should evaluate a two-track supplier strategy—partner with brand leaders for premium channels and with scalable manufacturers for private-label/foodservice volumes—while monitoring certification and traceability requirements that will become procurement table stakes.
What the PW Consulting report delivers (practical, actionable content)
Designed as a decision support toolkit for business leaders, procurement heads and M&A teams, the full study provides hands-on modules that translate market signals into executable initiatives:
- Market-sizing methodology and assumptions—transparent, replicable models that allow you to stress-test topline forecasts under alternative regulatory and price scenarios.
- Segment and regional demand diagnostics—directional demand drivers by channel (consumer retail, foodservice, institutional), plus buyer behavior insights that inform SKU rationalization and assortment planning (note: detailed segment-level figures and splits are reserved for the full report).
- Supplier map and qualification checklist—differentiating manufacturing tiers, certification readiness (GOTS, LFGB, REACH, FDA), production lead times and OEM/ODM capabilities.
- Cost and margin modeling tools—sensitivity tables that quantify the impact of beeswax and other input price moves, labor and freight assumptions on finished-goods economics.
- Go-to-market playbooks—channel entry frameworks, promotional levers, pricing ladders and private-label negotiation templates to win 2026 tenders and retail placements.
- M&A and partnership scorecards—criteria for target screening, synergy mapping and integration risk checklists tuned to this sector’s dynamics.
- Regulatory compliance roadmap—practical steps to align product specs and packaging claims with evolving jurisdictional mandates, including timelines and compliance costs.
- Scenario planning & risk register—four modeled futures (base, regulatory-accelerated, input-cost shock, and rapid-consolidation), with recommended contingency actions for each.
Actionable recommendations for executives in 2026
- Align procurement with scenario planning: create a hedged supply strategy that combines near-shore certified suppliers for fast-moving premium SKUs and cost-competitive offshore partners for commoditized lines. Implement contractual hedges or indexation clauses tied to beeswax or commodity proxies where feasible.
- Prioritize compliance and claims verification: dedicate a 2026 product roadmap milestone to secure required certifications and audit-ready traceability. Regulatory-driven procurement will increasingly screen out non-compliant suppliers.
- Layer channel strategies: deploy differentiated SKUs across branded DTC, retail and private-label channels to protect margins while accelerating distribution. Use subscription and refill models to deepen customer lifetime value in premium segments.
- Prepare the M&A bench: given moderate market concentration, identify tuck-in targets that add geographic breadth, manufacturing capacity or certification credentials. Use our scorecard to quantify deal economics and integration complexity in advance.
- Invest in material innovation: hedge beeswax dependency by accelerating R&D into alternative coatings and silicone solutions that meet performance and sustainability expectations—this reduces single-point supply risk and creates product differentiation.
Risks to monitor
Key downside risks include abrupt beeswax supply or price shocks, regulatory rollbacks or uneven enforcement across jurisdictions, and a rapid wave of low-cost private-label competition that compresses margins. Conversely, accelerated mandates and procurement commitments from large foodservice chains would materially uplift volumes and compress payback periods for supply-side investments. Our scenario models make these trade-offs explicit and quantify the break-even points for different strategic choices.
How to use this briefing
This briefing is a concentrated executive summary of the strategic signals that our full report unpacks with operational detail. If you are preparing budgets, negotiating supplier contracts, planning product launches or evaluating acquisition targets for 2026, the full PW Consulting report provides the templates, models and supplier intelligence to move from hypothesis to execution within weeks—not months.
To access the complete dataset, segment-level analytics, and the full suite of decision tools (including downloadable cost models and supplier scorecards), please consult the PW Consulting report landing page. The public summary herein is intended to establish the strategic contours and compel targeted follow-up for teams that require the underlying tables and playbooks needed for immediate action.
Concluding perspective
The reusable food wrap sector is entering a maturation phase where policy, procurement and product innovation intersect. For 2026, the winners will be organizations that convert regulatory momentum and consumer intent into operational advantage—by locking supply, certifying at scale, and designing go-to-market plays that balance premium branding with efficient fulfillment. PW Consulting’s report arms decision-makers with the macro baselines, competitive diagnostics and tactical templates necessary to do exactly that.
For detailed analysis of this topic, please visit the official page: Worldwide Reusable Food Wrap Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com