

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Organic Maple Syrup Market to Expand at a 7.02% CAGR — Sweet Growth Ahead

Worldwide Organic Maple Syrup Market — Strategic Outlook for 2026
Executive summary
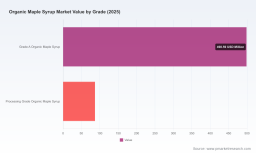
PW Consulting’s latest Worldwide Organic Maple Syrup Market report (base year 2025, historical series 2020–2025, forecast 2026–2032) equips senior executives and commercial teams with the forward-looking intelligence required to make high-impact decisions in 2026. The market reached approximately USD 585.5 Million in 2025 and – on the trajectory captured in our model – is projected to grow at a compound annual growth rate (CAGR) of 7.02% across the 2026–2032 forecast window, arriving near USD 941 Million by 2032 under our central-case assumptions.
Worldwide Organic Maple Syrup Market
These headline numbers mask a more nuanced competitive and operational landscape: supply-side expansion plans, evolving certification and stewardship requirements, buyer behavior shifts on organic premiums, and persistent labor and infrastructure constraints are all combining to make 2026 a pivotal year for strategic repositioning. Our report synthesizes these dynamics into an actionable playbook for market entry, procurement, product strategy, and M&A prioritization.
Worldwide Organic Maple Syrup Market
Why 2026 matters — the strategic inflection points
-
Supply reconfiguration: Larger producers in the U.S. have signaled meaningful capacity growth, with some operators planning double-digit expansions of tap count and processing capability. Notably, industry reporting indicates a significant portion of planned new production is intended to be certified organic — a structural shift that will influence supply elasticity and the availability of certified inventory in the near term.
Worldwide Organic Maple Syrup Market -
Premium compression risk: Major buyers and processors are already signaling a reassessment of organic pay premiums for 2026. As certified volumes grow, organizations that previously relied on consistent organic premiums will face margin pressures unless they refresh sourcing strategies or add differentiated consumer-facing propositions.
-
Regulatory and certification complexity: Organic maple syrup certification is not a simple label — in the U.S., it is tightly linked to forest stewardship plans, limits on synthetic inputs, and prescribed operational practices (e.g., permitted defoaming agents). Parallel governance structures in Canada — including production quotas and strategic reserves managed by producer federations — add an additional layer of supply-side modulation that will shape export flows and availability.
-
Capital and operational efficiency: The mix of labor shortages and increased investment in processing technologies (reverse osmosis, automated tapping systems, modern evaporators) is changing unit economics. Producers who accelerate technology upgrades under organic-compliant specifications will gain cost and scale advantages.
What the report delivers — practical, decision-ready content
-
Integrated market model: top-down and bottom-up views, historical validation (2020–2025), and scenario-driven forecasts for 2026–2032 including sensitivity to tap-count growth, certification conversion rates, and premium erosion.
-
Supply-demand scenarios: three actionable cases (conservative, central, upside) that model how certification adoption, quota management, and strategic reserve releases affect pricing and availability.
-
Price-formation and contract playbooks: guidance on term structures, indexation clauses, and performance KPIs for procurement teams to manage premium volatility and inventory risk.
-
Operational checklist for organic compliance: practical steps for forest stewardship planning, permitted inputs, audit readiness, and traceability systems aligned with MOFGA/VOF/MOSA and comparable certification bodies.
-
Route-to-market and SKU strategies: roadmaps for premium single-origin positioning versus co-packing/industrial blends, including recommended packaging, shelf-space tactics, and foodservice channel entry plays.
-
M&A and partnership frameworks: screens and valuation heuristics for bolt-on acquisitions, co-op partnerships, and long-term offtake arrangements with larger processors and distributor networks.
-
Risk matrix and early-warning indicators: a monitoring dashboard of 12 leading indicators (tap counts, certification applications, distributor inventory days, buyer premium signals, PPAQ reserve movements) to anticipate price inflection and supply imbalances.
-
Competitive benchmarking: strategic profiles, capability maps and scenario readiness assessments for the sector’s leading producers and processors.
Competitive landscape — strategic takeaways on the core players
-
Coombs Family Farms (Brattleboro, VT) — Multi-generational brand equity and broad retail reach are core strengths. Expect Coombs to continue leveraging brand-led premium positioning while selectively pursuing scale opportunities through contract packing and private label agreements.
-
Butternut Mountain Farm (Morrisville, VT) — Significant processing capacity and global distribution give this player an advantage in converting increased tap-count supply into commercially available certified inventory. Scale offers negotiating leverage with large buyers, but exposure to premium compression is material.
-
Crown Maple (Dover Plains, NY) — Premium single-origin positioning and tourism/brand experience create resiliency for retail price premiums. Their model is less sensitive to volume-driven price swings but depends on a sustained consumer willingness to pay.
-
Bascom Maple Farms — As a major independent buyer-processor, Bascom’s role as a consolidator of raw certified supply makes it a bellwether for bulk market dynamics and industrial channel flows.
-
Quebec Producers (e.g., Escuminac, LB Maple Treat, NuCAN) — Quebec-based processors and cooperatives remain structurally important to global supply. The federation-level quota and reserve mechanisms in Canada can quickly alter exportable certified volumes; monitoring these policies is essential for procurement planning.
-
Cooperatives and smaller specialist producers (Maple Valley Cooperative, Baird Farm, Sap Hound) — These organizations offer high traceability and local stewardship stories attractive to premium channels. They are also potential partners for co-development and secure long-term offtake.
Recent developments to watch (implications for 2026 tactics)
-
Industry reporting in early 2026 indicates sizable expansion plans among larger U.S. producers, with a significant share of that new capacity intended to carry organic certification. This will shift supply composition and may accelerate premium normalization in 2026.
-
New product certifications and trade show activity by specialist brands in 2025–2026 show continued retail innovation and category momentum. Brands converting conventional SKUs to certified organic should be treated as both competitors and potential collaborators for capacity aggregation.
-
Production statistics confirming robust output from states such as Maine underline that North American organic supply remains foundational; buyers should stress-test contracts against regional harvest cycles and cross-border logistic friction.
Recommended strategic moves for executives in 2026
-
Adopt a dual-track procurement strategy: secure near-term volumes with flexible indexed contracts while investing in strategic long-term offtake agreements with certified producers to lock in quality and traceability.
-
Negotiate premium de-risking clauses: include volume-tiered premiums, quality-adjusted rebates, and inventory carry provisions to limit exposure to rapid premium compression.
-
Invest selectively in traceability and stewardship verification to protect brand claims and command differentiated pricing for single-origin or high-stewardship SKUs.
-
Prioritize capital allocation to processing upgrades (reverse osmosis, energy-efficient evaporators) where organic-compliant practices can materially reduce per-unit cost.
-
Scan for strategic M&A or partnership targets among regional co-ops and independent processors to consolidate supply and secure access to certified volume without sole dependence on commodity spot markets.
-
Deploy a demand strategy that mixes premium retail storytelling with industrial channel penetration where higher volumes can offset narrower margins.
Market structure note and how we treat granular data
Our concentration analysis shows a moderately consolidated market: the top three players represent a material share of commercial activity, while the top five further increase sector concentration. We intentionally present our public commentary at a strategic level — the full report contains the granular regional, grade, and channel splits, buyer-level pricing matrices, and downloadable scenario models that underpin the analyses summarized here. These core segment figures are omitted from this release to preserve the report’s commercial value and to encourage direct access to the full dataset for decision-makers.
Call to action
For procurement leads, corporate strategy teams, private equity investors, and supplier management functions preparing plans for 2026, this report provides the quantitative models, operational checklists, and competitive intelligence necessary to convert market signals into decisive action. Access the full Worldwide Organic Maple Syrup Market report to obtain the detailed segment-level data, supplier scorecards, and downloadable scenario models required to finalize budgets and contract negotiations for 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Organic Maple Syrup Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com