

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
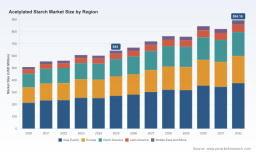
PW Consulting Forecast: Worldwide Acetylated Starch Market to Reach USD 894.16 Million by 2032 at a 4.81% CAGR — Asia‑Pacific Leads with USD 270.3M

Worldwide Acetylated Starch Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Acetylated Starch Market synthesizes five years of historical metrics (2020–2025) and a seven‑year forecast (2026–2032) into an actionable strategic playbook for executives preparing decisions in 2026. The sector has shown resilient expansion and structural evolution: the market reached approximately USD 644.0 Million in 2025 and, with a projected compound annual growth rate (CAGR) of 4.81% across the 2026–2032 forecast window, is expected to approach roughly USD 894.2 Million by 2032. This briefing highlights the ways senior leaders can convert that macro trajectory into durable competitive advantage while directing you to the full report for proprietary segment-level detail.
Worldwide Acetylated Starch Market
Why 2026 is a Turning Point
Three forces converge as companies prepare 2026 budgets and strategic roadmaps: supply‑side volatility, evolving regulatory clarity for modified starches, and accelerating demand for application‑specific functionality in food, pharmaceuticals and industrial uses. Collectively, these dynamics compress the window for strategic moves—whether to invest in capacity, secure feedstock, or pursue premium, clean-label formulations.
Worldwide Acetylated Starch Market
- Supply volatility: Feedstock and intermediate chemistries are driving episodic cost pressure. For example, corn commodity cycles and tariffs have reshaped global trade flows, while regional spikes in potato starch pricing and swings in acetic acid spot prices have tightened margins in some production footprints. Such upstream movement directly impacts contract negotiation leeway and inventory policies for acetylated starch producers and formulators.
- Regulatory clarity: Recent re‑evaluations by food safety authorities have reduced uncertainty in select applications of acetylated derivatives, altering risk profiles for market entry and product labeling in key markets. Companies that incorporate regulatory scenario planning into R&D and go‑to‑market timetables will shorten time‑to‑revenue for novel formulations.
- Demand sophistication: End-users increasingly require functionality over commodity—freeze‑thaw stability, clean‑label emulsification, and tailored rheology for plant‑based and convenience foods—creating opportunities for differentiated starch esters as value‑added ingredients rather than bulk binders.
What the Report Delivers — Practical, Executable Content
Our report is designed as a decision‑toolset for executives, not just a repository of numbers. It includes:
Worldwide Acetylated Starch Market
- Comprehensive market sizing and trend analysis from 2020 through 2025, with bottom‑up validation and sensitivity-tested forecasts through 2032.
- Scenario pathways that translate alternate macro inputs (commodity cost shocks, tariff shifts, and regulatory outcomes) into revenue and margin implications for producers, ingredient buyers and downstream manufacturers.
- Value‑chain diagnostics—mapping feedstock risk, processing bottlenecks, and logistics constraints—to prioritize investments in backward or forward integration.
- Commercial playbooks for five archetypal players: global integrated producers, regional specialists, toll processors, niche application formulators, and private‑label food manufacturers.
- Competitive benchmarking and capability heatmaps that juxtapose product portfolios, specialty grades, technical service, and supply reliability—enabling rapid partner selection or M&A target short‑listing.
- A regulatory and standards atlas that aligns local approvals and functional limits with product development pathways, helping R&D and regulatory teams align priorities for 2026 launches.
- Investor and procurement dashboards designed for rapid C‑suite briefing: KPIs, trigger points and a roadmap for negotiating long‑term supply agreements or hedging strategies.
Competitive Landscape — Who Matters and Why
The acetylated starch market is moderately concentrated, with the three largest firms holding a meaningful share and the top five approaching a plurality—conditions that favor scale players but leave room for agile specialists. Our competitive analysis focuses on the capabilities and strategic postures of incumbent and specialist producers:
- Cargill Inc. (Minneapolis, USA): A global leader with deep integration across starch derivatives and technical resource capability. Cargill’s strength lies in large‑scale manufacturing, global supply chains and broad application knowledge—advantages for customers seeking secure, multi‑region supply and customized grades for complex formulations.
- Ingredion Incorporated (Westchester, USA): Known for clean‑label positioning and branded ingredient systems, Ingredion competes on technical formulation support and application development, particularly for convenience foods and bakery systems.
- Tate & Lyle PLC (London, UK): Brings strong R&D around functional performance (freeze‑thaw, texture) and is positioned to capture demand in frozen and ready‑to‑eat food categories that require stability.
- Roquette Frères (Lestrem, France): A player with strengths in pharmaceutical grades and excipient applications, offering regulatory support and pharma‑grade manufacturing practices—important where tablet binding and controlled disintegration are required.
- Avebe U.A. (Veendam, Netherlands): A potato‑specialist with product lines focused on dairy and meat analog applications, well placed to serve plant‑based and specialty protein markets.
- Emsland Group (Emlichheim, Germany): Provides potato‑based acetylates with emphasis on pet food and industrial adhesives, illustrating how source specialization can unlock niche value pools.
- AGRANA Beteiligungs‑AG (Vienna, Austria): Combines corn and wheat capabilities targeted at paper and technical industries, highlighting horizontal diversification across end markets.
- KMC Kartoffelmelfabrik A/S (Hammel, Denmark): Focuses on high‑performance potato starches for extrusion and batter applications, demonstrating the premium opportunities in processing‑intensive segments.
For 2026 planning, strategic options range from doubling down on branded specialty grades and application‑centric services, to pursuing bolt‑on acquisitions that add regional capacity or specific source capabilities (e.g., potato vs. corn). The full report contains a detailed M&A scorecard and integration playbook tailored to each archetype above.
Key Strategic Imperatives for 2026
Based on the market trajectory and sector dynamics, PW Consulting recommends that executives prioritize five initiatives in 2026:
- Hedge feedstock risk and diversify sourcing: Implement multi‑tier procurement strategies that combine long‑term offtakes, strategic inventory, and geographic sourcing to cushion corn or potato price swings and tariff exposures.
- Invest selectively in functional differentiation: Prioritize R&D for formulations that command technical premiums—freeze‑thaw resilience, emulsification for low‑fat systems, and excipient grades for pharma—where margin expansion is achievable.
- Embed regulatory scenario planning into product roadmaps: Use modular regulatory dossiers and phased launches to exploit favorable re‑evaluations while reducing compliance risk across markets.
- Pursue targeted partnerships and co‑development: Collaborate with downstream OEMs (frozen foods, plant‑based proteins, tablet formulators) to co‑innovate and pre‑qualify grades, accelerating adoption cycles.
- Optimize production footprint through capacity and process improvements: Evaluate retrofits and tolling arrangements to balance capital intensity with responsiveness to demand volatility.
Scenario Sensitivities and Operational Triggers
The report provides scenario-based P&L models that show how a set of plausible macro movements—commodity price spikes, regulatory tightening or easing, and sudden shifts in end‑market demand—translate into cash flow and working capital stress points. For practical decision‑making, we identify three operational triggers that should prompt immediate executive action in 2026:
- Raw material cost variance exceeds tolerance bands—activate hedges and renegotiate long‑term supply contracts.
- Key regulatory approval delayed or tightened—prioritize markets with clearer pathways and shift commercialization timelines.
- Order book concentrated in a narrow set of customers—diversify through co‑development agreements and new channel partnerships.
Where This Report Adds Unique Value
Unlike desk studies that stop at forecasting, PW Consulting’s acetylated starch research ties market projections to operational levers and boardroom decisions. The report’s proprietary elements include:
- Validated supplier performance scores drawn from primary interviews and plant‑level audits.
- Application‑level willingness‑to‑pay curves that quantify premium pockets for differentiated functionality.
- Turnkey investment templates for capacity expansion, with sensitivity to feedstock and logistics risk.
Next Steps — How to Use This Analysis in 2026 Planning
For executive teams preparing capital allocation and product strategy in 2026, start by using the report’s dashboard to stress‑test your base case across the three scenarios provided. Then prioritize 2–3 immediate actions—procurement restructuring, targeted R&D investments, or selective partnerships—and map timelines to the operational triggers identified above. Finally, use the competitive heatmaps to refine negotiation positions with suppliers, customers and potential acquisition targets.
PW Consulting’s full Worldwide Acetylated Starch Market report contains the complete segment‑level intelligence, supplier scorecards, regulatory dossiers and detailed scenario P&L models that underpin the strategic recommendations summarized here. To access the proprietary segment breakdowns, application‑specific forecasts, and the transaction playbook for 2026, please visit our report landing page.
For detailed analysis of this topic, please visit the official page: Worldwide Acetylated Starch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com