

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Conjunctivitis Ophthalmic Drugs Market to Grow from USD 5,466.5 Million in 2025 to USD 7,952.01 Million by 2032 at a 5.51% CAGR

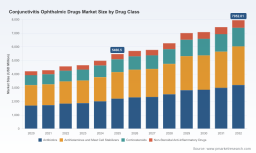
Worldwide Conjunctivitis Ophthalmic Drugs Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Conjunctivitis Ophthalmic Drugs Market synthesizes five years of historic performance and a seven‑year forecast horizon to equip executive teams with the strategic intelligence they need for 2026. The conjunctivitis therapeutics market has expanded steadily from approximately USD 4.21 billion in 2020 to an estimated USD 5.47 billion in 2025, and our base‑case forecast (2026–2032) projects a compound annual growth rate (CAGR) of 5.51%, reaching roughly USD 7.95 billion by 2032. These headline metrics frame a resilient growth narrative — but the competitive and regulatory dynamics underneath that topline are what will determine winners and losers in the coming 18–36 months.
Worldwide Conjunctivitis Ophthalmic Drugs Market
Why this matters for 2026 planning
-
Budgeting & resource allocation: With mid‑single‑digit CAGR and clear upside to 2032, biopharma and ophthalmic device teams should prioritize initiatives that capture sustainable share versus short‑term volume plays that are vulnerable to price erosion.
Worldwide Conjunctivitis Ophthalmic Drugs Market -
M&A and licensing windows: Moderate market concentration (CR3 ≈ 42.5%; CR5 ≈ 58.8%) signals that top firms hold meaningful scale but that gaps remain for targeted acquisitions, geographic rollouts, or specialty product in‑licensing to materially move the needle.
Worldwide Conjunctivitis Ophthalmic Drugs Market -
Reimbursement & access strategy: Product form (drops vs. inserts vs. sustained‑release), pediatric labeling, and payer position will be as determinative of commercial success as clinical differentiation.
Market trajectory — reading the topline
The market’s recovery and growth since 2020 reflect both demand elasticity in allergy and infectious disease care pathways and an expanding set of therapeutic modalities (traditional drops, preservative‑free formulations, inserts, and sustained‑release systems). Growth drivers include rising allergy prevalence in urbanized populations, continued uptake of branded innovations where clinically differentiated, and steady replacement of older therapies with preservative‑free or higher‑convenience options. Against that backdrop, generics and biosimilar entrants create persistent pricing pressure in commoditized segments.
For 2026, expect continuing mid‑single‑digit compound growth — supportive of disciplined commercial investments but not of undirected broad launches. Detailed scenario modelling in our report shows that incremental market share gains from either a differentiated branded asset or a cost‑effective generic play can have asymmetric value depending on channel access and payer coverage outcomes.
Competitive dynamics — what incumbents and challengers are doing
The competitive set blends large integrated players, specialist ophthalmic firms, and agile generics manufacturers. Industry leaders continue to push on three vectors: product differentiation, delivery technology, and geographic breadth. Notable players covered in our analysis include Alcon, Bausch + Lomb (Bausch Health), AbbVie (Allergan), Novartis, Santen, Pfizer, Nicox, Sun Pharma, Alembic, and Ocular Therapeutix. Each pursues a distinct strategic posture — from Alcon’s strong allergy portfolio to Santen’s specialization in pediatric and severe allergic indications, and from Sun Pharma’s generics scale to Ocular Therapeutix’s device‑enabled delivery approach.
Recent industry developments are illustrative of momentum and disruption: generic launches of established anti‑infective agents and anti‑allergy molecules continue to compress pricing in commoditized categories; selected regulatory approvals and label expansions for novel delivery formats have opened niche clinical and commercial opportunities; and regulatory approvals in major emerging markets have created new addressable segments for specialist products. Our report integrates these events into competitive scenarios, assessing their likely impact on revenue curves, margin trajectories, and bargaining power with payers and distributors.
Regulatory, patent and reimbursement levers — implications for strategy
-
Regulatory labeling nuances (including pediatric use constraints) materially affect product positioning. For example, intracanalicular inserts offer differentiated adherence and convenience benefits, but pediatric insertion requirements and payer treatment policies limit near‑term adoption unless procedural workflows and reimbursement codes are addressed.
-
Patent expiries and generic availability are compressing value in selected molecule classes; companies with heavy exposure to those molecules must accelerate lifecycle plans (reformulation, device pairing, or new indications) to preserve pricing.
-
API supply diversity for key molecules is both a risk mitigation factor and a competitive enabler. Securing multi‑sourced APIs and manufacturing capacity should be part of 2026 operational planning to avoid shortages or cost shocks.
Key strategic moves for 2026
-
Segmented go‑to‑market: Prioritize channels and therapeutic niches where your product’s attributes (efficacy, safety, dosing convenience, pediatric label) map to payer and clinician willingness‑to‑pay. Avoid one‑size‑fits‑all launches in an environment of selective coverage.
-
Defend and extend: For brands facing imminent generic competition, accelerate lifecycle actions — Rx‑to‑OTC switches where applicable, preservative‑free reformulations, fixed‑dose combinations, or device‑enabled delivery — that create new value not easily replicated by pure generics.
-
Partnerships & bolt‑ons: Use M&A selectively to fill capability gaps (e.g., sustained‑release technologies, pediatric formulations, regional registration expertise). Given the market’s moderate top‑end concentration, well‑timed bolt‑ons can lift commercial scale meaningfully.
-
Access engineering: Invest in reimbursement dossiers and procedure code strategy for insertable and sustained‑release products. Early payer engagement and real‑world evidence generation can accelerate uptake and justify premium pricing.
-
Supply resiliency: Build redundancy across API suppliers and leverage contract manufacturing partners to manage cost volatility and fulfilment timelines, especially for sterile ophthalmic products where regulatory audits and quality issues can create supply interruptions.
What PW Consulting’s report delivers — practical outputs for teams
Our report is designed not as a pure market narrative but as an executable intelligence package for 2026 planning cycles. Deliverables include:
-
A validated topline forecast with sensitivity scenarios (base, conservative, upside) through 2032, with transparent modelling assumptions.
-
Competitive profiling and strategic heatmaps for leading and emerging players, assessing R&D pipelines, commercial footprints, and likely strategic moves.
-
Regulatory & reimbursement impact matrices, including pediatric labeling constraints, insertable device reimbursement pathways, and patent‑expiry timelines that drive risk‑adjusted cash‑flow projections.
-
Go‑to‑market playbooks tailored by product archetype (branded differentiated, generic cost leader, device‑enabled therapy), complete with launch sequencing, payer engagement templates, and HCP targeting frameworks.
-
M&A screening criteria and valuation sensitivity tables for targets across the value chain (specialty ophthalmics, delivery technology, CMOs).
-
Operational checklists covering API sourcing, sterile fill/finish readiness, and quality compliance priorities to de‑risk supply interruptions.
How different stakeholders should use the intelligence in 2026
-
Executive teams: Use the report to set portfolio prioritization and budget envelopes, aligning R&D funnel gating with commercial realities implied by the market growth path.
-
Commercial leaders: Adopt the playbooks to refine channel strategies and to shape payer value messaging, especially for products with procedural requirements or pediatric considerations.
-
Business development & M&A teams: Apply our screening filters and valuation sensitivity work to identify bolt‑on targets that de‑risk launches or accelerate entry into underserved therapeutic niches.
-
R&D and medical affairs: Leverage the regulatory and evidence roadmaps to prioritize studies that unlock label expansions and payer coverage (e.g., real‑world adherence, pediatric safety).
Limitations & where to go next
Our briefing intentionally focuses on strategic implications and high‑level market trajectory. For clients requiring granular subsegment breakdowns (by drug class, disease type, and geographic revenue splits), line‑by‑line forecasts, or custom scenario modelling tied to proprietary assets, the full PW Consulting dataset and modelling workbook provide the necessary granularity — including segment P&Ls, price‑volume elasticity assumptions, and payer‑by‑country reimbursement scenarios. This “paywall” approach is deliberate: we provide the strategic narrative here to inform 2026 decision frameworks while directing teams that need executable numbers to the full deliverable.
Conclusion — a 2026 playbook in one paragraph
Conjunctivitis therapeutics is a market of predictable growth but nuanced opportunity. With an expected mid‑single‑digit CAGR and a near‑term market size comfortably above the mid‑single‑billion USD range, 2026 is the year to convert strategic intent into operational commitments: defend franchise value against generics, pursue targeted M&A to fill capability gaps, harden supply chains, and build payer evidence that unlocks premium pricing for differentiated formulations and delivery systems. PW Consulting’s full report arms leaders with the models, scenarios, and playbooks to make those decisions with confidence.
For access to the full dataset, segment‑level forecasts, and customizable scenario modelling kits, please contact PW Consulting’s Healthcare Strategy practice to arrange a briefing and download the full Worldwide Conjunctivitis Ophthalmic Drugs Market report.
For detailed analysis of this topic, please visit the official page: Worldwide Conjunctivitis Ophthalmic Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com