

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Electrical Systems in Ships Market to Rise from USD 6,200 Million (Base Year 2025) to USD 9,666.7 Million by 2032 at a 6.55% CAGR (Forecast 2026–2032) — Asia Pacific Leads with USD 2,479.1M; Top 5 Firms Command 58.2%

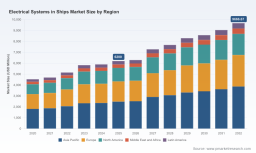
Worldwide Electrical Systems in Ships Market — Strategic Outlook for 2026: A PW Consulting Brief
PW Consulting is pleased to announce the release of our latest market research report, Worldwide Electrical Systems in Ships Market (base year 2025, forecast 2026–2032). This briefing summarizes the strategic implications for companies making critical investment, product, and partnership decisions in 2026. The global market for shipboard electrical systems has expanded materially over the past five years and is projected to continue growing at a steady pace—our model shows a compound annual growth rate (CAGR) of 6.55% across the 2026–2032 forecast window. In monetary terms (USD, revenue unit: Million), the market has evolved from a 2020 baseline of 4,530 to an estimated 6,200 in 2025 and is projected to reach approximately 9,667 by 2032.
Worldwide Electrical Systems in Ships Market
Why this report matters to 2026 decision-makers
-
Momentum behind ship electrification is no longer niche. Decarbonization mandates, tightening energy-efficiency regulations, and fleet electrification programs are transforming power architectures across commercial, offshore and defense fleets. These structural drivers create multi-year demand visibility for integrated electrical systems, energy storage and propulsion control.
Worldwide Electrical Systems in Ships Market -
Market growth is accompanied by shifting supplier economics. Rising power requirements onboard vessels increase demand for copper and marine-grade cabling, while battery technology and power electronics become central cost and technical differentiators. Procurement strategies and supply‑chain resilience will materially affect margin capture and time-to-revenue in 2026 and beyond.
Worldwide Electrical Systems in Ships Market -
Competitive actions—partnerships, targeted divestments and new-build contracts—have accelerated. Recent transactions and contract awards signal realignment among systems integrators, OEMs and specialist battery suppliers, with knock-on effects for go-to-market tactics and M&A agendas.
What the PW Consulting report delivers (practical, actionable content)
Our report balances executive-level strategic guidance with operationally relevant tools. Key deliverables include:
-
Market sizing and an audited forecasting model (2026–2032) with scenario toggles for alternative decarbonization and regulation outcomes.
-
System‑level total cost of ownership (TCO) templates—covering power generation, distribution, propulsion control and energy management—tailored to newbuild and retrofit economics.
-
Competitive benchmarking and go-to-market playbooks: vendor scorecards, capability maps and contracting archetypes.
-
Supply‑chain risk matrix including raw‑material exposure, lead‑time sensitivities and localization levers for critical components.
-
Investment cases and M&A heatmaps identifying where consolidation, partnerships or bolt‑on acquisitions are most value accretive.
-
Regulatory scenario planning and compliance roadmaps that translate maritime safety and energy management rules into product and service requirements.
Note: This briefing highlights the report’s strategic value; segment-level tables, regional breakdowns and contract-level revenue data are intentionally reserved for the full report to support proprietary decision-making.
Market dynamics shaping 2026 strategies
-
Fleet electrification is driving demand across multiple vessel classes. Public-sector fleet programs and private operator commitments are moving from pilots to fleet-scale procurement—creating opportunities for integrated suppliers and for niche specialists to scale through partnerships.
-
Strategic repositioning among incumbent suppliers. Recent corporate moves—including the divestment of an integrated marine electrical systems business by a major engine and systems provider—demonstrate a strategic sharpening across OEMs and the entrance of non‑traditional buyers into systems integration.
-
Partnerships between systems integrators, shipyards and battery specialists are consolidating go-to-market advantage. High‑visibility contract awards for hybrid-electric ferries and collaborative R&D projects for offshore support vessels illustrate how project-level alliances can leapfrog single-vendor capability gaps.
-
Input‑cost and compliance pressures are rising in parallel. Copper and specialized cabling remain core to electrical distribution and are increasingly a procurement consideration in long-term project costing. Concurrently, updated safety and energy regulations are accelerating upgrade cycles for existing fleets.
Competitive landscape: what to watch in 2026
The market is moderately concentrated (our concentration analysis shows meaningful share held by the top firms) but remains contestable across systems and services. Leading integrators and platform suppliers bring differentiating strengths:
-
Large systems integrators and equipment OEMs: Players with end‑to‑end portfolios—covering power generation, propulsion drives, distribution and automation—are best positioned to capture complex newbuild contracts and integrated retrofit packages. Their scale enables global service networks and turnkey delivery for fleet electrification programs.
-
Specialist energy storage and battery firms: Firms focused on maritime battery systems are essential partners for electrification, and their technology roadmaps determine key performance, safety and lifecycle economics in hybrid solutions.
-
Engine and propulsion specialists: Companies combining propulsion expertise with electrical systems can offer compelling hybrid architectures, especially where high integration between prime movers and electrical controls reduces system complexity.
-
System component suppliers and niche integrators: Smaller firms focused on switchboards, shore power solutions, converters and power management bring valuable modularity to projects and can be rapid acquisition targets for larger integrators seeking capability fill.
Strategic plays by stakeholder
-
For systems integrators and OEMs: Accelerate modular product lines, lock in long‑term supply agreements for key raw materials, and pursue alliances with battery suppliers. Use pilot project wins to build standardized delivery packages that reduce design‑to‑installation timelines.
-
For shipowners and operators: Prioritize lifecycle cost modelling over first‑cost procurement. Demand interoperability and standardized interfaces to protect future upgrade options and avoid vendor lock‑in. Consider long‑term service agreements to convert CapEx into predictable OpEx where feasible.
-
For shipyards: Invest in pre‑integrated structural elements and digital twin capabilities to shorten assembly and testing cycles. Show demonstrable compliance to emerging regulatory frameworks to win public and large‑operator contracts.
-
For component suppliers and battery makers: Secure qualification programs with lead integrators and focus on maritime‑specific safety certifications. Be prepared for volume scaling by 2027–2029 as large fleet programs move into execution.
-
For investors and M&A teams: Target bolt‑on technology plays that expand system integration capability or provide proprietary energy‑storage IP. Divest non‑core, capital‑intensive operations where scale benefits are limited.
2026 timing: near-term priorities that change outcomes
Given the market’s projected trajectory—with a notable step up in absolute market size in 2026 relative to earlier years—companies must treat 2026 as a year of execution rather than observation. Tactical priorities include:
-
Locking pilot contracts that can be rapidly scaled into program wins.
-
Establishing secured supply lines for critical raw materials and batteries to avoid pricing and lead-time shocks.
-
Positioning for public fleet electrification tenders and aligning product certifications to regional regulatory timelines.
-
Accelerating integration of energy management and digital monitoring to make retrofit offers more compelling from a risk and compliance perspective.
How PW Consulting supports your 2026 roadmap
Our research combines a disciplined quantitative model (comprehensive market-size vintage and a 2026–2032 forecast with sensitivity analysis) with deal‑level intelligence and supplier benchmarking. Clients benefit from:
-
Customized scenario runs from our forecast model to stress-test capital allocation under alternative regulatory and commodity-cost assumptions.
-
Vendor selection frameworks and RFP templates that embed TCO, safety and interoperability requirements.
-
M&A advisory and target-screening informed by capability maps and market concentration dynamics.
Next steps and access to the full intelligence
This brief is a strategic preview designed to surface the imperative for decisive action in 2026. The full PW Consulting report contains the granular segmental analytics, regional demand tables, vendor revenue benchmarks and downloadable models necessary to operationalize these insights. To obtain the comprehensive dataset, scenario models, and our practitioner playbooks, please visit our website or contact your PW Consulting advisor for access to the full report and a complimentary briefing session.
PW Consulting’s team of maritime electrification and systems-integration experts stands ready to translate this market intelligence into project roadmaps, procurement strategies and M&A execution plans—helping clients capture value across a market we forecast to expand substantially through the end of the decade.
For detailed analysis of this topic, please visit the official page: Worldwide Electrical Systems in Ships Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com