

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
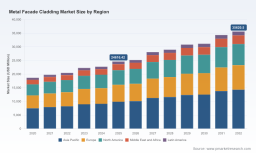
PW Consulting: Worldwide Metal Facade Cladding Market to Reach USD 24,616.42 Million in 2025, Growing at a 5.42% CAGR Through 2032

Worldwide Metal Facade Cladding Market: Strategic Outlook for 2026 — PW Consulting Intelligence Brief
Executive snapshot
PW Consulting’s new market study on the Worldwide Metal Facade Cladding sector provides a decision-grade strategic roadmap for companies preparing for 2026 and beyond. The global market — valued at approximately USD 24.6 billion in the report’s base year (2025) — is forecast to expand at a compound annual growth rate (CAGR) of 5.42% through the 2026–2032 horizon, reaching a projected market scale in excess of USD 35.6 billion by 2032. While headline growth is steady, underlying forces — raw material volatility, tightening safety and energy regulations, and evolving customer expectations for performance and aesthetics — create a complex operating context where timely strategic choices will determine winners and laggards.
Worldwide Metal Facade Cladding Market
Why this report matters for 2026 decision-making
-
Actionable foresight: The study translates macro-growth projections into practical strategic options — prioritizing where to invest, when to de-risk, and how to structure go-to-market approaches under mid-cycle inflationary pressure.
Worldwide Metal Facade Cladding Market -
Risk calibration: Material cost shocks and regulatory updates are no longer episodic concerns but primary determinants of margin and specification choices. The report quantifies sensitivity to metal price shifts and models the impact on supplier margins and tender outcomes.
Worldwide Metal Facade Cladding Market -
Competitive clarity without data overload: We map manufacturer capabilities, distribution models, and innovation trajectories to help executives identify the most viable partnership and M&A targets, while preserving detailed segment-level tables for licensed users.
What the report contains — practical intelligence for 2026
-
Market sizing and forecast framework: Annualized market values from 2020 through our base year (2025) and a year-by-year projection to 2032, with scenario overlays for inflationary and deflationary inputs.
-
Price and cost modeling: Dynamic models incorporating recent raw material moves, including recorded aluminum price upticks and supplier price actions, enabling rapid recalibration of procurement and pricing strategies.
-
Regulatory and specification playbook: Impact analysis of energy codes, fire-safety rules and sustainability certifications (e.g., LEED/BREEAM, EPBD implications), plus an operational checklist for compliance-driven product development and specification wins.
-
Supply-chain and commercial stress tests: Supplier concentration, lead-time sensitivity, and logistics risk matrices tailored to manufacturing and fabricating partners in metal cladding value chains.
-
Competitive landscaping: Profiles and strategic assessment of the market’s principal players, including their product emphases, vertical integration, and routes to market — enabling shortlists for JV partners, acquisition targets or procurement alternatives.
-
Scenario-driven playbooks: Three executable strategic pathways for OEMs, fabricators and distributors — “Protect & Optimize” (cost discipline and contract renegotiation), “Differentiate & Command” (product innovation and premiumization), and “Scale & Integrate” (roll-up and supply assurance) — with milestone-driven KPIs and investment benchmarks.
-
Commercial toolkit: Tender templates, RFP language for energy- and fire-compliant cladding, and a concise ROI calculator to evaluate material choice, lifetime maintenance and energy savings under different code assumptions.
Competitive landscape — who is shaping the market
The market remains broadly fragmented by revenue share (a low combined share of the top three and top five players), signaling continued space for regional specialists and new entrants. That fragmentation sustains competitive pressure on price but also creates opportunities for consolidation where scale and integrated capabilities matter.
-
Kingspan Group (Ireland) — Known for insulated metal panels and high-performance cladding systems, Kingspan is positioned to capture specification-driven demand in commercial and industrial projects emphasizing energy efficiency.
-
Alucobond (3A Composites; Germany/Switzerland) — A leader in aluminum composite panels (ACP), Alucobond’s strengths are lightweight, fire-rated, and highly customizable solutions that appeal to contemporary architectural programs.
-
Arconic Corporation (United States) — With established brands for high-rise facades, Arconic competes on coating technology and structural performance for tall buildings where durability and finish consistency are critical.
-
Tata Steel Limited (India) — Focused on pre-finished steel and aluminum offerings, Tata’s value proposition includes scale and sustainability messaging for cost-sensitive markets pursuing long-life building envelopes.
-
Alucoil (Spain) — Specializes in advanced ACM and lacquered aluminum systems tailored for façade, transport and industrial cladding applications where controlled aesthetics are paramount.
-
ALPOLIC (Mitsubishi Chemical) — Offers metal composite materials known for architectural versatility; strength in R&D and brand recognition supports high-end specification wins.
-
ArcelorMittal (Luxembourg) — Provides steel-based facade solutions through a building-envelope focus, leveraging integrated steelmaking and coatings know-how.
-
PAC-CLAD (Petersen Aluminum; United States) — A leading architectural panel supplier with recent commercial actions reflecting raw material cost pressure.
-
Zahner (United States) — A niche, design-led fabricator for bespoke projects relying on high craftsmanship and specialty metals such as stainless steel and copper.
-
BlueScope Steel (Australia) — Delivers pre-painted steel systems suited to large-scale commercial and industrial projects in regional markets.
-
Reynaers Aluminium (Belgium) — Focused on curtain wall and high-performance aluminium systems for energy-efficient façades.
-
Americlad (United States) — Specializes in architectural cladding fabrication and modular solutions that speed installation and reduce on-site risk.
Recent developments and market signals
-
Supplier price actions: Some fabricators announced material price increases in late 2025, reflecting upstream metal cost pressure. Procurement teams must assume base-case cost drift when negotiating 2026 contracts.
-
Pricing volatility: Independent pricing datasets recorded quarter-on-quarter aluminum price rises in Q4 2025, underscoring supply tightness in certain regions and the need for hedging or long-term supply agreements.
-
Regulatory tailwinds: Revised building-energy directives and heightened fire-safety requirements are accelerating specification shifts toward low-maintenance, fire-resistant metal systems — a structural demand driver for the forecast period.
-
Industry convenings: Key trade shows and exhibitions scheduled in 2026 will function as concentrated windows for product launches, specification capture, and alliance-building; active engagement there is a near-term commercial imperative.
Key dynamics and strategic implications
-
Margin management in a commodity-inflated environment — Tactical levers such as localized inventory buffers, index-linked contracts, and selective value-engineering can protect margins without sacrificing spec compliance.
-
Specification-driven premiumization — As energy and safety codes tighten, manufacturers that invest in validated, high-performance systems can command a price premium and secure longer-spec retention.
-
Consolidation opportunities — Low combined market shares among top players create M&A windows for firms seeking scale, particularly for fabricators with technical capability or regional distribution networks.
-
Supply-chain resilience as competitive moat — Firms that integrate upstream supply agreements, diversify metal sourcing, or develop recycled-content offerings will reduce procurement shocks and align with sustainability mandates.
Recommended strategic actions for 2026
-
Immediate: Implement short-term hedges and renegotiations to address raw material price moves; update tender templates to reflect probable cost corridors.
-
Near-term (0–12 months): Prioritize product certification and third-party testing aligned with the newest energy and fire-safety codes to preempt regulatory-based specification shifts.
-
Medium-term (1–3 years): Pursue targeted partnerships or bolt-on acquisitions that add fabrication capacity or specialized alloys; develop a differentiated “low-life-cycle-cost” product narrative grounded in validated energy performance.
-
Organizational: Strengthen commercial analytics with scenario-based pricing playbooks and embed procurement KPIs that explicitly account for lead-time and quality trade-offs.
How PW Consulting’s report helps executives act
This study is designed as a working document rather than a descriptive ledger. Alongside headline market figures and a clear 2026 strategic agenda, the deliverable includes modular tools (cost-sensitivity dashboards, negotiation playbooks, and a shortlist methodology for M&A or partnerships) that teams can deploy immediately. To preserve commercial value for clients, detailed segment-level tables, regional splits, and proprietary unit-cost templates are available exclusively in the licensed report package.
Next steps
For manufacturing executives, fabricators, investors and procurement leaders planning for 2026, PW Consulting’s Worldwide Metal Facade Cladding Market report provides the intelligence and playbooks necessary to convert market visibility into profitable action. Request access to the full report to obtain the segment-level analytics, supplier scorecards and scenario models that inform tactical procurement, product development and M&A decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Metal Facade Cladding Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com