

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Bromoacetic Acid Market Poised for 4.4% CAGR as Asia‑Pacific Emerges as Dominant Market

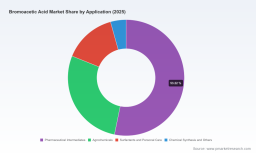
PW Consulting Strategic Brief — Worldwide Bromoacetic Acid Market Outlook: What 2026 Decisions Need to Know
Executive summary
PW Consulting’s newest market intelligence note on the Worldwide Bromoacetic Acid market synthesizes historical performance, 2026–2032 projections, regulatory shifts, feedstock dynamics, and supplier positioning into a single operational playbook for executives. Built on a 2025 base year with historical tracking from 2020–2025 and bottom‑up scenario modeling through 2032, the study concludes that the market is on a steady expansion path with a compound annual growth rate (CAGR) of 4.4% for the forecast period. In monetary terms, total industry revenue crossed the USD 176.5 Million mark in 2025 and is forecast to grow to approximately USD 187.0 Million in 2026, continuing toward mid‑to‑late‑hundreds by the early 2030s under the central scenario.
Worldwide Bromoacetic Acid Market
Why 2026 is a strategic inflection point
-
Regulatory momentum and transport reclassification in 2025–2026 are reshaping compliance costs and go‑to‑market timelines for intermediates and formulations that use bromoacetic acid.
Worldwide Bromoacetic Acid Market -
Upstream feedstock volatility — most notably in acetic acid pricing — is introducing fresh margin stress and creating arbitrage opportunities for agile producers and buyers.
Worldwide Bromoacetic Acid Market -
Market concentration is meaningful: the top three and top five suppliers capture a material share of the market, signaling both the benefits of scale and the potential for consolidation plays.
Market trajectory and what the numbers mean for strategy
Our base‑case forecast, anchored to the 2025 base year, shows a durable market expansion consistent with mid‑single‑digit CAGR dynamics (4.4% through 2032). This is driven by steady demand in pharmaceutical intermediates, agrochemical synthesis and selected specialty chemical applications. For corporate strategists, the headline takeaways are straightforward: volume growth exists, but margin resilience depends on three controllable levers — feedstock cost management, regulatory preparedness, and differentiated product positioning (e.g., reagent/technical vs. pharmaceutical grades).
Key dynamics shaping 2026 decisions
-
Regulation and compliance: The European Commission’s Implementing Decision in early 2025 extended approval timelines for certain biocidal uses — a short‑term relief for some market participants, but the inclusion of bromoacetic acid esters in the 2025 REACH Restricted Substances List creates medium‑term reformulation and substitution pressure in select end markets.
-
Transport & logistics: Bromoacetic acid’s hazardous goods classification (UN 3425, Class 8, Packing Group II) introduces higher logistics costs and handling protocols for cross‑border shipments. Procurement and operations teams must revalidate carrier approvals and insurance arrangements ahead of volume commitments.
-
Feedstock exposure: Acetic acid price swings are now a leading margin driver. For example, Northeast Asia acetic acid prices spiked to roughly USD 0.58/kg in April 2026 (a significant recent increase), while other regions show divergent trajectories. Buyers and integrated producers must implement pass‑through mechanisms or hedging strategies earlier in contract cycles.
Commercial implications — procurement, production, and product strategy
-
Procurement playbook: Shift from annual spot negotiations to dynamic sourcing frameworks. Incorporate formula‑based contracts tied to acetic acid indices and a two‑tier supplier portfolio — primary long‑term partners for continuity plus a set of opportunistic secondary suppliers to capture regional arbitrage.
-
Operational playbook: Rationalize inventory buffers to balance higher transport/handling costs against supply interruption risk. Evaluate tolling and contract manufacturing arrangements in lower‑cost geographies, but prioritize suppliers that can demonstrate compliance with hazardous goods protocols and REACH registration where relevant.
-
Product playbook: Invest selectively in grade differentiation. Producers with dual capability across technical and pharmaceutical/reagent grades command pricing premiums and access to higher‑margin niches — but that requires investment in quality systems and traceability.
Competitive landscape: practical reading of supplier positioning
The market combines a set of specialized reagent suppliers from mature markets with high‑volume exporters and bulk producers primarily located in cost‑competitive manufacturing hubs. PW Consulting’s assessment of named players yields tactical insights for sourcing, alliances, and M&A screening:
-
Vandana Chem (India) — A volume‑oriented manufacturer and exporter. Strengths: cost competitiveness, export infrastructure. Strategic implication: attractive as a secondary supplier for volume needs and flexible order sizes; less differentiated on reagent grade credentials.
-
Central Drug House (CDH) (India) — ISO‑certified producer serving both lab and industrial organic synthesis markets. Strengths: certification pedigree and established pharma supply channels. Strategic implication: suitable partner for companies requiring documented quality systems without the premium of global reagent brands.
-
Tokyo Chemical Industry (TCI) (Japan) — Global supplier focused on high‑purity reagent grades and distribution reach. Strengths: brand trust for R&D and pharma intermediates. Strategic implication: preferred for accredited research and development supply chains; premium pricing justified by reliability and documentation.
-
Merck KGaA / Sigma‑Aldrich (Germany) and Thermo Fisher Scientific / Alfa Aesar (United States) — Global reagent brands with extensive regulatory and compliance capabilities. Strengths: quality, global logistics, regulatory support. Strategic implication: default suppliers for regulated R&D and critical intermediate applications; selected for risk‑averse buyers despite higher cost.
-
Chemical Bull, Manasa Life Sciences, Ottokemi, Simson Pharma (India) and Nanjing Baijingyu (China) — Regional producers and bulk suppliers with varied specialization. Strengths: scale and regional responsiveness. Strategic implication: candidates for spot volumes, regional distribution, and cost optimization; require due diligence on compliance, batch traceability and transport readiness.
Risk matrix and scenario planning for 2026
The report includes an actionable risk matrix tailored to three near‑term scenarios: (1) Accelerated regulatory tightness, (2) Persistent feedstock inflation, and (3) Supply consolidation via M&A. For 2026 decisions, we advise companies to stress‑test P&L models against a feedstock shock of similar magnitude to the recent acetic acid swings, and to model incremental logistics cost on top of price volatility. In combination, these risks can compress margins even when top‑line volumes grow at the forecast CAGR.
What PW Consulting’s report delivers (and why you need the full study)
The publicly available summary highlights strategic directions. The full report — built for corporate decision‑makers — provides:
-
Proprietary demand forecasts (2026–2032) with scenario bands and sensitivity to raw material indices.
-
Supplier scorecards covering compliance credentials, product grade breadth, cost position, and logistics readiness — enabling rapid shortlist creation for sourcing tenders.
-
Regulatory impact matrices mapping REACH, EU biocidal decisions, and transport classification to practical timelines, remediation costs, and product substitution risks.
-
Commercial negotiation templates and price‑indexation clauses tailored to acetic acid volatility and hazardous‑goods logistics surcharges.
-
M&A and partnership screening framework identifying the most attractive targets by strategic fit (technology, quality systems, market access), and modeled synergies under multiple integration assumptions.
Consistent with our “trailer” principle, this brief demonstrates analytic depth while intentionally withholding detailed segment‑by‑segment shares and granular pricing tables that are included in the full study. Those core segmentation outputs are the strategic assets companies rely on to reconfigure sourcing footprints and to bid confidently in procurement cycles.
Immediate strategic actions for executives (90‑day playbook)
-
Initiate a rapid supplier due‑diligence sweep focused on hazardous goods compliance and REACH status; prioritize dual‑sourcing agreements where single‑source exposure exists.
-
Lock in a procurement indexation approach with major suppliers to align price pass‑throughs to acetic acid movements; negotiate caps and collars to limit downside risk.
-
Conduct a product portfolio review to identify SKUs that will be most affected by ester restrictions and transport classification changes; accelerate reformulation plans where required.
-
Explore strategic partnerships and minority investments in regional producers with logistics strength to secure capacity for medium‑term demand growth.
Conclusion — how PW Consulting supports your 2026 agenda
For companies that source, produce, or use bromoacetic acid in regulated specialty chains, 2026 is the year to convert market visibility into defensive and offensive moves: shore up compliance, redesign procurement contracts to insulate against feedstock shocks, and pursue targeted partnerships that secure access to differentiated grades. PW Consulting’s full report equips leadership teams with the quantitative forecasts, supplier assessments and contractual templates required to execute those moves decisively. For access to the complete dataset, segment tables, supplier scorecards and actionable modeling tools, please consult the full Worldwide Bromoacetic Acid Market report on our website.
For detailed analysis of this topic, please visit the official page: Worldwide Bromoacetic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com