

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Smart Carry-on Bags Market to Rise from USD 1,450.0 Million in 2025 to USD 3,501.03 Million by 2032 at a 13.42% CAGR (2026–2032) — GPS/Bluetooth & Online E‑commerce Lead

Worldwide Smart Carry-on Bags Market: Strategic Outlook for 2026
As travel rebounds and consumer expectations converge around convenience, connectivity, and safety, the smart carry-on bag market has quietly transitioned from niche novelty to strategic category. PW Consulting’s latest market study — the Worldwide Smart Carry-on Bags Market Report (base year 2025, forecast 2026–2032) — equips executives with the forward-looking, operationally actionable intelligence they need to make high-consequence decisions in 2026 and beyond.
Worldwide Smart Carry-on Bags Market
Why 2026 Is an Inflection Point
Our analysis shows that market momentum has accelerated sharply over the past five years, with global industry revenue moving from a sub‑billion niche in 2020 to approximately USD 1,450 Million in 2025. The near‑term outlook is robust: the market is forecast to expand further in 2026 and grow at a compound annual growth rate (CAGR) of 13.42% through our 2032 horizon, where total revenues approach the USD 3.5 billion mark. These macro dynamics create a narrow window for market-shaping moves — product roadmaps, channel restructuring, regulatory compliance investments, and M&A activity — that will determine market leadership for the remainder of the decade.
Worldwide Smart Carry-on Bags Market
What Matters Strategically for 2026
- Regulatory compliance is now a competitive prerequisite: 2026 introduced more restrictive dangerous-goods guidance from aviation authorities regarding lithium batteries. IATA and major regulators require removable batteries for checked luggage acceptance, and several carriers have tightened policies on non‑removable batteries for carry‑on units. These changes raise design and certification stakes: product teams must prioritize removable power modules, documented safety testing, and transparent labeling to mitigate go‑to‑market friction.
- Battery architecture will determine accessibility: The industry’s winners will be those who marry modular battery systems with retail-friendly installation and robust documentation. Airlines’ evolving policies (including outright bans by some carriers on non‑removable cells) make immutable battery design choices risky from both compliance and distribution standpoints.
- Feature sets are maturing — value lies in orchestration, not novelty: Consumers expect basic smart features (location tracking, charging, digital weighing, secure locking) as table stakes. The next value layer is seamless interoperability (app ecosystems, OTA firmware updates, data privacy) and proven reliability across multiple travel scenarios.
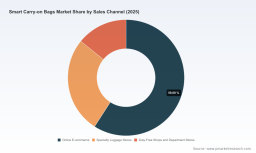
- Distribution is bifurcating: Direct‑to‑consumer brands that master online storytelling and lifetime service ecosystems will compete alongside legacy brands that leverage wholesale, airport, and specialty retail footprints. Channel strategy must therefore be tailored: premium, service‑led SKUs for DTC; certified, airline‑friendly SKUs for travel retail and duty‑free.
What the Report Delivers (Practical, Executable)
- Top‑line market sizing and a detailed seven‑year forecast calibrated to 2025 base metrics — enabling revenue and capex planning for 2026.
- Scenario models that stress‑test product and channel choices against regulatory shock events (battery rule tightening, airline prohibitions).
- Go‑to‑market playbooks for incumbents and new entrants — SKU rationalization, channel roll‑out timing, pricing ladders, and service models.
- Competitive benchmarking and capability matrices that identify feature gaps, margin levers, and partnership opportunities.
- Supplier maps and component‑level risk assessments for critical subassemblies (battery systems, tracking modules, and locks), plus suggested supplier diversification strategies.
- M&A and partnership scouting: target archetypes, valuation heuristics, and integration checklists for acquiring technology enablers (GPS/IoT platforms, battery management firms, mobile app developers).
- Retail and after‑sales strategies, including warranty policies, battery replacement programs, and airport service models to reduce friction at the point of travel.
- Regulatory and certification playbook: a checklist for product compliance across leading aviation jurisdictions and recommendations for third‑party test houses to accelerate approvals.
Competitive Landscape: Who’s Shaping the Category
The smart carry-on arena is structurally moderate in concentration: our CR3 and CR5 metrics show that the three largest firms account for under half of market sales, and the top five approach roughly half. This distribution implies meaningful opportunity for nimble challengers while underscoring the defensive advantages of incumbents with scale, brand resonance, and multi‑channel footprints.
Worldwide Smart Carry-on Bags Market
- Samsonite International S.A. (Luxembourg) — A large, diversified incumbent that leverages deep retail reach and multiple smart SKUs offering weighing, biometric locking, trackers, and integrated charging. Samsonite’s scale allows it to invest in cross‑channel service programs and certification throughput, making it a default partner for travel retailers seeking airline‑compliant options.
- Away Travel Inc. (United States) — A DTC native that built a premium brand around thoughtfully engineered baggage. Away’s strengths are product storytelling, customer lifecycle marketing, and modularity in features — a useful case study for conversion of online brand equity into service subscriptions.
- TUMI (United States), Rimowa (Germany), Delsey (France) — Premium legacy brands that differentiate on materials, design pedigree, and business traveler features. Their strategic challenge is balancing premium pricing with the added cost and logistics of compliant battery systems.
- Travelpro, Heys, Horizn Studios, Samsara, Arlo Skye, Samsara Luggage — A mix of specialized and growth-oriented players that compete on innovation (rideable designs, app‑native alerts, proprietary aluminum shells). These firms are acquisition and partnership targets for larger brands wanting to accelerate feature roadmaps.
- Airwheel Holding Ltd. (China) — Represents an adjacent mobility play, blending rideable capabilities with luggage functions; illustrates diversification paths that combine personal mobility and baggage.
Recent industry events — from trade show surges in new product launches to editorial testing and consumer reviews — confirm that product velocity remains high. However, new product velocity must be synchronized with certification cycles and airline policy updates to avoid commercial setbacks.
Where to Place 2026 Bets: Tactical Recommendations
- Prioritize removable, serviceable battery systems: Re‑engineer legacy integrated power packs into modular solutions that enable airline compliance and simplify aftermarket battery swaps. This reduces channel friction and expands addressable distribution.
- Invest in OTA and platform interoperability: A robust firmware and app strategy that supports remote lock updates, geofencing, and secure data handling will be a differentiator as consumers expect continuous improvement post‑purchase.
- Design for distribution diversity: Create SKU families aligned to channel needs — airline‑compliant cores for travel retail and premium feature bundles for DTC buyers — with harmonized service commitments to protect brand trust.
- Establish rapid certification lanes: Pre‑approved component suppliers, preferred testing houses, and proactive regulatory engagement reduce time-to-shelf and are material competitive advantages in a tightened regulatory environment.
- Consider bolt‑on acquisitions for capability acceleration: Target small GPS/IoT platform providers, battery management specialists, or app studios to compress time to market for integrated features.
Risk Matrix for 2026 Planning
- Regulatory risk: Sudden tightening of lithium battery rules can strand inventory and invalidate channel agreements; mitigation requires adaptable battery architectures and inventory contingency plans.
- Channel risk: A misaligned SKU strategy that ignores airline rules or retail compliance can lead to product delistings and costly recalls.
- Technology risk: Proprietary tracking systems without open standards may face consumer resistance; adopt hybrid architectures that preserve IP but support interoperability.
- Reputation risk: Battery incidents, even isolated, disproportionately harm companies in this category; invest in transparent safety programs and extended warranties to build consumer trust.
Conclusion — The Strategic Value of the Report for 2026 Decisions
For C‑suite executives, product leaders, and corporate development teams, PW Consulting’s report is designed as a decision‑support dossier: it pairs a rigorously validated market sizing baseline (USD 1,450 Million in 2025 with a 13.42% CAGR into our forecast window) with granular playbooks and scenario models that translate market dynamics into executable actions. Whether your objective is to defend share, accelerate innovation, pursue M&A, or redesign channel economics, the intelligence in this study materially shortens the learning curve and lowers execution risk.
We deliberately present this briefing as a strategic “trailer”: the report highlights what matters and why, while the proprietary segmentation matrices, supplier scorecards, and transaction‑level valuations are maintained behind our research portal. PW Consulting clients and decision‑makers seeking the full data assets, downloadable models, and bespoke workshop engagements for 2026 planning should contact our industry team or visit the PW Consulting reports page to request access.
For detailed analysis of this topic, please visit the official page: Worldwide Smart Carry-on Bags Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com