

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Video Inspection Robot Market at USD 2,450 Million in Base Year 2025, Poised to Reach USD 4,158.6 Million by 2032 on a 7.85% CAGR

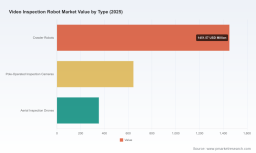
Video Inspection Robot Market Outlook 2026: Strategic Imperatives for Decision-Makers
PW Consulting's latest market research brief on the Video Inspection Robot market presents an actionable intelligence package designed to inform high-stakes procurement, R&D prioritization, and M&A decisions in 2026. Anchored on a 2025 base year, the study projects a compound annual growth rate (CAGR) of 7.85% over the 2026–2032 forecasting window. That trajectory underscores a market expanding from roughly USD 2.45 billion in 2025 to a multi-billion-dollar opportunity by 2032 — a scale that compels incumbent vendors, infrastructure owners, and private equity to re-evaluate strategy this year.
Video Inspection Robot Market
Why the 2026 decision window is decisive
-
Acceleration of replacement and inspection demand: Aging civil infrastructure, expanding utility networks, and stricter service-level mandates are increasing the frequency and scope of visual inspections. Organizations that commit budget and technical direction in 2026 will capture the most favorable deployment timelines over the next funding cycle.
Video Inspection Robot Market -
Technology inflection: The industry is shifting from simply capturing video to delivering actionable intelligence — through AI-assisted defect recognition, sensor fusion (laser profiling + sonar + video), and autonomy for large-diameter and confined spaces. Early adopters of integrated platforms will lock in operational efficiencies and higher ASPs for service models.
Video Inspection Robot Market -
Supply-chain and regulatory headwinds: Recent trade policy inquiries and tariffs affecting camera and sensor imports, together with continued supplier-side disruptions for high-precision optical components, are increasing lead times and input costs. Firms that pre-emptively adjust sourcing or secure component inventory in 2026 will reduce project risk.
-
Commercial model evolution: Buyers are moving toward outcome-based procurement (inspection-as-a-service), creating recurring revenue opportunities but demanding stronger data platforms and lifecycle support from equipment vendors.
What the report delivers — practical, decision-ready content
The PW Consulting report is deliberately built to be operational. It combines rigorous market sizing and trend analysis with executable tools for commercial teams, product leaders, and investors. Highlights include:
-
Methodology and data foundation — transparent assumptions, primary interviews, and reconciled supply-side shipment data that justify the headline sizing and growth rate.
-
Market drivers and restraints — deep qualitative and quantitative analysis of the push-pull forces shaping adoption, from labor constraints to regulatory compliance costs.
-
Technology deep dives — comparative assessments of AI-assisted video analytics, laser profiling, sonar integration, and wireless vs. tethered architectures, with deployment suitability by use case.
-
Vendor scorecards and procurement playbooks — evaluation matrices that map vendor capabilities to buyer requirements, suggested RFP language, and negotiation levers for 2026 purchasing cycles.
-
Use-case ROI models and TCO calculators — modular templates that allow asset owners to quantify inspection-as-a-service vs. capital procurement across different pipe sizes and operating environments.
-
Scenario planning and stress tests — three alternative market trajectories that model tariff shocks, sensor supply interruptions, and an accelerated shift to autonomous inspection.
-
Deal flow and M&A themes — identification of acquisition targets (software platforms, sensor specialists, service integrators) and valuation heuristics relevant to today’s private equity appetite.
Note: This press overview highlights the report’s scope and executive tools. Detailed regional and application-level splits, plus full-year-by-year segment projections, are available only in the complete report to preserve the proprietary value of PW Consulting’s modeling.
Competitive landscape — who matters and why
The market is moderately fragmented: the top three vendors account for roughly a quarter of the market by revenue, while the top five approach close to two-fifths — a structure that leaves meaningful room for consolidation and regional champions. This concentration profile implies an active battleground for technology leadership and service expansion.
-
Envirosight LLC (Randolph, NJ, USA) — A leader in sewer and pipeline crawler systems; recent product evolution emphasizes HD video capture and AI-assisted defect recognition to speed inspection workflows.
-
Deep Trekker Inc. (Kitchener, ON, Canada) — Builds pipe crawlers and underwater ROVs focused on confined-space video inspection with modular payloads for multi-environment deployments.
-
Wuhan Easy-Sight Technology (Wuhan, China) — High-volume manufacturer of pipeline CCTV systems with capabilities optimized for long-distance and sonar-augmented inspections.
-
IBAK Helmut Hunger GmbH & Co. KG (Kiel, Germany) — Noted for modular platforms that integrate panoramic video and 3D laser profiling for high-fidelity documentation of asset condition.
-
CUES Inc. (Orlando, FL, USA) — Offers truck-mounted and crawler systems tailored to municipal sewer programs; strong service ecosystem for public-sector procurement.
-
RedZone Robotics (Pittsburgh, PA, USA) — Active in autonomous and semi-autonomous inspection for large-diameter pipelines; a focus on automation is attracting utility customers seeking scale.
-
Mini-Cam Ltd. (United Kingdom) — Specialist in compact crawlers for drains and small-diameter pipelines, emphasizing portability and fast deployment.
-
iPEK International GmbH (Germany) — Known for rugged robotic CCTV systems for detailed pipeline inspection, with strong OEM and rental channels in Europe.
-
Waygate Technologies (Baker Hughes; USA/Germany) — Supplies remote visual inspection (RVI) robotics with industrial-grade video for energy and petrochemical customers.
-
Inspector Systems (Germany) — Provider of modular video and laser inspection robots spanning a wide diameter range; positions itself on flexibility and customization.
Recent vendor moves underscore two short-term imperatives: (1) embedded analytics and AI are table stakes, and (2) certified solutions for hazardous environments are unlocking energy and offshore opportunities. Representative developments include Envirosight’s 2025 launch of an AI-assisted ROVVER X HD, IBAK’s late-2025 release of panoramic 3D profiling robots, and early-2026 deployments of explosion-proof inspection robots by major industrial players.
Strategic plays for 2026 — six recommended actions
-
Prioritize platform + software integration: Buy, partner, or build analytics platforms that turn video into defect calls and maintenance tickets. Service-led models that include SaaS analytics command higher lifetime value.
-
Hedge supply-chain risk: Establish dual-sourcing for critical optics and sensors, negotiate longer-term supply contracts in 2026, and evaluate partial localization for high-volume components to mitigate tariff exposure.
-
Certify for industrial markets: For vendors pursuing energy and petrochemical segments, ATEX/IECEx and equivalent certifications will unlock higher-margin contracts; plan certification roadmaps now.
-
Design modular roadmaps: Product leaders should architect modular robots (swap-in sensors, wireless/tether options) to broaden addressable use cases without heavy internal re-engineering.
-
Target M&A selectively: Infra owners and PE should assess acquisitions that accelerate AI analytics, add inspection services in target geographies, or secure critical sensor IP.
-
Pilot outcome-based contracts: Run controlled pilots for inspection-as-a-service with clear KPIs (inspection throughput, defect detection accuracy, cost-per-meter) to build proof cases for scale.
Risks, scenarios, and mitigation
-
Tariff and trade policy shocks: Ongoing trade measures impacting camera and sensor components can raise BOM costs. Scenario planning suggests a near-term increase in COGS and longer lead times; mitigation includes pass-through pricing and inventory buffering.
-
Sensor supply disruptions: Continued shortages for high-precision optics and MEMS sensors will favor vendors with diversified supply chains or internal sourcing agreements.
-
Standards and compliance divergence: Fragmented regional safety standards could raise go-to-market complexity. Invest in modular certification strategies and global compliance expertise.
-
Competitive consolidation: A wave of M&A is plausible as larger equipment OEMs and service firms seek to consolidate software and autonomous capabilities; buyers should prepare defensive and acquisitive playbooks.
How PW Consulting’s intelligence supports your 2026 decisions
For executive teams, the report functions as both compass and toolkit. The headline market trajectory and our 7.85% forecasted CAGR provide the macro context to allocate capital, but the true value lies in the diagnostic modules — vendor scorecards, ROI calculators, and scenario-based procurement guidance — that convert market understanding into executable steps. Whether you are a municipal utility designing a five-year inspection program, a vendor defining a product roadmap, or an investor sizing acquisition opportunities, the report reduces uncertainty and prioritizes options for 2026.
To access the full dataset, segment-level forecasts, and the complete set of practical templates (including downloadable TCO models and vendor RFP language), request PW Consulting’s complete Video Inspection Robot Market report. The full package contains the proprietary tables and segment breakdowns that underpin the strategic recommendations summarized here.
For detailed analysis of this topic, please visit the official page: Video Inspection Robot Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com