

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Pipe Flanges Market Set to Reach USD 7,034.4 Million by 2032 at 4.01% CAGR; Asia‑Pacific Leads with USD 2,156.3 Million in 2025
By pmarketresearch, 2026-07-15
Worldwide Pipe Flanges Market — Strategic Preview for 2026 Decision‑Making
PW Consulting’s latest market study on the Worldwide Pipe Flanges Market synthesizes five years of historical performance, near‑term market inflection points, and a seven‑year forecast horizon to equip executive teams with the intelligence required to shape winning 2026 strategies. The market reached an estimated USD 5,342.0 Million in 2025 after recovering from pandemic‑era disruptions and price volatility; our forecast models project a steady compound annual growth rate (CAGR) of approximately 4.01% through the 2026–2032 period, culminating in a market size approaching USD 7,034.4 Million by 2032. This briefing outlines why that trajectory matters, where durable value pools are forming, and the practical moves procurement, manufacturing, and corporate development leaders must prioritize in the coming 12 months.
Worldwide Pipe Flanges Market
Why 2026 Is a Strategic Inflection for Buyers and Suppliers
Three converging forces create a narrow window in 2026 for firms to reshape cost structures and competitive positioning: (1) regulatory resets in flange standards, (2) stabilization—but not certainty—in raw material pricing, and (3) a persistently fragmented supplier base that rewards scale or highly differentiated capabilities.
Worldwide Pipe Flanges Market
- Standards and compliance: The release of ASME B16.5-2025 introduces revised pressure‑temperature ratings, tightened material definitions, and new interpretative language that changes how manufacturers certify and mark flanges. For end users this raises the bar on vendor qualification; for producers, it creates near‑term retooling and documentation costs but longer‑term opportunities to command quality premiums.
- Raw materials and cost variability: After the sharp swings of 2021–2024, global steel pricing showed signs of stabilization in early 2026 (notably in the low‑to‑mid $800s per short ton in the U.S. market). However, stainless and alloy grade differentials remain sensitive to supply disruptions and energy costs—factors that will influence material selection decisions and inventory strategies.
- Market structure: Concentration metrics indicate a highly fragmented landscape—top three players account for a modest share of the market and even the top five hold less than a quarter—creating outsized opportunity for targeted consolidation, channel optimization, and regional manufacturing investments.
What the Numbers Imply for 2026 Playbooks
Historical trends captured in the report show a market that has grown from roughly USD 4.42 billion in 2020 to USD 5.34 billion in 2025, with intermittent softness and rebounds reflecting project cycles in energy, petrochemicals, and water infrastructure. That background provides three practical implications for 2026 planning:
Worldwide Pipe Flanges Market
- Capex vs. outsourcing tradeoffs: With demand growth underpinned by steady industrial capex, firms must run scenario analyses comparing the ROI of regional factory upgrades versus strategic outsourcing to fast-turn suppliers. Our financial models quantify the breakeven points under multiple steel price and lead‑time scenarios included in the full report.
- Procurement resilience: Locking in supply agreements that incorporate ASME‑aligned specifications, volume flex provisions, and raw material pass‑through protections will reduce project risk. The strongest contracts blend price protection with quality guarantees tied to third‑party testing and traceability.
- Service differentiation: In fragmented markets, aftermarket services—rapid machining, on‑site support, and certification documentation—are increasingly decisive. Suppliers that convert standard flange sales into service contracts improve customer retention and margin profiles.
Competitive Landscape: Profiles and Strategic Moves
The industry roster ranges from specialized domestic fabricators to global steel and component groups. Leading players demonstrate two primary go‑to‑market archetypes: high‑service, fast‑turn domestic specialists and integrated, scale‑focused global manufacturers. Our competitive review profiles firms across these archetypes and evaluates strategic intent, capability gaps, and M&A vulnerability.
- High‑service specialists: Companies centered on rapid customization, strict compliance with ANSI/API/AWWA standards, and expedited delivery windows are capitalizing on project emergency needs and short‑cycle maintenance markets. These firms often emphasize wide material portfolios (carbon, stainless, alloys) and custom machining capabilities.
- Scale and integration players: Larger groups leverage upstream vertical integration (pipe and billet sourcing), broader global footprints, and long‑term OEM relationships to win large diameter and high‑volume contracts. Their investment focus is on forging, heat treatment, and automated inspection to maintain cost leadership.
- Regional champions: Several manufacturers have anchored market share by aligning plant location decisions with major infrastructure corridors and by tailoring product portfolios for local standards and project specifications.
Selected company insights in the full report include supplier scorecards for major manufacturers—highlighting manufacturing footprint, product breadth (standard vs custom), certifications, lead‑time performance, and recent strategic initiatives—allowing buyers and investors to triangulate partner suitability quickly.
Regulatory Update: ASME B16.5-2025 and Its Operational Impact
ASME’s 2025 update is not merely administrative; it has concrete production and procurement implications. The standard revises pressure‑temperature ratings, clarifies normative language (may/shall/should), and expands accepted ASTM materials—all of which influence material qualification, testing protocols, and nameplate data. Operational leaders should treat this as a project: updating procurement specifications, aligning inspection regimes, and validating supplier documentation. Early movers—those that certify processes and present compliant traceability packages—will capture higher-specification tenders and shorten approval cycles with engineering teams.
Supply‑Chain Signals and Tactical Responses
Given ongoing metal price sensitivity and episodic logistical bottlenecks, the report prescribes a six‑point tactical checklist for 2026:
- Implement hedged purchasing strategies for critical alloy inputs and evaluate pre‑purchase forward contracts for high‑use grades.
- Create modular sourcing pools: a primary regional supplier for volume, a secondary specialist for custom/urgent needs, and strategic stock at key nodes.
- Embed ASME B16.5‑compliance clauses into RFQs and supply agreements, including acceptance testing, traceability, and rework liabilities.
- Run a cost‑to‑serve review across SKU clusters to identify where in‑house machining or subcontracting changes margin dynamics.
- Use digital quoting and inspection tools to reduce bid turnaround times and lower the cost of custom orders.
- Prioritize suppliers with robust NDT and documentation systems—inspection failures are a leading cause of project delays and cost overruns.
Opportunity Areas for 2026 Corporate Development
The market’s fragmentation presents discrete M&A and partnership opportunities for buyers with capital and for incumbents seeking margin improvement. The report maps attractive targets by capability (forging vs. machining vs. heat treatment), by compliance readiness (ASME‑aligned operations), and by aftermarket service offerings. Typical value creation levers we identify include:
- Vertical integration of critical heat‑treatment or forging steps to reduce unit cost and quality variance.
- Acquiring fast‑turn regional fabricators to improve responsiveness in key demand corridors.
- Platform consolidations that pair scale producers with high‑service distributors to expand channel reach and conversion rates.
What PW Consulting’s Report Contains (Practical Deliverables)
Beyond market sizing and trend analysis, the study delivers practitioner tools designed for immediate application:
- Actionable 90‑ and 365‑day playbooks for procurement, production, and commercial teams.
- Supplier scorecards and an RFP checklist aligned to ASME B16.5‑2025 requirements.
- Five stress‑tested pricing and capex scenarios tied to raw material sensitivity analyses.
- Deal scan and integration templates for bolt‑on acquisitions and joint‑venture negotiations.
- Client‑ready slide decks and one‑page executive summaries to accelerate board‑level decisions.
How Executives Should Use This Preview to Shape 2026 Budgets
Decision makers should treat the forecast and strategic signals in this preview as the foundation for three budgetary priorities: (1) allocate funds to compliance and traceability upgrades to secure access to higher‑spec projects, (2) designate capital for selective capacity or capability purchases that shorten lead times for high‑value SKUs, and (3) reserve contingency working capital to manage raw material swings and logistics volatility. Firms that move early on these priorities will convert nominal market growth into lasting share and margin gains.
Next Steps and Access to the Full Intelligence
This article is intentionally a strategic “trailer” — designed to show depth, surface the decisive issues, and outline concrete options without disclosing the full segmentation maps and proprietary unit economics contained in the complete study. For procurement teams, M&A groups, and operations leaders preparing 2026 plans, the full report includes detailed regional demand models, SKU‑level margin matrices, supplier contact maps, and bespoke scenario tools that cannot be reproduced here.
To access the full Worldwide Pipe Flanges Market report and the supporting toolkits that translate these insights into executable initiatives for 2026, contact PW Consulting’s industry practice. Our advisors will walk you through the forecast assumptions, model sensitivities, and the customized playbooks that match your organization’s profile and risk appetite.
For detailed analysis of this topic, please visit the official page: Worldwide Pipe Flanges Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Wood Foam Market to Grow from USD 78.5 Million in 2025 to USD 247.74 Million by 2032 at a 17.84% CAGR — Europe Holds 37.5% Share
By pmarketresearch, 2026-07-15
Worldwide Wood Foam Market: Strategic Imperatives for 2026
As global manufacturers and brand owners accelerate substitution of fossil-derived materials, wood-based foams have moved from niche experiment to boardroom priority. PW Consulting’s new Worldwide Wood Foam Market report frames why 2026 will be a decisive year for strategic decisions — not only for materials teams, but for C-suite leaders setting procurement, sustainability, and capital allocation agendas. Our analysis marries granular engineering realities with commercial go-to-market playbooks, delivering the kind of decision-grade intelligence that senior executives need to act with confidence.
Worldwide Wood Foam Market
Market trajectory: scale, speed, and what it unlocks
The wood foam sector is maturing rapidly. After a period of steady growth during 2020–2025, the market reached an estimated USD 78.5 million in 2025 and is projected to expand at a compound annual growth rate of 17.84% through our 2026–2032 forecast window. By the end of that horizon the market is expected to be approaching USD 248 million. That pace of expansion represents both a demand shock and a supply-chain stress test: investors, converters and OEMs must weigh the timing and scale of investments required to capture share and to meet regulatory and customer-driven decarbonization targets.
Worldwide Wood Foam Market
Why 2026 is a strategic inflection point
- Regulatory acceleration: Policy developments — most notably packaging regulations in major markets — are shifting procurement mandates toward fiber-based, recyclable alternatives. Materials engineered for kerbside recyclability in existing paper and cardboard streams reap near-term adoption advantages.
- Sustainability as a commercial lever: High-value customers are demanding documented circularity and low-carbon feedstocks. Wood foams produced from sustainably managed forest fibers can deliver credible life-cycle advantages when substitution pathways are correctly validated.
- Scale economics on the horizon: Pilot-scale validations and early commercial agreements have proven technical viability for several product lines. The question for many players in 2026 will be whether to build, partner, license or buy capacity as cost curves evolve.
Demand dynamics and application opportunities (what to prioritise)
Wood foam is not a single-market play: it spans protective packaging, building and construction, acoustic and thermal insulation, and selected transportation components. Each application presents a distinct value equation — from regulatory-driven replacement in single-use packaging to performance-led adoption in insulation and niche transport components where weight and end-of-life are priorities. Our assessment identifies “low-friction” adoption corridors where wood foam’s mechanical and circularity attributes align directly to buyer procurement drivers; these corridors should be the immediate focus of product teams entering or scaling in this market.
Worldwide Wood Foam Market
Technology and feedstock realities
Material science advances and process engineering are central to commercial success. There are two dominant process archetypes in play: industrialized, cellulose/wood-fiber-based foams designed for cushioning and packaging; and rigid, board-style foams optimized for insulation and structural lightweighting. Research institutions and industrial developers have converged on approaches that use sustainably sourced wood fibers as primary feedstock and avoid petrochemical foaming agents — a structural difference that enables both end-of-life compatibility with paper recycling streams and a compelling carbon story when feedstock certification is secured.
From a manufacturing perspective, scaling these technologies requires attention to water management, drying energy, density control, and post-processing for dimensional stability. The players who master low-energy drying and modular production cell designs will unlock the fastest route to competitive unit economics.
Supply chain structure and market concentration
The market is already showing meaningful concentration among early industrial-scale participants. The top-tier companies control a substantial share of commercialized supply and route-to-market relationships, creating both opportunities for fast followers and barriers for late entrants. Our concentration metrics indicate that a small set of players account for the majority of today’s available commercial capacity — a dynamic that has implications for pricing power, co-manufacturing arrangements, and M&A strategies.
Competitive landscape — capabilities that matter
- Stora Enso (Helsinki): As the primary industrial supplier of Fibrease® and Papira® product lines, Stora Enso has migrated wood-foam materials from lab validation to commercial supply. Their focus on delivering recyclable, fibre-based cushioning positions them as the benchmark for packaging-oriented applications.
- Fraunhofer WKI (Braunschweig): The research institute’s process innovations for 100% wood-based foams — engineered without petrochemical additives — are critical to the insulation and lightweight construction use-cases. Fraunhofer’s work accelerates process scalability and feedstock optimization for rigid board formats.
- Sourcing & distribution partners (NOVAPOR, Nature‑Pack, Nefab): Commercialization is being enabled through sheet and finishing suppliers, exclusive distributors and packaging system integrators. These partnerships shorten time-to-market for brand owners switching from polymer foams to fibre-based alternatives.
- Regional manufacturers (Reilly Foam, JB Polymers and others): A cohort of foam manufacturers is active in adapting existing production skills to wood-fiber systems. Their success will depend on process retrofits, access to certified fiber, and strategic alliances with technology licensors or IP owners.
Recent industry developments reinforce the shift from experimentation to industrialisation: lead suppliers have announced pilot-scale commercial supply and validated production runs, while converters in adjacent foam markets are expanding capacity to capture emergent demand. These moves presage a near-term period of strategic alignment and consolidation.
What PW Consulting’s report delivers — practical, transactional, and prescriptive
Our Worldwide Wood Foam Market report is designed as an executable toolkit for decision-makers in 2026. Highlights include:
- Market sizing and forward-looking scenarios with sensitivity analyses tied to feedstock price, energy cost, and policy adoption rates.
- Supplier benchmarking and a readiness matrix that maps technical capability to commercial routes (licensing, tolling, captive manufacture).
- Go-to-market playbooks for OEMs and packagers: procurement scorecards, pilot-to-scale timelines, and contract templates for offtake and co-development.
- Capex and Opex modelling templates, including modular plant layouts and break-even analyses at multiple throughput bands.
- Regulatory compliance checklists and pathway mapping for circularity claims, with specific attention to kerbside recyclability and packaging regulation alignment.
- Case studies and vendor negotiation playbooks focused on securing sustainable wood fiber supply and forest certification.
Importantly, the report intentionally refrains from publishing granular regional or application-level splits in public summaries — we treat those as premium decision-support artifacts available through the full dataset to preserve commercial confidentiality and to enable tailored licensing of the underlying models.
Strategic recommendations for executives — six immediate actions
- Prioritize pilot projects in use-cases where regulatory tailwinds and customer willingness-to-pay converge. Shortlist those corridors for rapid scale testing.
- Secure feedstock credentials early. Long-term contracts with certified suppliers or joint-venture forest management can be decisive in delivering credible scope-3 improvements.
- Design modular investments. Opt for phased-capex plants that can switch between flexible and rigid formats or that can be replicated geographically to reduce logistic cost exposure.
- Form distribution or co-packaging partnerships rather than building end-to-end stack where time-to-market matters most.
- Embed recyclability in product specifications and validate claims with third-party assays to avoid downstream rejection in recycling streams.
- Monitor consolidation windows for opportunistic acquisitions of converters or technology assets — early consolidation is likely to reshape pricing and route-to-market dynamics.
How to use this analysis in your 2026 planning cycle
Senior leaders should treat the wood foam opportunity as a cross-functional agenda item: sustainability, operations, procurement and corporate development must coordinate around pilots, supplier commitments and capex gating. PW Consulting’s playbooks convert market projections into executable project plans, enabling teams to transition from exploratory POCs to production contracts within a 12–24 month window.
For companies evaluating market entry or competitive response, the most valuable next step is access to the full quantitative dataset, supplier scorecards and our modular financial models. The public summary intentionally signals where the opportunity is concentrated while reserving the core segmentation and granular unit-economics for clients who require bespoke scenario modelling and implementation support.
Conclusion
Wood foam represents a meaningful, fast-growing segment within the broader transition away from petrochemical-based foams. The market’s trajectory — underpinned by robust policy momentum and tangible commercial progress from leading suppliers — creates attractive windows for both first movers and disciplined fast followers. In 2026, the decisions you make about partnerships, pilot scale-ups, and capital deployment will determine whether your organization captures strategic advantage or plays catch-up in an increasingly crowded field.
PW Consulting’s Worldwide Wood Foam Market report synthesizes technical, commercial and regulatory intelligence into a single, actionable roadmap. For teams ready to turn insight into implementation, the full report provides the proprietary segmentation, supplier benchmarking, and financial models necessary to execute with precision.
Contact PW Consulting to access the full report and the downloadable decision-support toolkit that underpins our 2026 recommendations.
For detailed analysis of this topic, please visit the official page: Worldwide Wood Foam Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electrically Heated Windshield Market for EVs to Reach USD 3,043.51 Million by 2032 at a 14.12% CAGR — Asia Pacific Leads with USD 526.44M
By pmarketresearch, 2026-07-15
Electrically Heated Windshields for EVs: A Strategic Preview for 2026 Decision-Making
PW Consulting’s new market study on Electrically Heated Windshields for EVs presents a timely, actionable intelligence package aimed at executives who must convert winter-performance innovation into durable commercial advantage. The global market for electrically heated windshields has moved from niche technology to a strategic EV systems component: our model shows the market more than doubled between 2020 and 2025, reaching roughly USD 1.2 billion (Million USD) in 2025, and is forecast to grow at a compound annual growth rate (CAGR) of 14.12% across the 2026–2032 horizon to exceed USD 3.0 billion by 2032.
Electrically Heated Windshield for EV Market
Why this matters for 2026 planning
-
Energy efficiency now equals safety and comfort in EV purchasing criteria. Electrically heated windshields materially reduce HVAC load during cold-start conditions—an important lever to protect real-world driving range.
Electrically Heated Windshield for EV Market -
Electrified vehicle electrical architectures (notably the growing adoption of 48‑volt subsystems) are lowering the integration barrier for higher-power glass-based heating solutions. This is shifting heated windshields from nice-to-have luxury options into core thermal management strategy for mainstream EV platforms.
Electrically Heated Windshield for EV Market -
Market concentration is meaningful: the sector exhibits mid-to-high supplier concentration, underscoring supplier negotiation power, technology differentiation stakes, and M&A interest among glass OEMs, Tier‑1s, and new tech entrants.
Snapshot: What our numbers tell you (high-level)
Historical demand doubled in five years, driven by BEV adoption, colder-market feature expectations, and OEM-led comfort-safety differentiation. The forecast trajectory embedded in our model captures accelerating adoption as OEM platforms standardize higher-voltage architectures and as more efficient heating technologies commercialize. These macro dynamics create a multi-year runway for suppliers and OEMs, but success will hinge on integration costs, energy trade-offs, certification timeframes, and component supply resilience.
Report value: practical outputs for corporate decision-makers
-
Executive Decision Playbook: scenario-based recommendations for OEMs, Tier‑1s and suppliers to prioritize product investments, specification timing, and partnership models through 2026.
-
Market Model & Sensitivity Toolkit: a transparent forecasting engine (2026–2032) with configurable levers—adoption curves, power-architecture mix, and price erosion—that executives can use to stress-test product and pricing strategies.
-
Commercial Benchmarking: supplier scorecards that combine technical differentiation, supply capacity, certification track record, cost position, and OEM relationships—designed to support sourcing and co-development decisions.
-
Integration & Systems Guide: engineering-level checklists for electrical architecture compatibility (including 48‑volt adoption), ADAS camera/window optics considerations, and NVH/lamination trade-offs to accelerate time-to-vehicle.
-
Raw Material & Supply Risk Matrix: procurement playbooks and hedging strategies for PVB/PVA and specialty glass inputs, including scenario planning for observed price volatility and export headwinds.
-
M&A and Partnership Roadmap: valuation frameworks for acquiring or partnering with specialist technology firms (e.g., pulsed electro-thermal providers), with deal structures to protect IP and scale manufacturing rapidly.
Competitive landscape: who moves the market
Our competitive analysis blends product-level engineering differentiation with go-to-market posture. Key incumbents and challengers typify three strategic archetypes: traditional glass OEMs evolving coatings and wire embedding; specialist thermal-tech startups commercializing disruptive low-energy approaches; and OEMs internalizing glass heating to protect system-level range.
-
AGC Inc. (AGC Automotive) — plays to its glass‑OEM strengths with both conductive coating (invisible) and ultra‑fine wire approaches, positioning solutions explicitly for EV thermal management. Its dual-technology portfolio reduces client integration friction and supports multiple platform strategies.
-
Pilkington (NSG Group) — leverages established wire‑heated windshield competency and ADAS integration experience. Their proposition is speed-to-defog/defrost with compatibility for advanced driver assistance sensors—a clear value for OEMs targeting cold-climate reliability.
-
Fuyao Glass — focuses on cost-competitive manufacturing and targeted heating zones (wiper, sensor, camera) through tungsten micro-wires laminated within PVB. This zone-targeting is relevant where cost and selective functionality trump full-surface heating.
-
Saint‑Gobain Sekurit — differentiates via invisible conductive coatings (ClimaCoat) combined with heat‑reflective glass formulations, positioning for OEMs seeking integrated all‑weather performance while maintaining optical clarity for ADAS cameras.
-
Betterfrost Technologies — represents a category-defining specialist. Their pulsed electro‑thermal deicing (PETD) delivers fast clear‑times with demonstrable energy reduction versus HVAC defrost. Recent 2026 testing shows commercial traction with OEMs and Tier‑1s; this modality is attracting attention where rapid-clear times and low energy draw are prioritized.
-
Hyundai Motor Group / Genesis — as a technology adopter and developer, Genesis’ public demonstrations of a 48‑volt metal‑coated heated glass on electrified models signal a potent integrator strategy: OEMs can capture system-level energy savings by pairing glass heating with platform electrical architectures.
Collectively, these players illustrate a market in which competitive advantage will come from multi-technology roadmaps, high-quality lamination and coating expertise, fast qualification cycles for ADAS compatibility, and supply footprint close to major vehicle assembly centers.
Supply chain, raw materials, and regulatory headwinds
-
Raw material dynamics: PVB interlayers and PVA inputs remain central to lamination and wire embedding. Recent price movements and export dynamics require procurement contingency planning; small unit-cost shifts can materially change glass BOM economics at scale.
-
Certification and optical safety: electrically heated glazing must satisfy automotive glazing standards (e.g., ECE R43, FMVSS 205) while preserving ADAS camera performance. Plan for longer qualification paths where new coatings or heating topologies alter optical properties.
-
Electrical architecture fit: the rise of 48‑volt subsystems meaningfully improves the energy and integration case for higher‑power glass heaters. OEM platform strategy decisions in 2026 should explicitly include heated‑glass power budgets and harmonize with HVAC, battery thermal management, and vehicle energy management software.
Technology trajectories and trade-offs
Two technical families dominate: embedded fine‑wire heating and invisible conductive coatings; a third—pulsed electro‑thermal deicing (PETD)—is emerging as a disruptive energy-efficient alternative. Selection drivers are clear:
-
Fine wires: rapid, evenly distributed heating and proven ADAS compatibility when properly engineered; potential compromises in optical uniformity if not ultra‑fine.
-
Conductive coatings: invisible aesthetics and improved optical continuity for cameras, with power and coating durability trade-offs that require rigorous environmental testing.
-
PETD: very low steady-state energy consumption and fast clear times, but system-level integration (control electronics, pulse drivers) and long-term reliability data are still maturing.
Our report includes comparative P&L-level modeling of these approaches, showing where lifetime energy savings and customer-experience premiums offset higher unit costs.
Implications for corporate strategy in 2026
-
OEMs should codify heated‑glass strategy in platform value engineering: decide whether to insource, co-develop, or buy from established glass OEMs based on volume forecasts and ADAS requirements.
-
Glass OEMs and Tier‑1s should converge product roadmaps with electrical architecture and ADAS teams to shorten qualification cycles—time-to-spec will determine early-adopter economics.
-
Material suppliers and contract manufacturers must build price-risk mitigation into long-term supply agreements for PVB/PVA and specialty coatings.
-
Investors and M&A teams should evaluate specialists—particularly PETD providers—for bolt-on acquisitions to capture energy-efficiency differentiation, but structure earn-outs tied to OEM qualification milestones.
What’s in the full PW Consulting report (practical table of contents)
-
1) Executive summary & strategic recommendations
-
2) Market sizing & forecast model (2020–2032) with downloadable model
-
3) Segmentation analysis (region, technology, vehicle type) and adoption scenarios
-
4) Supplier benchmarking and capability heatmaps
-
5) Detailed technical annex: coating chemistries, wire metallurgy, lamination methods, and testing protocols
-
6) Procurement and raw-material risk playbooks
-
7) Integration checklists for OEM systems engineering
-
8) M&A & commercial partnership guidance with valuation templates
Note: this preview intentionally omits the granular regional, technology, and vehicle-type revenue splits that form the heart of the model. Those segment-level outputs—and supporting appendices with supplier price decks, BOM scenarios, and regional adoption curves—are available in the full report and the downloadable forecast tool.
Next steps for executives
-
Download the forecast model and run platform-specific scenarios (we provide templates keyed to battery pack size, 12/48‑volt subsystem availability, and expected cold‑climate penetration).
-
Initiate supplier dialogues using our scorecards to accelerate qualification with those that align to your integration roadmap.
-
Design pilot programs that combine one glass OEM and one PETD specialist to evaluate trade-offs across range preservation, user experience, and unit-cost outcomes within your 2026 program timelines.
PW Consulting’s Electrically Heated Windshield for EVs report is designed as a strategic instrument for 2026 planning cycles—giving you the market model, technical comparators, and commercial playbooks needed to convert winter-performance innovation into durable product and financial advantage. For access to the full dataset, supplier-level appendices, and the downloadable forecast workbook, please visit our report landing page.
For detailed analysis of this topic, please visit the official page: Electrically Heated Windshield for EV Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Non-invasive Bilirubin Meter Market to Reach USD 347.5 Million by 2032
By pmarketresearch, 2026-07-15
PW Consulting Releases Strategic Preview: Worldwide Non-invasive Bilirubin Meter Market — Actionable Intelligence for 2026 Decision Makers
PW Consulting today publishes a strategic preview accompanying our new market research on the Worldwide Non-invasive Bilirubin Meter Market (base year 2025, forecast period 2026–2032). The full study combines rigorous historic tracking (2020–2025) with scenario-tested forecasts and executable playbooks designed to support commercial, product and M&A decisions in 2026 and beyond. At a glance: the market is sized at USD 234.6 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of approximately 5.78% across the 2026–2032 forecast horizon, reaching roughly USD 347.5 Million by 2032. This release outlines the report’s strategic value while preserving the granular segment tables and proprietary models that are available only in the complete report.
Worldwide Non-invasive Bilirubin Meter Market
Why this report matters for 2026 strategy
-
Timing: 2026 is a pivotal year for manufacturers, distributors and health systems who must align product pipelines, regulatory pathways and commercial channels with accelerating demand for non-invasive neonatal diagnostics.
Worldwide Non-invasive Bilirubin Meter Market -
Risk-reduction: Buyers and investors need validated market sizing, concentration analysis and scenario modeling to de-risk portfolio allocations and acquisition targets.
Worldwide Non-invasive Bilirubin Meter Market -
Operational impact: Procurement cycles, reimbursement positioning and clinical validation plans for non-invasive bilirubin meters require coordinated cross-functional execution. Our report translates market signals into concrete operational priorities.
What the full PW Consulting report delivers — practical, decision-ready content
-
Robust market architecture and forecasting: A transparent model that explains drivers and sensitivities across the 2026–2032 forecast window, with scenario alternatives that stress-test adoption under different reimbursement and regulatory outcomes.
-
Segment-aligned go-to-market playbooks: Actionable plays for vendors selling to hospitals, clinics/pediatric centers and home-care channels, including channel economics, procurement levers and clinical value propositions.
-
Competitive and concentration analysis: An evidence-based assessment of market concentration, market leader positioning and challenger routes-to-scale that informs M&A and distribution strategies.
-
Regulation & reimbursement intelligence: A consolidation of regulatory clearances, guideline alignment and the evolving reimbursement landscape—mapped to commercial implications.
-
Technology and product roadmaps: Evaluation of sensor technologies, handheld vs. benchtop form factors, and integrations (e.g., smartphone-enabled screening) with practical recommendations on product investments and validation needs.
-
Commercial scoring and vendor due diligence templates: Ready-to-use checklists for commercial diligence, including sales force sizing, pricing sensitivity, and partner selection criteria.
-
Appendices and data toolbox: Revenue tables, model inputs, clinical references and a register of primary interviews used in analysis (note: detailed subsegment figures are reserved for the full report to preserve proprietary modeling).
Competitive landscape — concentrated but dynamic
The non-invasive bilirubin meter market is meaningfully concentrated, with the top three players commanding a majority of market share and the top five occupying an even larger portion of global revenue. This concentration underpins both barriers and strategic levers: established vendors benefit from clinical trust, distribution networks and existing purchasing relationships with neonatal care providers, while smaller manufacturers and new entrants can compete on price, niche features and rapid innovation cycles.
Key industry participants include legacy medical device manufacturers, specialist neonatal device firms and several regional OEMs. Notable companies covered and analyzed in the report include: Drägerwerk AG & Co. KGaA, Konica Minolta, major China-based manufacturers, established neonatal monitoring firms, and a set of technology-focused challengers. Our firm-level profiles synthesize product portfolios, regulatory status, distribution footprint and recent commercial moves.
Strategic takeaways from our competitive analysis:
-
Regulatory differentiation matters: Devices with clearances aligned to neonatal screening guidelines command premium positioning in hospital procurement processes. Clinical trust built through regulatory and guideline alignment accelerates adoption by neonatal units.
-
Partnerships accelerate product feature sets: Strategic collaborations—such as the recent partnership announced in mid-2024 between a leading transcutaneous jaundice meter manufacturer and a smartphone-based screening specialist—illustrate how incumbents and software innovators create new value propositions for community and home-based screening.
-
Form factor and sensor performance drive procurement choices: The market differentiates on handheld ease-of-use, benchtop throughput and sensor sensitivity. Buyers weigh capital costs against lifetime operation savings produced by reduced blood draws and lower consumable usage.
-
Channel plays vary by geography: Multinational vendors must optimize a mix of direct sales, distributor partnerships and OEM supply agreements; regional manufacturers often compete effectively on price and localized service models.
Regulatory, clinical and reimbursement dynamics shaping near-term adoption
Clinical and regulatory developments are central to adoption. Non-invasive transcutaneous bilirubin meters are positioned as estimation tools to reduce blood draws and support screening workflows, and they align with pediatric guidance for objective measurement in jaundice management. Importantly, select devices carry specific regulatory clearances that broaden their indicated use in vulnerable neonatal subpopulations—an advantage in clinical procurement evaluations.
Evidence on health-economic impact is emerging: systematic reviews indicate that transcutaneous screening can reduce readmissions for phototherapy by supporting earlier detection and outpatient management pathways. For commercial teams, this establishes both a clinical value proposition and a reimbursement argument that can be translated into bundled procurement proposals with health systems.
Five strategic imperatives for decision makers in 2026
-
Prioritize regulatory strategy early. Position device claims to meet guideline endpoints that matter to neonatal clinical committees. A targeted 510(k) or equivalent clearance can materially shorten sales cycles in key markets.
-
Invest in clinical evidence that maps to procurement economics. Randomized and real-world studies demonstrating reduced readmissions or lower lab consumption unlock both buyer trust and payer conversations.
-
Partner with digital health innovators. Integrations with smartphone triage apps, telehealth platforms or hospital EMRs expand the use-cases for non-invasive screening and create recurring value beyond one-time device sales.
-
Design channel economics for each buyer segment. Hospitals, outpatient pediatric centers and home-care customers have distinct procurement behaviors. Tailored leasing, service and training bundles increase adoption and lifetime value.
-
Use M&A strategically to fill capability gaps. For mid-sized device firms, acquisitions can accelerate entry into geographies or add complementary technologies (e.g., high-sensitivity sensors or digital interpretation algorithms) faster than organic development.
How to use PW Consulting’s report in your 2026 planning
For C-suite leaders, the report serves as a playbook to prioritize investment, plan regulatory filings and align commercial channels. For business development and M&A teams, the vendor profiles, concentration metrics and scenario valuations provide a practical shortlist and valuation orientation. For product and clinical teams, the technology assessment and evidence roadmaps inform R&D priorities and clinical trial design.
We designed the deliverables to be operational: downloadable financial models, a commercial scorecard template, vendor due-diligence questionnaires and negotiation checklists that can be applied immediately to vendor evaluations, tender responses and partnership discussions. To preserve analytical rigor and confidentiality, the report contains the full set of segmented tables and financial models behind our public summary—these are available in the full research package.
Next steps and where to access the full study
PW Consulting’s full Worldwide Non-invasive Bilirubin Meter Market report provides the granular segmentation, vendor revenue tables and detailed forecasting models that senior teams need to act in 2026. The preview above highlights the strategic direction and the executable plays; the complete study contains the proprietary subsegment metrics and the scenario models that power capital allocation and commercial planning.
Organizations ready to convert insight into action should contact PW Consulting to request the full report and schedule a tailored briefing. Our analysts will walk through the models, debrief the competitive intelligence and map the most relevant plays for your business objectives in 2026.
PW Consulting. Insight to action — commercial intelligence for leaders shaping neonatal diagnostics and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Non-invasive Bilirubin Meter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Steady Growth for Worldwide Rubella Treatment Market — 3.62% CAGR Projected for 2026–2032
By pmarketresearch, 2026-07-15
Worldwide Rubella Treatment Market 2026 Outlook: Strategic Insights for Executive Decision-Making
PW Consulting’s latest market brief on the Worldwide Rubella Treatment Market provides an evidence‑based strategic compass for healthcare executives, public health planners, investors and R&D leaders preparing for 2026 and beyond. Grounded in a five‑year historical base (2020–2025) with 2025 as the base year and a robust forecast window through 2032, the report crystallizes how incremental market growth, regulatory dynamics and supply‑chain realities will shape competitor advantage and program implementation across public and private care settings. The global market, measured in USD Million, recorded a significant rebound to an estimated USD 1,251.0 Million in 2025 and is forecast to expand at a compound annual growth rate (CAGR) of 3.62% across 2026–2032, reaching roughly USD 1,604.6 Million by 2032.
Worldwide Rubella Treatment Market
Why this briefing matters for 2026 strategy
- Strategic timing: 2026 is a pivotal year for immunization programs and commercial positioning. Recent regulatory milestones, evolving public‑health targets and renewed attention to vaccine delivery technologies create both opportunities and competitive pressure.
- Action orientation: The report is designed to convert macro trends into boardroom actions—portfolio prioritization, supply‑chain hedging, regulatory engagement plans and M&A screening criteria.
- Rapidly converging inputs: Epidemiological guidelines, vaccine approvals and cold‑chain constraints are converging to reshape procurement priorities and service delivery models. Leaders who translate these signals into operational changes in 2026 can materially improve uptake and cost‑effectiveness.
Market snapshot: trajectory and structure
After volatility in the early 2020s, the rubella treatment market stabilized and strengthened into 2025. Measured in USD Million, the market reached an estimated USD 1,251.0 Million in 2025. Our forecast scenario—underpinned by conservative uptake assumptions in routine immunization programs and incremental private‑sector demand—projects a mid single‑digit growth profile (CAGR 3.62%) through 2032, culminating in an approximate market size of USD 1,604.6 Million. This trajectory reflects steady vaccination program investment, incremental vaccine introductions and sustained demand for supportive medications and immunoglobulins used in prophylactic and passive immunization contexts.
Worldwide Rubella Treatment Market
Market concentration is notable: the combined share of the top three firms is in the mid‑60% range (CR3 ~64.25%), while the top five capture nearly four‑fifths of the market (CR5 ~79.8%). This concentration indicates material competitive barriers—scale, regulatory licensed portfolios and established procurement relationships—that new entrants must navigate.
Worldwide Rubella Treatment Market
Key demand and supply drivers
- Public‑health policy continuity: Routine MMR vaccination schedules remain the primary demand engine. Continued endorsement and financing by global and national immunization programs underpin base demand and create a predictable volume environment for established producers.
- Regulatory momentum and approvals: Recent approvals of established MMR products in major markets have immediate procurement implications and affect brand planning, labeling strategies and national tender outcomes.
- Delivery innovation: Needle‑free and micro‑needle delivery systems are emerging as differentiators for coverage in hard‑to‑reach populations, potentially reducing reliance on cold‑chain‑intensive campaigns and improving campaign efficiency.
- Cold‑chain and manufacturing complexity: Live attenuated vaccines require specific cell‑culture platforms and robust temperature management from manufacture to administration; bottlenecks or raw‑material volatility can cascade into allocation challenges in procurement cycles.
- Therapeutic gap and exploratory antivirals: There are no approved antiviral drugs for treating acute rubella infection—clinical management remains supportive. However, exploratory research (e.g., in vitro activity reported for broad‑spectrum agents) signals a potential, albeit uncertain, future adjunct to immunization strategies.
Competitive landscape—who to watch
The rubella treatment market remains anchored by established vaccine manufacturers with global production, registration footprints and procurement relationships. Several players stand out for strategic relevance in 2026:
- Merck & Co., Inc. (United States) — A long‑standing supplier of combination MMR vaccines, leveraging established clinical data, broad market access and integrated manufacturing capabilities. Expect continued emphasis on demonstrated safety profiles and large‑scale supply commitments.
- GlaxoSmithKline (GSK) (United Kingdom) — Recent regulatory approvals for its MMR product in major markets have implications for tender cycles and brand positioning. GSK’s activity highlights how regulatory milestones can unlock immediate procurement and distribution opportunities for incumbent and challenger brands alike.
- Sanofi Pasteur (France) — A global pediatric vaccine franchise with an emphasis on combination vaccines and public‑sector supply agreements. Strategic focus for Sanofi centers on portfolio stability and engagement with national immunization programs.
- Large regional manufacturers — Major producers in Asia that supply high‑volume, cost‑competitive vaccines to domestic and export markets are central to achieving global coverage targets, particularly where price sensitivity and public funding drive procurement.
- Innovators in delivery and adjuncts — Firms developing needle‑free technologies and exploratory antiviral programs are strategically important, even if they currently command a small share of revenue. Their value lies in potential to reshape program delivery and expand access.
PW Consulting’s landscape analysis emphasizes the interplay between global incumbents’ scale and regional manufacturers’ price competitiveness. The net effect is a market that offers both defensive plays for large integrators and targeted opportunities for niche innovators—especially where delivery technology or local production is a procurement preference.
Regulatory and clinical context shaping decisions
- Treatment profile: There are no specific, approved antiviral treatments for rubella infection; clinical care is supportive (e.g., antipyretics and hydration). This creates a structural reliance on preventive measures—primarily vaccination—and on passive immunoprophylaxis where indicated.
- Exploratory therapeutics: Laboratory evidence indicates some broad‑spectrum agents show in vitro inhibition of rubella virus replication, but clinical translation is unproven and years away from regulatory validation. Organizations considering therapeutic pipelines should allocate investment conservatively and prioritize translational studies.
- Immunization policy: MMR vaccines remain embedded in routine childhood immunization schedules supported by WHO and most national programs. Policy continuity reduces demand volatility but raises the bar for new entrants who must demonstrate programmatic fit and cost‑effectiveness.
Strategic implications and recommended moves for 2026
For executives and investors, the 2026 decision window should focus on three prioritized arenas where action yields outsized returns:
- Portfolio and portfolio sequencing: Rebalance vaccine and supportive‑care portfolios to reflect stable, immunization‑driven demand while maintaining optionality for delivery innovations. For incumbents, protect manufacturing capacity and secure long‑term procurement contracts; for challengers, target niches where delivery tech or local production confers procurement advantage.
- Supply‑chain resiliency and cost optimization: Invest in redundant cold‑chain capacity, diversify raw‑material suppliers and negotiate flexible contract terms with national purchasers. Scenario planning for cold‑chain disruptions should be a standard line‑item in 2026 budgets.
- Regulatory and payer engagement: Use 2026 to accelerate dossier readiness for new markets, align real‑world evidence initiatives with national program metrics, and prepare health‑economics dossiers that address vaccine scheduling and delivery cost offsets.
- Partnership and M&A playbook: Given market concentration and procurement dynamics, targeted partnerships (e.g., licensing agreements with regional manufacturers or distribution partnerships with local players) offer faster market access than greenfield expansion. M&A screening should prioritize complementary manufacturing capacity, cold‑chain capabilities and established procurement relationships.
- Innovation and access models: Pilot needle‑free delivery in high‑impact geographies where campaign logistics drive dropout rates. Such pilots can create rapid wins in coverage and form the basis for larger scale rollouts backed by programmatic evidence.
What the PW Consulting report delivers (practical, not academic)
Our report is built for operationalization. Subscribers will receive:
- Executive dashboards summarizing market size, near‑term scenarios and sensitivity to immunization uptake and price movements (note: full segment‑level tables and regional splits are reserved for subscribers to protect competitive integrity and to encourage direct engagement with our analysts).
- Actionable competitive heatmaps identifying where procurement windows open by geography and by product class, with playbooks for rapid response bids.
- Supply‑chain risk matrices and a procurement negotiation toolkit, including clauses for capacity guarantees and cold‑chain contingencies.
- Regulatory pathway maps for priority markets and a template for post‑approval real‑world evidence to accelerate reimbursement and formulary inclusion.
- M&A and partnership screening criteria with valuation heuristics and integration checklists tailored to vaccine and delivery technology assets.
Methodology and transparency
The analysis is based on a combination of primary interviews with public‑health purchasers, manufacturers and delivery innovators, alongside secondary literature, regulatory filings and PW Consulting’s market model. The study period covers 2020–2025 historically, with projections through 2032. Financials are stated in USD and reported in millions for comparability. Concentration metrics (CR3 and CR5) reflect observed procurement shares and licensed supply volumes, offering a realistic view of competitive dynamics.
Final prospectus: converting insight into advantage in 2026
For executive teams, 2026 presents a clear mandate: translate stable, immunization‑driven demand into strategic positioning that leverages manufacturing scale, supply‑chain resilience and differentiated delivery technologies. The rubella treatment market is not a high‑growth outlier, but its strategic importance—rooted in population health priorities and procurement scale—makes it mission‑critical for vaccine manufacturers and healthcare strategists. PW Consulting’s Worldwide Rubella Treatment Market report equips leaders with a pragmatic roadmap: diagnose the structural drivers, prioritize the operational levers, and execute partnership and regulatory plays that secure share and demonstrate public‑health impact.
To access the full analysis—complete segment breakdowns, region‑level forecasts, supplier scorecards and the proprietary decision tools that underpin the recommendations above—visit our report page or contact a PW Consulting analyst. The core intelligence that will materially influence procurement, R&D prioritization and partnership strategy in 2026 is available to stakeholders who need to act now.
For detailed analysis of this topic, please visit the official page: Worldwide Rubella Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Aluminium Sulfate Market to Grow at a 3.8% CAGR (2026–2032) as Water Treatment Drives Demand
By pmarketresearch, 2026-07-15
Worldwide Aluminium Sulfate Market — Strategic Outlook for 2026 Decision-Making
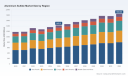
PW Consulting’s latest market study on the Worldwide Aluminium Sulfate market synthesizes multi-year historical data (2020–2025), forward-looking scenario models (2026–2032), and practical playbooks for executives making near-term investment, procurement, and commercial decisions. At a glance, the global market is positioned to expand from USD 1,422.5 Million in the base year (2025) to approximately USD 1,846.9 Million by 2032, representing a compound annual growth rate (CAGR) of 3.8% over the forecast period. These headline figures mask important volatility drivers and structural shifts — our report decodes those forces and translates them into executable options for 2026.
Worldwide Aluminium Sulfate Market
What this report delivers — actionable intelligence, not academic summary
- Robust demand and supply modelling calibrated to 2020–2025 actuals and stress-tested across three macroeconomic scenarios for 2026–2032. Each scenario includes demand elasticity, price sensitivities, and feedstock-price transmission matrices.
- Practical procurement and hedging playbooks tied to raw-material dynamics (alumina hydrate and sulfuric acid), with contract templates, cost-pass-through thresholds, and tipping points for spot vs. long-term sourcing.
- A capital-allocation toolkit: CAPEX/OPEX benchmarks, plant-scale break-evens, and an investment prioritization matrix to support brownfield expansion, debottlenecking, or new-build projects.
- Competitive landscape diagnostics with capability maps and an M&A target shortlist—scored by strategic fit, geographic access, and asset quality—plus integration risk templates.
- Regulatory and trade-risk assessments, including import-duty scenarios and product classification implications, with compliance checklists tailored to major markets.
- Commercial playbooks for price segmentation, channel optimization, and value-added product development (including technical grades for water treatment, paper & pulp, textiles, and specialty applications).
Key market dynamics shaping 2026 choices
Three structural themes should govern executive planning in 2026:
Worldwide Aluminium Sulfate Market
- Feedstock and input-cost transmission: Alumina hydrate and sulfuric acid constitute the primary upstream cost base. Recent market intelligence shows alumina hydrate averaged near USD 385/metric ton in 2023, while sulfuric acid experienced an elevated band in Q4 2023 driven by fertilizer demand. These inputs create asymmetrical cost pass-through across regions and product grades. Procurement strategies that combine indexed contracts, regional supply diversification, and limited-term hedging will outperform static sourcing approaches.
- Trade policy and market access: Trade measures remain a material commercial constraint. For example, the US maintains anti-dumping duties on certain imports, reshaping global flows and pricing differentials. Companies that map tariff exposure to route-to-market strategies (local production, tolling, or bonded distribution) will retain margin control while protecting market share.
- Regulatory and sustainability pressures: Classification and environmental rules influence formulation choices and water-treatment acceptance. Notably, aluminium sulfate remains classified as non-hazardous for recognized water-treatment uses under relevant EU frameworks — a certainty that reduces compliance cost for municipal contracts but does not eliminate scrutiny related to lifecycle carbon and effluent management. Integrating low-carbon feedstock paths and transparent LCA data into bids will become a differentiator in procurement tenders.
Competitive landscape: fragmentation and strategic positions
The market exhibits moderate concentration: the top three players account for approximately 32.4% of industry sales, and the top five for around 46.8%. This structure creates pockets of competitive intensity and frequent regional leadership changes. Key incumbents and strategic considerations include:
Worldwide Aluminium Sulfate Market
- USALCO, LLC (Baltimore, MD, USA) — Strengths in liquid and dry grades for municipal and industrial water treatment. Plays to watch: leveraging solution-chemistry expertise to extend service contracts and move from commodity sales toward lifecycle water-treatment partnerships.
- Chemtrade Logistics Income Fund (Toronto, Canada) — High-purity alum producer with integrated logistics capabilities. Competitive advantage arises from combining chemical manufacturing with distribution optimization; a logical acquirer or partner for firms seeking North American market access or logistics resilience.
- GEO Specialty Chemicals, Inc. (Ambler, PA, USA) — Technical-grade supplier with multiple domestic sites. Strategic focus: specialty formulations for textiles and leather tanneries; growth lever is cross-selling technical coagulants into adjacent municipal accounts.
- GFS Chemicals, Inc. (Columbus, OH, USA) — Laboratory and industrial focus creates a high-margin niche. Opportunity: expand reagent lines into standardized bulk grades for municipal clients to stabilize volatility in specialty volumes.
- Kemira Oyj (Helsinki, Finland) — Global reach and aluminum-based coagulation expertise. Strategic strengths include integrated R&D and global sales channels; key decision is where to invest for capacity versus service-led differentiation.
- Ataman Kimya A.S. (Izmir, Turkey) and major Chinese and Indian producers — Several regional producers export granular and liquid grades. Their strategic advantage is cost-competitive capacity, but trade measures and freight volatility alter competitiveness. Near-term moves include deploying regional tolling hubs or entering distribution alliances to circumnavigate tariff barriers.
Implications for 2026 strategy — prioritized moves
Executives should prioritize a concise set of actions in 2026 to capture upside while containing downside risk:
- Revise procurement architecture: Adopt a layered sourcing model mixing (a) multi-year indexed contracts with select low-cost producers, (b) shorter spot windows to capture downward cycles, and (c) regional buffer inventories. Embed sulfuric-acid and alumina hydrate price triggers into supply contracts to enable pass-through or shared-risk clauses.
- Reassess capacity strategy: Before committing to greenfield plants, deploy brownfield debottlenecking and modular expansions. Our CAPEX calculator identifies scale thresholds where greenfield becomes advantaged — use it to vet projects against a 3.8% CAGR baseline and downside demand shocks.
- Value-over-volume commercial moves: Shift select accounts from commodity supply to service contracts (e.g., dosing expertise, performance SLAs) to protect margins, particularly in municipal water-treatment segments where long-term contracts are common.
- Trade and tax engineering: Model duty-impact scenarios and prepare alternative routing (third-country transshipment, local finishing) to mitigate punitive tariffs. Where legal, structure tolling or JV arrangements to preserve market access.
- M&A and partnerships: Target acquisitions should be prioritized for capability (technical grades), geographic access (distribution footprints), or feedstock integration. Our M&A scorecard ranks targets across commercial fit, asset quality, and regulatory exposure to accelerate screening.
- ESG and product stewardship: Build LCA-backed product claims for low-carbon alum lines and establish transparent effluent monitoring for major municipal contracts. This is both a procurement differentiator and a medium-term compliance hedge.
Risk matrix and contingency planning
Principal risks for 2026 include input-price spikes, abrupt trade-policy shifts, and localized demand shocks tied to municipal capex cycles. Our report maps these risks into probability-impact quadrants and provides pre-scripted contingency responses — from temporary margin-sharing contracts to rerouting supply chains and accelerated product substitution campaigns for exposed customer cohorts.
How PW Consulting’s analysis helps you act in 2026
Beyond headline forecasts, PW Consulting delivers models and templates designed for immediate operational use: procurement negotiation playbooks, a CAPEX prioritization toolset, regional tariff-impact simulators, and a proprietary margin-sensitivity dashboard that translates input-price moves into customer-level P&L outcomes. We intentionally present high-level findings here to demonstrate methodological rigor while reserving granular segmentation tables, company-level volume/price splits, and interactive scenario files for the full report package.
Next steps — use the intelligence, not just the numbers
For executives planning capital deployment, contract renegotiations, or market-entry strategies in 2026, the operative advantage will come from combining macro-forecast awareness with executional templates. PW Consulting’s Worldwide Aluminium Sulfate report is structured to convert market insight into operational action: detailed datasets, supplier scorecards, and negotiation-ready clauses are available in the full deliverable.
To access the full analysis, proprietary datasets, and the interactive decision-support tools referenced above, please visit the PW Consulting report page for the Worldwide Aluminium Sulfate Market. The full package contains the segment-level tables, regional and application breakdowns, and company-level metrics that informed the strategic recommendations summarized here.
For detailed analysis of this topic, please visit the official page: Worldwide Aluminium Sulfate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Cosmetic-Grade Retinol Market Poised to Expand at a 6.92% CAGR Through 2032
By pmarketresearch, 2026-07-15
PW Consulting — Strategic Outlook: Worldwide Cosmetic Grade Retinol Market (Official Release)
Executive summary
Cosmetic grade retinol remains one of the most strategically significant actives in personal care formulations, straddling premium anti‑aging propositions and broad mass‑market usage. Our latest Worldwide Cosmetic Grade Retinol Market report establishes a clear picture of that strategic value: the market reached approximately USD 1,465.5 Million in the base year 2025 and is forecast to expand at a compound annual growth rate (CAGR) of 6.92% across the 2026–2032 horizon, reaching roughly USD 2,341.0 Million by 2032 under the central case. For 2026 specifically, the market trajectory and regulatory inflection points make this report a practical roadmap for commercial, regulatory and R&D decisions.
Worldwide Cosmetic Grade Retinol Market
Why this report matters for 2026 decision‑making
- Regulatory inflection will redraw addressable formulations: New concentration caps and labeling mandates in key markets are driving reformulation and portfolio reclassification. Companies that preemptively align product specifications, dosages and labeling with the incoming regime will avoid costly recalls and speed time‑to‑market for reformulated SKUs.
- Margin pressure vs. premiumization tension: Supply dynamics favor both scale providers and specialist delivery platforms. Players must balance cost efficiency with differential delivery technologies (stabilized and encapsulated forms) to defend price realization while protecting clinical claims.
- Supply chain due diligence becomes a strategic lever: The raw material base for cosmetic retinol is concentrated among synthetic routes (and a subset of extraction pathways). Securing validated suppliers with traceable quality systems and contingency capacity is now a boardroom priority.
- M&A and partnership windows are narrowing: With mid‑single‑digit CAGR and pockets of high strategic value (stabilized grades, encapsulation technologies, regulatory‑compliant formulations), 2026 is likely to see accelerated bolt‑on activity and JV discussions—especially where incumbents seek to internalize specialty delivery capabilities or geographic downstream access.
What the report delivers — practical, operational modules
Our research team structured the report to be directly usable in strategy workshops, procurement negotiations and R&D prioritization. Key deliverables include:
Worldwide Cosmetic Grade Retinol Market
- Market sizing and forward scenarios: Base‑year 2025 market sizing, historical trends (2020–2025) and three forecast scenarios to 2032. These scenarios isolate demand drivers such as premium anti‑aging adoption, mass‑market acne/brightening reformulation cycles, and regulatory impact pathways.
- Regulatory impact matrix and compliance playbook: A jurisdiction‑by‑jurisdiction analysis that translates concentration limits, labeling obligations and timelines into product‑level actions and compliance milestones—allowing product teams to prioritize SKU updates by risk exposure and commercial upside.
- Supply chain and sourcing toolkit: Supplier risk heatmaps, capacity shock simulations, and a validated shortlist of global and regional raw material providers with suggested contractual clauses (quality audits, force majeure, IP protections) to reduce continuity risk.
- Formulation & innovation briefing: Comparative evaluation of stabilization and delivery technologies, clinical endpoints commonly pursued with retinol actives, and a prioritization framework for internal R&D investments versus external technology partnerships.
- Commercial segmentation playbooks: Go‑to‑market templates for premium, masstige and mass channels that align formulation attributes, price architecture and communication strategies—designed to accelerate cross‑functional implementation.
- M&A and partnership screening: Financial and strategic screening criteria, sample term sheet considerations and integration checklists tailored to acquisitions of specialty ingredient providers, encapsulation technology firms or downstream private labels.
Regulatory and market dynamics shaping 2026
Two regulatory themes dominate near‑term strategy:
Worldwide Cosmetic Grade Retinol Market
- Harmonized concentration limits and mandatory consumer messaging in Europe: Recent measures set explicit maxima for retinol equivalents in topical products and mandate on‑pack language signaling the presence of Vitamin A and guidance on cumulative intake. These rules include staged implementation dates for new versus existing stock, creating an interim window for controlled rollouts and label updates.
- U.S. market governance and facility oversight: Continued implementation of modernized cosmetic regulatory frameworks increases the administrative burden on manufacturers and contract formulators. Facility registrations, product listings and upcoming GMP requirements raise the bar for supplier qualification and audit readiness.
These regulatory shifts are not merely compliance items; they change product economics and consumer communication strategy. Brands that replatform formulas to maintain efficacy at lower permitted concentrations, or that invest in delivery systems that demonstrate superior bioavailability or reduced irritation, will preserve premium positioning and claim substantiation.
Supply base and raw material realities
Cosmetic grade retinol continues to be produced primarily via controlled synthetic routes from established precursors, with high‑purity powder forms standard for bulk supply. The market features a mix of global specialty suppliers and larger chemical conglomerates, as well as regional manufacturers that provide scale and cost advantages. The report includes a supply concentration assessment and contingency playbooks for managing quality, lead times and import risk across primary sourcing corridors.
Competitive landscape — where incumbents and challengers create advantage
Market concentration metrics indicate a moderately consolidated supplier landscape, with the top three and top five players holding meaningful but not dominant combined shares. This structure yields strategic choices for brands and CPG firms:
- BASF SE (Ludwigshafen, Germany): A global leader noted for stabilized retinol grades and “clean” formulations. Recent product introductions that omit legacy stabilizers align with retailer and consumer demand for cleaner ingredient panels. Their scale and formulation expertise make them a default partner for large CPG clients seeking low‑risk reformulation pathways.
- DSM‑Firmenich (Heerlen, Netherlands): Positions innovation around derivative and stabilized vitamin A chemistries with a strong sustainability narrative. Their strength is in differentiated dosage forms and corporate sustainability frameworks attractive to brands targeting eco‑conscious consumers.
- Evonik Industries AG (Essen, Germany): Specialist in encapsulated delivery technologies; their platforms aim to reduce irritation while increasing retinol stability—attributes that directly support premium claim differentiation and regulatory compliance at constrained concentrations.
- Croda International Plc (Snaith, UK): Brings bio‑based ingredient credentials and formulation support, enabling brand stories that combine efficacy with sustainability—an increasingly important axis for market segmentation.
- Regional producers and high‑purity suppliers (selected European and Chinese manufacturers): Several manufacturers provide high‑purity bulk retinol and derivative forms at competitive cost and scale. They are strategic partners for price‑sensitive product lines, but require robust quality assurance and supply continuity oversight to meet the standards of premium buyers.
Strategically, buyers should segment supplier relationships: centralized, long‑term contracts with global majors for stabilized, compliance‑ready grades; tactical spot or regional contracts with volume producers to manage cost; and innovation partnerships with encapsulation specialists to maintain product differentiation.
Using this report in your 2026 playbook
Senior teams can apply the report directly in four areas:
- Portfolio triage: Map SKUs to regulatory risk and margin contribution to prioritize reformulation or phase‑out timelines.
- Procurement optimization: Re‑design sourcing strategies using the supplier risk matrix and contract templates to reduce unit cost volatility and secure capacity through 2032 scenarios.
- R&D and claims strategy: Use the formulation briefing to choose between higher‑potency stabilized grades and encapsulated delivery depending on tolerated irritation profiles and intended claims.
- M&A and alliance planning: Apply the M&A screening tool to identify bolt‑on targets that accelerate entry into encapsulation, sustainability credentials, or regional manufacturing footprints.
Methodology & what we intentionally withhold
The analysis rests on a combination of primary interviews with ingredient suppliers, brand formulators and trade channel experts; proprietary shipment and pricing datasets; synthesis of public regulatory texts; and bottom‑up capacity modeling. The report’s base year is 2025 with historical coverage from 2020–2025 and forecasts to 2032, all presented in USD (Million).
In line with our “teaser” approach for this release, we present robust macro sizing, scenario outcomes and supplier concentration metrics to support strategic planning, but detailed segment and regional breakouts—including exact regional market shares and application‑level revenue splits—are reserved for the full report and interactive data portal. This ensures you receive the granular intelligence required for direct commercial execution and negotiation.
Next steps — how to engage
For leadership teams preparing 2026 budgets and strategic initiatives, the report functions as both a short‑term playbook and a long‑range market map. PW Consulting can support bespoke deliverables: supplier due diligence packages, expedited formulation workshops, and M&A target screening based on criteria aligned to your strategic intent. Access to the full dataset and appendices (including the granular segmentation and supplier scorecards) is available through PW Consulting’s report portal and advisory services.
For detailed analysis of this topic, please visit the official page: Worldwide Cosmetic Grade Retinol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Skeletal Dysplasia Treatment Market Set to Soar at a 14.05% CAGR
By pmarketresearch, 2026-07-15
Worldwide Skeletal Dysplasia Treatment Market — PW Consulting Strategic Brief (Official Release)
Executive summary
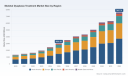
PW Consulting’s newest market study, Worldwide Skeletal Dysplasia Treatment Market (base year 2025; historical 2020–2025; forecast 2026–2032), delivers the actionable intelligence life‑science executives need to make high‑stakes decisions in 2026. At the macro level the market has more than doubled in five years—from roughly USD 1.35 billion in 2020 to about USD 3.03 billion in 2025—and is modeled to continue robust expansion, reaching some USD 7.61 billion by 2032. Our forecast period (2026–2032) carries a compound annual growth rate of 14.05% (USD, Million), reflecting accelerating therapeutic innovation, shifting regulatory pathways, and payer re‑pricing pressure.
Worldwide Skeletal Dysplasia Treatment Market
Why this report matters for 2026 decision makers
- Actionable horizon: 2026 is a pivot year—recent regulatory events and late‑stage readouts are crystallizing commercial windows and reimbursement risk for multiple modality classes.
- Resource allocation: R&D, manufacturing scale‑up, and market access investments must be prioritized against a compressed window to capture share as new entrants move from approval to launch.
- Competitive dynamics: The market exhibits relatively high concentration among the top firms, yet the pipeline and oral/injectable modality diversification create meaningful displacement risk for incumbents.
- Strategic optionality: Our report turns market momentum into ready‑to‑execute options—launch sequencing, payer evidence plans, partnership targets, and M&A scenarios—tailored for 2026 planning cycles.
What the report contains (practical, executable content)
- Comprehensive market model (2020–2032) in USD Million with scenario toggles for regulatory outcomes, price points, and uptake curves—designed to integrate into corporate planning tools.
- Competitive playbooks for new approvals and late‑stage assets, including go‑to‑market timelines, launch resource templates, and first‑90‑day market activation checklists.
- Payer and HTA engagement blueprints that translate clinical endpoints into reimbursement evidence packages, plus modeled cost‑utility thresholds across major HTA regimes.
- Regulatory and reimbursement risk matrices (accelerated approvals, confirmatory trial contingencies, conditional coverage scenarios) with mitigation playbooks and trigger points.
- M&A and alliance screening: prioritized lists of targets and partners by capability gap (commercial infrastructure, manufacturing, biomarker/data platforms) together with valuation sensitivities under multiple uptake scenarios.
- Customizable slide decks, executive summaries, and one‑page decision frameworks to expedite board and investor communication in 2026 planning cycles.
Market dynamics shaping 2026 strategy
Three forces dominate the near‑term landscape: (1) regulatory acceleration, (2) modality diversification, and (3) payer evidence demand. Accelerated approvals granted or expected in early 2026 have shortened the interval between clinical proof and commercial availability; however, these approvals commonly carry confirmatory obligations that materially affect life‑cycle economics and reimbursement negotiation leverage. Simultaneously, therapeutic diversity—weekly peptide analogs, once‑daily oral small molecules, biologics and surgical/supportive care pathways—creates complex share‑shifting scenarios. Finally, payers are increasingly conditioning coverage on hard functional outcomes and long‑term proportionality or morbidity benefits rather than growth velocity alone.
Worldwide Skeletal Dysplasia Treatment Market
Competitive landscape: who to watch and why
- BioMarin Pharmaceutical Inc. — An established leader with the first approved targeted therapy that changed the treatment paradigm for children with achondroplasia. BioMarin’s ongoing clinical evidence generation—most recently publicized data highlighting early treatment effects on proportionality and arm span—reinforces a durable incumbency but also exposes the company to head‑to‑head and modality substitution risk as oral and less frequent dosing competitors emerge.
- Ascendis Pharma A/S — Now an approved contender in 2026 with a once‑weekly long‑acting CNP prodrug. The novel dosing profile opens differentiated positioning with physicians and caregivers focused on adherence and quality‑of‑life, but accelerated approval pathways require robust confirmatory plans that will drive near‑term R&D and real‑world evidence expenditure.
- BridgeBio Pharma / QED Therapeutics — A small‑molecule entrant reporting positive Phase 3 topline results for an oral FGFR3 inhibitor. Oral delivery and potential effects on body proportionality represent a commercial inflection point should regulatory filings proceed as planned. Breakthrough Therapy Designation and imminent NDA/MAA filings introduce meaningful upside and competitive pressure on pricing and line‑share dynamics.
Implications of recent developments (Feb–Mar 2026)
- Regulatory acceleration increases first‑mover value but amplifies reimbursement negotiation complexity; contingency clauses linked to confirmatory trials are now a structural feature for several therapies.
- Clinical data that show benefits beyond growth velocity—such as improvements in proportionality or functional measures—are becoming critical differentiators for both clinicians and payers.
- Oral FGFR inhibition, if approved, has the potential to reframe patient and clinician preferences, increase market segmentation by modality, and pressure pricing benchmarks used in HTA assessments.
Market structure and concentration
The market shows significant concentration at the top: the three largest firms account for a substantial majority of market share, with the five largest firms representing over four‑fifths of the market. For incumbents this implies defensibility in core segments but also heightened vulnerability to disruptive entrants whose mechanisms or dosing profiles command clinical preference. For new entrants, concentration means that partnerships, targeted regional strategies, or niche differentiation will be essential to gain commercial traction quickly.
Worldwide Skeletal Dysplasia Treatment Market
Strategic recommendations for 2026 planning
- Prioritize evidence that matters: Redirect pivotal and post‑marketing studies toward endpoints payers value (long‑term functional outcomes, surgery avoidance, QoL gains) rather than relying solely on surrogate growth metrics.
- Design launch packages for conditional coverage: Prepare staged market access strategies that link reimbursement to registry‑based outcome verification and risk‑sharing agreements.
- Build modality playbooks: For injectables, focus on specialty clinic onboarding and caregiver support; for orals, emphasize adherence programs and primary‑care integration.
- Scenario‑based manufacturing planning: Align capacity investments to a tiered uptake model—rapid adoption, moderate uptake with price erosion, and delayed uptake contingent on confirmatory success.
- Explore strategic partnerships: Consider licensing, co‑promotion, or regional distribution agreements to accelerate launch in geographies where local clinical champions and payer pathways differ materially.
- Protect pricing through value communication: Translate proportionality and functional outcomes into economic models that resonate with hospitals and national payers (reduction in surgeries, long‑term care costs, productivity gains).
- Prepare for M&A arbitrage: Use our valuation sensitivities to identify targets whose real option value (biomarker platforms, manufacturing, novel modalities) can be unlocked through acquisition.
How to use this report in your 2026 decision cycle
- Quarterly strategic reviews: Integrate the market model into FY26 revenue and capex planning; re‑run scenarios as confirmatory trial readouts and regulatory decisions are announced.
- Market access playbooks: Deploy payer blueprints in parallel with launch readiness to shorten time‑to‑coverage.
- M&A and partnership screening: Apply our scoring matrix to prioritize targets for diligence based on strategic fit and upside under multiple uptake assumptions.
- Investor and board engagement: Use our board‑grade one‑page summaries and sensitivity charts to communicate upside and downside risk succinctly.
What we deliberately withhold here—and why
To preserve the strategic value of the full study and adhere to PW Consulting’s “trailer” principle, we have intentionally omitted detailed regional, indication, and treatment‑type splits from this release. The full report contains granular segmentation tables, country‑level uptake models, and pricing matrices that are essential for definitive launch sequencing, HTA submissions, and M&A valuation. These datasets are available through the full report and interactive model on our website for clients and authorized subscribers.
Next steps and how to obtain the full study
Executives seeking to convert the 2026 inflection into competitive advantage should request the full Worldwide Skeletal Dysplasia Treatment Market report, which includes the complete market model (USD, Million), detailed segmentation, proprietary scenario engines, and tailored consulting workshops for rapid implementation. PW Consulting also offers bespoke briefings to map the report’s outputs into corporate R&D, commercial and M&A roadmaps.
For board‑level inquiries, custom analytics, or to schedule a rapid briefing on 2026 tactical options, contact PW Consulting’s Industry Practice. The full dataset and model will enable you to set defensible budgets, negotiate with payers, and time market entry to maximize shareholder value in this fast‑evolving market.
For detailed analysis of this topic, please visit the official page: Worldwide Skeletal Dysplasia Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com