

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Worldwide Skeletal Dysplasia Treatment Market Set to Soar at a 14.05% CAGR

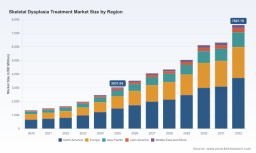
Worldwide Skeletal Dysplasia Treatment Market — PW Consulting Strategic Brief (Official Release)
Executive summary
PW Consulting’s newest market study, Worldwide Skeletal Dysplasia Treatment Market (base year 2025; historical 2020–2025; forecast 2026–2032), delivers the actionable intelligence life‑science executives need to make high‑stakes decisions in 2026. At the macro level the market has more than doubled in five years—from roughly USD 1.35 billion in 2020 to about USD 3.03 billion in 2025—and is modeled to continue robust expansion, reaching some USD 7.61 billion by 2032. Our forecast period (2026–2032) carries a compound annual growth rate of 14.05% (USD, Million), reflecting accelerating therapeutic innovation, shifting regulatory pathways, and payer re‑pricing pressure.
Worldwide Skeletal Dysplasia Treatment Market
Why this report matters for 2026 decision makers
- Actionable horizon: 2026 is a pivot year—recent regulatory events and late‑stage readouts are crystallizing commercial windows and reimbursement risk for multiple modality classes.
- Resource allocation: R&D, manufacturing scale‑up, and market access investments must be prioritized against a compressed window to capture share as new entrants move from approval to launch.
- Competitive dynamics: The market exhibits relatively high concentration among the top firms, yet the pipeline and oral/injectable modality diversification create meaningful displacement risk for incumbents.
- Strategic optionality: Our report turns market momentum into ready‑to‑execute options—launch sequencing, payer evidence plans, partnership targets, and M&A scenarios—tailored for 2026 planning cycles.
What the report contains (practical, executable content)
- Comprehensive market model (2020–2032) in USD Million with scenario toggles for regulatory outcomes, price points, and uptake curves—designed to integrate into corporate planning tools.
- Competitive playbooks for new approvals and late‑stage assets, including go‑to‑market timelines, launch resource templates, and first‑90‑day market activation checklists.
- Payer and HTA engagement blueprints that translate clinical endpoints into reimbursement evidence packages, plus modeled cost‑utility thresholds across major HTA regimes.
- Regulatory and reimbursement risk matrices (accelerated approvals, confirmatory trial contingencies, conditional coverage scenarios) with mitigation playbooks and trigger points.
- M&A and alliance screening: prioritized lists of targets and partners by capability gap (commercial infrastructure, manufacturing, biomarker/data platforms) together with valuation sensitivities under multiple uptake scenarios.
- Customizable slide decks, executive summaries, and one‑page decision frameworks to expedite board and investor communication in 2026 planning cycles.
Market dynamics shaping 2026 strategy
Three forces dominate the near‑term landscape: (1) regulatory acceleration, (2) modality diversification, and (3) payer evidence demand. Accelerated approvals granted or expected in early 2026 have shortened the interval between clinical proof and commercial availability; however, these approvals commonly carry confirmatory obligations that materially affect life‑cycle economics and reimbursement negotiation leverage. Simultaneously, therapeutic diversity—weekly peptide analogs, once‑daily oral small molecules, biologics and surgical/supportive care pathways—creates complex share‑shifting scenarios. Finally, payers are increasingly conditioning coverage on hard functional outcomes and long‑term proportionality or morbidity benefits rather than growth velocity alone.
Worldwide Skeletal Dysplasia Treatment Market
Competitive landscape: who to watch and why
- BioMarin Pharmaceutical Inc. — An established leader with the first approved targeted therapy that changed the treatment paradigm for children with achondroplasia. BioMarin’s ongoing clinical evidence generation—most recently publicized data highlighting early treatment effects on proportionality and arm span—reinforces a durable incumbency but also exposes the company to head‑to‑head and modality substitution risk as oral and less frequent dosing competitors emerge.
- Ascendis Pharma A/S — Now an approved contender in 2026 with a once‑weekly long‑acting CNP prodrug. The novel dosing profile opens differentiated positioning with physicians and caregivers focused on adherence and quality‑of‑life, but accelerated approval pathways require robust confirmatory plans that will drive near‑term R&D and real‑world evidence expenditure.
- BridgeBio Pharma / QED Therapeutics — A small‑molecule entrant reporting positive Phase 3 topline results for an oral FGFR3 inhibitor. Oral delivery and potential effects on body proportionality represent a commercial inflection point should regulatory filings proceed as planned. Breakthrough Therapy Designation and imminent NDA/MAA filings introduce meaningful upside and competitive pressure on pricing and line‑share dynamics.
Implications of recent developments (Feb–Mar 2026)
- Regulatory acceleration increases first‑mover value but amplifies reimbursement negotiation complexity; contingency clauses linked to confirmatory trials are now a structural feature for several therapies.
- Clinical data that show benefits beyond growth velocity—such as improvements in proportionality or functional measures—are becoming critical differentiators for both clinicians and payers.
- Oral FGFR inhibition, if approved, has the potential to reframe patient and clinician preferences, increase market segmentation by modality, and pressure pricing benchmarks used in HTA assessments.
Market structure and concentration
The market shows significant concentration at the top: the three largest firms account for a substantial majority of market share, with the five largest firms representing over four‑fifths of the market. For incumbents this implies defensibility in core segments but also heightened vulnerability to disruptive entrants whose mechanisms or dosing profiles command clinical preference. For new entrants, concentration means that partnerships, targeted regional strategies, or niche differentiation will be essential to gain commercial traction quickly.
Worldwide Skeletal Dysplasia Treatment Market
Strategic recommendations for 2026 planning
- Prioritize evidence that matters: Redirect pivotal and post‑marketing studies toward endpoints payers value (long‑term functional outcomes, surgery avoidance, QoL gains) rather than relying solely on surrogate growth metrics.
- Design launch packages for conditional coverage: Prepare staged market access strategies that link reimbursement to registry‑based outcome verification and risk‑sharing agreements.
- Build modality playbooks: For injectables, focus on specialty clinic onboarding and caregiver support; for orals, emphasize adherence programs and primary‑care integration.
- Scenario‑based manufacturing planning: Align capacity investments to a tiered uptake model—rapid adoption, moderate uptake with price erosion, and delayed uptake contingent on confirmatory success.
- Explore strategic partnerships: Consider licensing, co‑promotion, or regional distribution agreements to accelerate launch in geographies where local clinical champions and payer pathways differ materially.
- Protect pricing through value communication: Translate proportionality and functional outcomes into economic models that resonate with hospitals and national payers (reduction in surgeries, long‑term care costs, productivity gains).
- Prepare for M&A arbitrage: Use our valuation sensitivities to identify targets whose real option value (biomarker platforms, manufacturing, novel modalities) can be unlocked through acquisition.
How to use this report in your 2026 decision cycle
- Quarterly strategic reviews: Integrate the market model into FY26 revenue and capex planning; re‑run scenarios as confirmatory trial readouts and regulatory decisions are announced.
- Market access playbooks: Deploy payer blueprints in parallel with launch readiness to shorten time‑to‑coverage.
- M&A and partnership screening: Apply our scoring matrix to prioritize targets for diligence based on strategic fit and upside under multiple uptake assumptions.
- Investor and board engagement: Use our board‑grade one‑page summaries and sensitivity charts to communicate upside and downside risk succinctly.
What we deliberately withhold here—and why
To preserve the strategic value of the full study and adhere to PW Consulting’s “trailer” principle, we have intentionally omitted detailed regional, indication, and treatment‑type splits from this release. The full report contains granular segmentation tables, country‑level uptake models, and pricing matrices that are essential for definitive launch sequencing, HTA submissions, and M&A valuation. These datasets are available through the full report and interactive model on our website for clients and authorized subscribers.
Next steps and how to obtain the full study
Executives seeking to convert the 2026 inflection into competitive advantage should request the full Worldwide Skeletal Dysplasia Treatment Market report, which includes the complete market model (USD, Million), detailed segmentation, proprietary scenario engines, and tailored consulting workshops for rapid implementation. PW Consulting also offers bespoke briefings to map the report’s outputs into corporate R&D, commercial and M&A roadmaps.
For board‑level inquiries, custom analytics, or to schedule a rapid briefing on 2026 tactical options, contact PW Consulting’s Industry Practice. The full dataset and model will enable you to set defensible budgets, negotiate with payers, and time market entry to maximize shareholder value in this fast‑evolving market.
For detailed analysis of this topic, please visit the official page: Worldwide Skeletal Dysplasia Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com