

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Pipe Flanges Market Set to Reach USD 7,034.4 Million by 2032 at 4.01% CAGR; Asia‑Pacific Leads with USD 2,156.3 Million in 2025

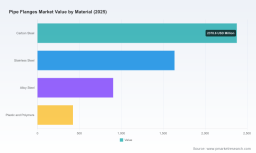
Worldwide Pipe Flanges Market — Strategic Preview for 2026 Decision‑Making
PW Consulting’s latest market study on the Worldwide Pipe Flanges Market synthesizes five years of historical performance, near‑term market inflection points, and a seven‑year forecast horizon to equip executive teams with the intelligence required to shape winning 2026 strategies. The market reached an estimated USD 5,342.0 Million in 2025 after recovering from pandemic‑era disruptions and price volatility; our forecast models project a steady compound annual growth rate (CAGR) of approximately 4.01% through the 2026–2032 period, culminating in a market size approaching USD 7,034.4 Million by 2032. This briefing outlines why that trajectory matters, where durable value pools are forming, and the practical moves procurement, manufacturing, and corporate development leaders must prioritize in the coming 12 months.
Worldwide Pipe Flanges Market
Why 2026 Is a Strategic Inflection for Buyers and Suppliers
Three converging forces create a narrow window in 2026 for firms to reshape cost structures and competitive positioning: (1) regulatory resets in flange standards, (2) stabilization—but not certainty—in raw material pricing, and (3) a persistently fragmented supplier base that rewards scale or highly differentiated capabilities.
Worldwide Pipe Flanges Market
- Standards and compliance: The release of ASME B16.5-2025 introduces revised pressure‑temperature ratings, tightened material definitions, and new interpretative language that changes how manufacturers certify and mark flanges. For end users this raises the bar on vendor qualification; for producers, it creates near‑term retooling and documentation costs but longer‑term opportunities to command quality premiums.
- Raw materials and cost variability: After the sharp swings of 2021–2024, global steel pricing showed signs of stabilization in early 2026 (notably in the low‑to‑mid $800s per short ton in the U.S. market). However, stainless and alloy grade differentials remain sensitive to supply disruptions and energy costs—factors that will influence material selection decisions and inventory strategies.
- Market structure: Concentration metrics indicate a highly fragmented landscape—top three players account for a modest share of the market and even the top five hold less than a quarter—creating outsized opportunity for targeted consolidation, channel optimization, and regional manufacturing investments.
What the Numbers Imply for 2026 Playbooks
Historical trends captured in the report show a market that has grown from roughly USD 4.42 billion in 2020 to USD 5.34 billion in 2025, with intermittent softness and rebounds reflecting project cycles in energy, petrochemicals, and water infrastructure. That background provides three practical implications for 2026 planning:
Worldwide Pipe Flanges Market
- Capex vs. outsourcing tradeoffs: With demand growth underpinned by steady industrial capex, firms must run scenario analyses comparing the ROI of regional factory upgrades versus strategic outsourcing to fast-turn suppliers. Our financial models quantify the breakeven points under multiple steel price and lead‑time scenarios included in the full report.
- Procurement resilience: Locking in supply agreements that incorporate ASME‑aligned specifications, volume flex provisions, and raw material pass‑through protections will reduce project risk. The strongest contracts blend price protection with quality guarantees tied to third‑party testing and traceability.
- Service differentiation: In fragmented markets, aftermarket services—rapid machining, on‑site support, and certification documentation—are increasingly decisive. Suppliers that convert standard flange sales into service contracts improve customer retention and margin profiles.
Competitive Landscape: Profiles and Strategic Moves
The industry roster ranges from specialized domestic fabricators to global steel and component groups. Leading players demonstrate two primary go‑to‑market archetypes: high‑service, fast‑turn domestic specialists and integrated, scale‑focused global manufacturers. Our competitive review profiles firms across these archetypes and evaluates strategic intent, capability gaps, and M&A vulnerability.
- High‑service specialists: Companies centered on rapid customization, strict compliance with ANSI/API/AWWA standards, and expedited delivery windows are capitalizing on project emergency needs and short‑cycle maintenance markets. These firms often emphasize wide material portfolios (carbon, stainless, alloys) and custom machining capabilities.
- Scale and integration players: Larger groups leverage upstream vertical integration (pipe and billet sourcing), broader global footprints, and long‑term OEM relationships to win large diameter and high‑volume contracts. Their investment focus is on forging, heat treatment, and automated inspection to maintain cost leadership.
- Regional champions: Several manufacturers have anchored market share by aligning plant location decisions with major infrastructure corridors and by tailoring product portfolios for local standards and project specifications.
Selected company insights in the full report include supplier scorecards for major manufacturers—highlighting manufacturing footprint, product breadth (standard vs custom), certifications, lead‑time performance, and recent strategic initiatives—allowing buyers and investors to triangulate partner suitability quickly.
Regulatory Update: ASME B16.5-2025 and Its Operational Impact
ASME’s 2025 update is not merely administrative; it has concrete production and procurement implications. The standard revises pressure‑temperature ratings, clarifies normative language (may/shall/should), and expands accepted ASTM materials—all of which influence material qualification, testing protocols, and nameplate data. Operational leaders should treat this as a project: updating procurement specifications, aligning inspection regimes, and validating supplier documentation. Early movers—those that certify processes and present compliant traceability packages—will capture higher-specification tenders and shorten approval cycles with engineering teams.
Supply‑Chain Signals and Tactical Responses
Given ongoing metal price sensitivity and episodic logistical bottlenecks, the report prescribes a six‑point tactical checklist for 2026:
- Implement hedged purchasing strategies for critical alloy inputs and evaluate pre‑purchase forward contracts for high‑use grades.
- Create modular sourcing pools: a primary regional supplier for volume, a secondary specialist for custom/urgent needs, and strategic stock at key nodes.
- Embed ASME B16.5‑compliance clauses into RFQs and supply agreements, including acceptance testing, traceability, and rework liabilities.
- Run a cost‑to‑serve review across SKU clusters to identify where in‑house machining or subcontracting changes margin dynamics.
- Use digital quoting and inspection tools to reduce bid turnaround times and lower the cost of custom orders.
- Prioritize suppliers with robust NDT and documentation systems—inspection failures are a leading cause of project delays and cost overruns.
Opportunity Areas for 2026 Corporate Development
The market’s fragmentation presents discrete M&A and partnership opportunities for buyers with capital and for incumbents seeking margin improvement. The report maps attractive targets by capability (forging vs. machining vs. heat treatment), by compliance readiness (ASME‑aligned operations), and by aftermarket service offerings. Typical value creation levers we identify include:
- Vertical integration of critical heat‑treatment or forging steps to reduce unit cost and quality variance.
- Acquiring fast‑turn regional fabricators to improve responsiveness in key demand corridors.
- Platform consolidations that pair scale producers with high‑service distributors to expand channel reach and conversion rates.
What PW Consulting’s Report Contains (Practical Deliverables)
Beyond market sizing and trend analysis, the study delivers practitioner tools designed for immediate application:
- Actionable 90‑ and 365‑day playbooks for procurement, production, and commercial teams.
- Supplier scorecards and an RFP checklist aligned to ASME B16.5‑2025 requirements.
- Five stress‑tested pricing and capex scenarios tied to raw material sensitivity analyses.
- Deal scan and integration templates for bolt‑on acquisitions and joint‑venture negotiations.
- Client‑ready slide decks and one‑page executive summaries to accelerate board‑level decisions.
How Executives Should Use This Preview to Shape 2026 Budgets
Decision makers should treat the forecast and strategic signals in this preview as the foundation for three budgetary priorities: (1) allocate funds to compliance and traceability upgrades to secure access to higher‑spec projects, (2) designate capital for selective capacity or capability purchases that shorten lead times for high‑value SKUs, and (3) reserve contingency working capital to manage raw material swings and logistics volatility. Firms that move early on these priorities will convert nominal market growth into lasting share and margin gains.
Next Steps and Access to the Full Intelligence
This article is intentionally a strategic “trailer” — designed to show depth, surface the decisive issues, and outline concrete options without disclosing the full segmentation maps and proprietary unit economics contained in the complete study. For procurement teams, M&A groups, and operations leaders preparing 2026 plans, the full report includes detailed regional demand models, SKU‑level margin matrices, supplier contact maps, and bespoke scenario tools that cannot be reproduced here.
To access the full Worldwide Pipe Flanges Market report and the supporting toolkits that translate these insights into executable initiatives for 2026, contact PW Consulting’s industry practice. Our advisors will walk you through the forecast assumptions, model sensitivities, and the customized playbooks that match your organization’s profile and risk appetite.
For detailed analysis of this topic, please visit the official page: Worldwide Pipe Flanges Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com