

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Forecast: Worldwide Rail Air Conditioning Market to Expand at a 6.55% CAGR During 2026–2032
By pmarketresearch, 2026-07-15
Worldwide Rail Air Conditioning Market: 2026 Playbook — Strategic Imperatives from PW Consulting’s Latest Market Study
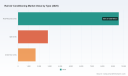
PW Consulting today releases a forward-looking briefing drawn from our comprehensive market study, Worldwide Rail Air Conditioning Market (base year 2025, forecast period 2026–2032). The global rail HVAC market has expanded from approximately USD 10.8 billion in 2020 to USD 14.05 billion in 2025, and is projected to reach roughly USD 21.9 billion by 2032, representing a 6.55% CAGR over the 2026–2032 forecast window. For rail operators, OEMs, tier‑1 suppliers and investors, 2026 represents a strategic inflection point where regulatory pressure, materials volatility and a rapid shift to energy‑efficient architectures converge to rewrite requirements for product design, sourcing and aftermarket service models.
Worldwide Rail Air Conditioning Market
Why 2026 is the decision year
-
Regulatory acceleration: European and global standards are tightening both performance and environmental thresholds. EN 14750 continues to set the bar for operational performance across extreme temperature ranges, while recent emission rules are pushing low‑GWP refrigerants and associated system redesigns into procurement checklists. These converging mandates mean equipment selected today must be validated across more severe operating envelopes and refrigerant lifecycles.
Worldwide Rail Air Conditioning Market -
Technology pivot to efficiency and electrification: System architectures are migrating toward inverter-driven compressors and brushless DC motor platforms that can cut in‑service energy use materially. Early adopters are already field‑validating these gains on high‑visibility projects, shifting evaluation criteria from initial CapEx to lifetime energy and integration cost.
Worldwide Rail Air Conditioning Market -
Supply‑chain and cost pressure: Raw material swings and labour tightness are forcing manufacturers to rework supply strategies and production footprints. The cumulative effect is higher unit production risk for suppliers that rely on commodity‑heavy designs or single‑source subassemblies.
-
Consolidation and concentrated supplier power: The market shows moderate concentration, with the top three suppliers accounting for just over 40% of value and the top five approaching 60%—a structure that magnifies the strategic importance of supplier selection, partnership models and aftermarket control.
What PW Consulting’s report delivers — practical intelligence for 2026
-
Market sizing and validated forecasts: A rigorous historical reconstruction (2020–2025) and scenario‑based projections across 2026–2032 to test upside and downside demand under policy, commodity and technology shocks.
-
Technology and product roadmaps: Comparative analyses of inverter systems, brushless DC compressors, refrigerant alternatives and modularization strategies — including lifecycle cost models that prioritize Opex sensitivity over headline CapEx.
-
Supply‑chain and cost diagnostics: Component‑level margin mapping, supplier concentration heatmaps and procurement risk matrices designed to support hedging, dual‑sourcing and near‑shoring decisions.
-
Competitive intelligence and go‑to‑market playbooks: Profiles of global incumbents and disruptive challengers, tender pipelines, and win‑loss case studies that reveal how leading suppliers are securing fleetwide contracts.
-
Aftermarket and service strategies: Opportunity sizing and commercial models for maintenance, parts, and remote diagnostics — a critical revenue pool often undervalued in RFP negotiations.
-
Decision tools: Interactive TCO calculators, certification roadmaps and project-level scenario models that translate technical choices into procurement outcomes.
Competitive landscape — who moves the market
The market remains anchored by several established global players and strong national champions. Leading firms combine system design expertise with global installation footprints, while a cohort of regional providers retains advantages on local content, service networks and price competitiveness. Recent corporate developments underscore where momentum is concentrating:
-
Knorr‑Bremse’s mid‑2025 launch of an energy‑saving HVAC platform exemplifies supplier strategies to win metro and urban transit tenders by reducing lifecycle energy consumption.
-
Alstom’s contract awards in 2025 highlight continued demand for integrated rolling‑stock HVAC packages tied to major fleet programmes.
-
Hitachi’s validation work on eco‑HVAC units for a major high‑speed project signals a rising focus on certifying next‑gen architectures for harsh operating regimes.
-
Wabtec’s supplier nominations in high‑growth markets illustrate how modular solutions are being positioned to scale rapidly in emerging fleet programmes.
-
Several Japanese OEMs and Chinese metro‑specialists continue to compete on lightweight, low‑power designs and cost competitiveness, respectively—intensifying price and spec competition across global tenders.
Supply‑chain realities and regulatory headwinds
-
Commodity exposure: Heat‑exchanger metals and electronic components remain the largest contributors to bill‑of‑materials volatility. Manufacturers that lock strategic alloy supplies and redesign for material efficiency can protect margins and delivery certainty.
-
Refrigerant transition: Regulatory moves toward very low‑GWP refrigerants necessitate system redesigns, compatibility tests and new service protocols. Product roadmaps must include refrigerant lifecycle management and training plans for depot maintenance crews.
-
Certification burden and time‑to‑market: Certification cycles for new HVAC platforms are lengthening as regulators tighten test regimes. Suppliers who invest early in modular validation and cross‑jurisdictional test campaigns gain measurable time‑to‑award advantages.
-
Labour and cost inflation: Skilled assembly and calibration remain bottlenecks in advanced markets. Manufacturers are responding with automation, standardization and targeted localization to contain build costs and lead times.
Strategic recommendations for 2026 — prioritized actions
-
Reframe procurement around TCO and integration risk, not just unit price. Include energy consumption under realistic duty cycles, refrigerant replacement scenarios, and servicing availability in all supplier scorecards.
-
Accelerate modular and scalable product strategies. Design approaches that separate core compressors, heat exchangers and control electronics reduce certification overhead and support faster customization for regional markets.
-
Lock strategic supplier partnerships for critical commodities and electronics. Hedging and framework agreements—coupled with co‑development clauses—reduce exposure to raw‑material spikes and ensure prioritized production slots.
-
Invest in retrofit and aftermarket service propositions. With fleets seeking to extend asset life while meeting new environmental rules, retrofit kits and remote monitoring packages offer higher margins and recurring revenue.
-
Prioritize certification lead indicators. Early engagement with certification bodies and targeted test campaigns shorten procurement cycles and create meaningful entry barriers for late movers.
-
Define a clear refrigerant transition roadmap. R&D programmes should model refrigerant availability, handling costs and end‑of‑life scenarios so product offerings remain compliant without disruptive redesigns.
-
Explore M&A and strategic JV opportunities focused on electronics, controls and aftermarket analytics—capabilities that are increasingly differentiating wins in competitive tenders.
How PW Consulting’s study supports executive action
Our report synthesizes quantitative market construction with qualitative, operational intelligence to produce executable recommendations. Through scenario stress‑testing, supplier heatmaps and a suite of financial tools, boardrooms can translate technical trends into procurement timelines, R&D budgets and partner selection criteria for 2026 and beyond. To maintain the market’s “trailer” principle: the public brief maps the strategic contours; the full report contains the granular segment matrices, regional buildouts, product‑type economics and supplier scorecards required to operationalize these recommendations.
Next steps
For executives preparing 2026 capital and procurement plans, the path forward is clear: act now to lock supplier relationships, prioritize energy‑efficient and low‑GWP designs, and monetize aftermarket services. PW Consulting’s Worldwide Rail Air Conditioning Market report offers the granular models and playbooks you need to convert these imperatives into measurable outcomes. Visit our report page or contact the PW Consulting advisory team to request the full dataset, interactive dashboards and a complementary strategy briefing tailored to your organisation’s role in the rail value chain.
For detailed analysis of this topic, please visit the official page: Worldwide Rail Air Conditioning Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Fibers & Electromagnetic Shielding Market to Expand at 7.91% CAGR, Hitting USD 13,866.23 Million by 2032
By pmarketresearch, 2026-07-15
Worldwide Fibers and Electromagnetic Shielding Market: Strategic Imperatives for 2026
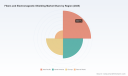
PW Consulting's latest market study — Worldwide Fibers and Electromagnetic Shielding Market (base year 2025) — reframes how executives should approach materials, supply chains, and product roadmaps in an era where electromagnetic compatibility and lightweight conductive solutions are mission-critical. The global market has expanded rapidly over the past half-decade, with total industry revenue climbing from roughly USD 5.7 billion in 2020 to more than USD 8.1 billion in 2025. Under our central scenario, the sector is projected to grow at a compound annual growth rate of 7.91% through the 2026–2032 forecast window, reaching fresh scale and complexity by 2032. This report is purpose-built to convert those macro trends into concrete decisions for procurement, engineering, and corporate strategy in 2026.
Worldwide Fibers and Electromagnetic Shielding Market
Why 2026 Is a Strategic Inflection Point
Several concurrent forces make 2026 pivotal for companies active in fibers and electromagnetic shielding. First, accelerated adoption of electronics across automotive, telecom, medical, and defense systems is lifting demand for integrated shielding solutions that balance weight, form factor, and attenuation performance. Second, technology advances — from metallized yarns to transparent silver-nanowire films and conductive polymer formulations — are creating differentiated product pathways but also new validation burdens. Third, supply-side pressures and regulatory overhead are materially reshaping competitiveness: raw material cost volatility (notably for silver and other precious metals) and stricter RoHS/REACH validation requirements are increasing total cost of ownership and time-to-market for advanced conductive solutions.
Worldwide Fibers and Electromagnetic Shielding Market
Market structure matters. The industry exhibits moderate consolidation: the top three players control a material share of global revenue that indicates leading suppliers set quality and spec benchmarks, while the top five firms extend near-term influence over technology roadmaps and distribution channels. For buyers and technology owners this creates both risk (single-source exposures) and opportunity (co-development with market leaders).
Worldwide Fibers and Electromagnetic Shielding Market
What the PW Consulting Report Delivers — Practical, Operational Insights
- Robust market sizing and scenario modeling: annualized top-line estimates and three forward demand scenarios to stress-test growth assumptions across 2026–2032.
- Supply-chain and cost-decomposition tools: bill-of-materials level visibility, commodity sensitivity matrices, and supplier concentration heatmaps to quantify procurement risk.
- Technology readiness and adoption roadmaps: comparative assessments of conductive fibers, metallization techniques, conductive polymers, and coating systems, including manufacturability and scale constraints.
- Regulatory and compliance playbook: timelines and cost impacts for RoHS/REACH validation, recommended test protocols, and mitigation pathways to accelerate approvals.
- Competitive intelligence and partner shortlists: supplier profiles, capability-cluster mapping, and M&A screening criteria tailored to strategic buyers and private equity investors.
- Commercialization accelerators: sample go-to-market frameworks, EVA-based pricing models, and a checklist for embedding shielding into system-level product design.
We intentionally present the report as an operational toolkit rather than an academic catalog: every chapter includes actionable templates, decision trees, and workshop modules that can be deployed immediately within procurement, R&D, and corporate development teams.
Competitive Landscape — Who Matters and Why
The competitive map is multi‑polar: global diversified materials firms, specialized textile and metallization houses, and niche compounders each play distinct roles in value chains.
- Parker Hannifin (Chomerics division) — Strengths: integrated elastomeric and gasket solutions, deep aerospace and defense certifications. Strategic implication: ideal partner for sealed or high-reliability enclosure applications where mechanical resilience and conductivity must coexist.
- 3M Company — Strengths: wide portfolio of tapes, laminates and films; strong channel reach into electronics and industrial OEMs. Strategic implication: OEMs seeking scale and predictable supply should evaluate tape/film integration early in product design.
- Henkel AG & Co. KGaA — Strengths: conductive adhesives and polymer-based approaches with automotive-grade process capability. Strategic implication: valuable collaborator for bonding-integrated shielding and weight-optimized assemblies.
- Laird Performance Materials (DuPont affiliate) — Strengths: high-performance fabrics and composites targeting telecom and high-frequency use-cases. Strategic implication: prime for co-development of RF-optimized textile solutions and thermal management hybrids.
- Bekaert — Strengths: specialty stainless steel fibers and yarns used in textile shielding and protective garments. Strategic implication: suppliers seeking metallized-fiber competence and battlefield-proven textile platforms should engage early.
- RTP Company — Strengths: engineered thermoplastic compounds embedding conductive fillers. Strategic implication: rapid prototyping of EMI-shielded polymer parts and low-volume production runs benefit from RTP’s materialization expertise.
- Tech‑Etch, Holland Shielding, Shieldex, Soliani EMC, Swift Textile Metalizing, Marktek, Aaronia — Strengths: focused offerings across metallized textiles, silver-coated yarns, and technical fabrics. Strategic implication: these specialists are go-to partners for bespoke fabrications, prototyping, and niche applications.
- PPG Industries — Strengths: conductive coatings and paints compatible with composite and fiber substrates. Strategic implication: useful where conformal or large-surface shielding must be applied post-assembly.
Recent product introductions underscore the rapid evolution of the space: DuPont’s 2025 launch of silver nanowire-based inks and films points to growing adoption of transparent shielding solutions (important for ADAS displays and in-mold electronics), while regional innovators have begun delivering non-combustible EMI films suited to defense tent fabrics. Both trends illustrate the dual technical and regulatory pressures companies must reconcile in 2026.
Market Dynamics and Downside Risks
Three dynamics deserve immediate attention from executives allocating capital in 2026:
- Raw-material price volatility — Rising silver prices in early 2026 have direct cost implications for silver-coated fibers and high-performance conductive textiles. Hedging strategies and substitution analyses should be part of procurement playbooks.
- Regulatory compliance friction — Stricter testing and extended validation for nano-engineered additives and conductive fillers (RoHS/REACH) increase time-to-revenue. Upfront compliance design and certified lab partnerships reduce rework risk.
- Technology diffusion constraints — Despite the appeal of MXenes, graphene, and carbon nanotubes, their cost and manufacturing complexity limit near-term substitution in price-sensitive fiber applications. Roadmaps should balance research bets with pragmatic engineering choices.
Strategic Recommendations for 2026 Decision-Makers
- Adopt a two-track material strategy: protect high-performance products with premium conductive solutions while actively qualifying lower-cost alternatives for volume applications.
- Implement commodity and supplier hedging: prioritize contracts with price adjustment mechanisms, diversify metallization sources, and explore recycled silver or less-volatile alloys where performance permits.
- Invest in regulatory-first development: embed RoHS/REACH and relevant telecom/defense certification gates early in product timelines to avoid downstream delays.
- Pursue targeted co-development with specialized suppliers: form JVs or development agreements with textile metallizers or nanowire innovators to accelerate proprietary productization.
- Operationalize a supplier scorecard: combine technical capability, geographic footprint, lead-time resilience, and regulatory maturity to guide sourcing decisions.
- Prioritize modular shielding architectures: design with replaceable or upgradable shielding modules to accommodate rapid material advances and cost shifts.
- Screen M&A and minority investment targets against our acquisition criteria: technology defensibility, certification backlog, and customer concentration.
- Run scenario-based capital plans: stress-test capex decisions against commodity spikes, compliance-induced time-lag, and accelerated product obsolescence.
How PW Consulting Can Help
The published report provides the comprehensive data backbone and executable workstreams required to act in 2026. For teams that need quicker implementation, PW Consulting offers tailored advisory packages: rapid due-diligence for transactions, a three‑week supplier optimization sprint, or an intensive regulatory acceleration workshop that pairs your engineers with our materials scientists. For board-level strategy, we deliver condensed executive dashboards and an investor memoire that align material strategy with capex and M&A decision windows.
As a next step, procurement, R&D, and corporate development leaders should obtain the full report to access the detailed market tables, supplier matrices, and downloadable decision templates. Our "trailer" here is intentional: the executive narrative shows the strategic contours while the full dataset and operational playbooks, available through PW Consulting, supply the granular intelligence required to act decisively in 2026.
Contact PW Consulting to schedule a briefing or to commission a bespoke engagement that translates the report’s insights into a 90‑day action plan matched to your risk tolerance and growth ambitions.
For detailed analysis of this topic, please visit the official page: Worldwide Fibers and Electromagnetic Shielding Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 5.45% CAGR — Worldwide Industrial Cleaning Services Market to Reach USD 104,417.57 Million by 2032 (Base Year 2025)
By pmarketresearch, 2026-07-15
PW Consulting Launch: Strategic Preview — Worldwide Industrial Cleaning Services Market (2026 Readiness)
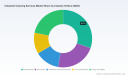
As industrial operators, service providers, and investors prepare to make material decisions in 2026, PW Consulting’s latest market study on Worldwide Industrial Cleaning Services delivers an evidence-based, decision-ready framework for competitive advantage. Built on an empirical baseline that covers 2020–2025 and forward-looking scenario modelling to 2032, the report identifies where capital and operational choices will create or erode value. The global market — estimated at USD 72,018.34 Million in our 2025 base year and projected to expand to approximately USD 104,417.57 Million by 2032 — is expected to grow at a compound annual growth rate (CAGR) of 5.45% during the 2026–2032 forecast window. These headline figures set the stage for the tactical and strategic recommendations that follow; the full report contains the granular tables, segmentation matrices, and vendor scorecards that underpin these conclusions.
Worldwide Industrial Cleaning Services Market
Why this report matters for 2026 decision-makers
- Bridge the planning gap between near-term operational pressures (labor, regulatory compliance, supply volatility) and medium-term investment choices (automation, M&A, service redesign).
- Translate market growth and margin dynamics into concrete procurement and contracting strategies that protect uptime and drive cost-to-clean improvements.
- Support capital allocation debates with scenario-tested forecasts that reflect plausible combinations of wage inflation, chemical price shocks, and regulatory tightening.
- Provide vendor differentiation and playbooks for service providers looking to defend price or expand into adjacent value pools without diluting profitability.
What the PW Consulting report contains — practical, operational, and strategic
This study is built for executive action. Beyond headline market sizing and demand forecasts (2020–2025 historical series and 2026–2032 projections), the deliverables include:
Worldwide Industrial Cleaning Services Market
- Operational playbooks: standardized cleaning-spec templates, risk-based cleaning frequency matrices, and safety checklists that align with updated OSHA and REACH requirements.
- Commercial toolkits: RFP templates, outcome-based contracting models, and a Total Cost of Ownership (TCO) calculator that quantifies labor, chemicals, downtime, and capital equipment trade-offs.
- Vendor and capability assessment: a heat-mapped supplier diagnostic that evaluates scale, technical capabilities, sustainability credentials, and contract performance (note: the public summary outlines major providers; full scorecards and interview transcripts are in the subscription package).
- Scenario planning models: three stress-tested futures (baseline growth, accelerated regulation, and high-automation adoption) that produce revenue, margin and workforce implications for each scenario.
- Implementation roadmaps: 90‑, 180-, and 360‑day plans tailored to owners/operators, outsourcing buyers, and service providers aimed at rapid realization of efficiency gains.
Market dynamics shaping strategies in 2026
Five structural forces should dictate choices this year:
Worldwide Industrial Cleaning Services Market
- Labor supply and wage inflation: Skilled industrial cleaning personnel remain a constraint. US wages for industrial cleaners averaged USD 18.50 per hour in 2024, rising amid stronger manufacturing demand (US Bureau of Labor Statistics). Global skilled-worker shortages are material — our referenced industry studies project a shortage near 15% by 2026 — forcing upward wage pressure and intensified investment in retention and training (IFMA).
- Regulatory tightening: Tighter chemical and safety controls (for example, EU REACH mandates on cleaning agents and recent OSHA updates requiring powered industrial truck cleaning protocols) increase compliance complexity and procurement risk. Non-compliance can be costly; clients will pay a premium for certified, auditable service partners (European Chemicals Agency; OSHA).
- Input cost volatility: Prices for industrial cleaning chemistries rose in 2025 (surfactant supply disruptions added nearly a 6% input cost impact per industry reporting). This acts as a margin lever for service providers and a cost-leak for buyers that do not engage in forward procurement or alternative-chemistry substitution (American Chemistry Council).
- Technology and automation: Advances in dry ice blasting, robotics for hazardous-zone cleaning, and data-driven scheduling offer real options to reduce labor intensity and increase quality consistency. The economics of automation shift materially when labor inflation and compliance requirements intersect.
- Service bundling and integrated facilities solutions: Demand is moving toward integrated vendor suites that combine cleaning, maintenance, and compliance reporting — but buyers remain price-sensitive, producing an opportunity for both scale players and high-quality specialists.
Competitive landscape — what incumbent and challenger moves signal for 2026
The market remains fragmented (the three-largest players account for single-digit market shares, and the top five collectively remain well below a quarter of the market), creating both consolidation opportunities and room for specialized, high-margin niches. PW Consulting tracks strategic moves among leading service providers and interprets their playbooks:
- ABM Industries (New York, USA): With a recent multi-year contract win for manufacturing facilities (Oct 2025), ABM continues to expand through volume contracts in core industrial geographies. Their play emphasizes deployment scale and integrated facility services to defend pricing power (ABM press release).
- ISS Facility Services (Copenhagen, Denmark): The September 2025 partnership with a major European automotive OEM signals ISS’s focus on tailored protocols for high-regulation manufacturing environments, leveraging integrated safety and quality assurance processes (ISS news).
- Sodexo (Issy-les-Moulineaux, France): Sodexo’s June 2025 rollout of a sustainability-focused industrial cleaning program in Asia-Pacific highlights a strategic bet on green chemistry and lifecycle cost positioning in food-processing segments (Sodexo update).
- Aramark (Philadelphia, USA): Aramark’s ISO 14001 recertification for North American industrial operations (April 2025) is a defensive credential that supports premium contracts where environmental compliance is a procurement filter (Aramark sustainability report).
- Other notable players: Compass Group, Dussmann, Kuehne+Nagel, GDI, OCS Group, and Atalian compete across complementary niches (logistics, chemical plants, energy sites). Their strategies range from vertical specialization to bundled logistics-cleaning propositions.
Collectively, these moves indicate three convergent trends: (1) scale-led bids for large multi-site contracts, (2) specialized service offerings to meet strict regulatory needs, and (3) public sustainability credentials used as commercial differentiators. For buyers, supplier selection is no longer just price-driven; it requires an assessment of compliance, continuity, and technological readiness.
Strategic implications — what to prioritize in 2026
For executive teams making budget and sourcing decisions this year, PW Consulting recommends six prioritized actions:
- Quantify true cost-to-clean: Move beyond day-rate comparisons. Use TCO models to capture downtime, incident risk, chemical and PPE spend, and long-term remediation liability.
- Invest in skill pipelines and retention: Given projected labor shortages and wage pressure, invest in certified training academies, retention incentives, and apprenticeship partnerships to secure operational continuity.
- Pursue selective automation: Pilot robotics and dry ice technologies in high-frequency or hazardous applications to de-risk labor cost inflation and improve throughput.
- Lean into compliance as a commercial lever: Require supplier certifications and audit trails in procurement RFPs; prioritize partners with demonstrable REACH- and ISO-compliant processes.
- Design flexible contracting: Use hybrid pricing (base + performance/uptime bonuses) to align incentives, sharing both productivity gains and downside risks from sudden input-cost shocks.
- Use M&A and partnerships tactically: For service providers, M&A remains a rapid path to capability acquisition (sustainability chemistries, hazardous cleaning expertise, regional footprints). For buyers, strategic partnerships can secure capacity and innovation without full vendor integration.
How to use this report in the boardroom (practical agenda)
PW Consulting designed the deliverables to be actionable in three time horizons:
- 5-minute brief: Snapshot of market size, CAGR (5.45% for 2026–2032), and top-three risks for immediate procurement decisions.
- 30-minute executive workshop: Review scenario outputs, validate risk tolerances, and prioritize pilot projects (automation, supplier consolidation, or green-chemistry adoption).
- 90-day implementation sprint: Deploy an RFP using our templates, run two vendor proof-of-concept pilots, and finalize a dynamic contract that includes compliance SLAs and cost-sharing clauses.
Final note — the strategic value of full-access intelligence
Our public summary is designed to orient senior leaders to the strategic choices before them in 2026. The full PW Consulting report contains the proprietary segmentation matrices, regional and service-type breakdowns, detailed vendor scorecards, and downloadable financial models that provide the exact inputs necessary for capital allocation and vendor negotiation. Key proprietary outputs — including the segment-level revenue forecasts, price elasticity tables, and supplier performance benchmarks — are intentionally reserved for report subscribers to preserve the analytical rigor and sourcing integrity of our work.
To access the complete dataset, vendor scorecards, and implementation toolkits that underpin the 5.45% CAGR projection and the USD 2025–2032 forecast series, visit the PW Consulting report portal or contact our industry practice leads. In an environment where labor dynamics, regulatory pressure, and input volatility intersect, the difference between reactive procurement and proactive strategic design will determine which organizations capture the upside of market growth and which will be left managing avoidable risk.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Cleaning Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Towed Array Sonar Market to Reach USD 1,825.23 Million by 2032, Expanding at a 5.2% CAGR (2026–2032)
By pmarketresearch, 2026-07-15
Worldwide Towed Array Sonar System Market: Strategic Outlook for 2026 Decision Makers
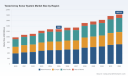
PW Consulting today releases an executive briefing drawn from our forthcoming Worldwide Towed Array Sonar System Market report, designed to equip defense planners, procurement leads, investors and industry strategists with the forward-looking commercial and operational context they need as 2026 spending cycles begin. The global market has evolved from roughly USD 980 Million in 2020 to about USD 1,280 Million in 2025, and our forecast anticipates continued expansion through 2032 — reaching approximately USD 1,825 Million by the end of the period, at a compound annual growth rate (CAGR) of 5.2% across 2026–2032.
Worldwide Towed Array Sonar System Market
Why this report matters for 2026 decisions
-
Timing and visibility: Ministries of Defence and prime contractors face conflicting priorities between near-term fleet upgrades and mid-term capability investments (platform integration, unmanned systems and variable-depth solutions). The report ties demand signals to procurement windows, helping teams align CapEx allocations and contract strategies with market momentum.
Worldwide Towed Array Sonar System Market -
Supply chain resilience: With transducer-grade piezoelectric ceramics (PZT) under pressure following raw material constraints — a documented price uptick tied to rare earth export dynamics — procurement teams must structure multi-year sourcing and strategic stockholding. The analysis quantifies exposure across component tiers and models cost sensitivity under different commodity and logistics scenarios.
Worldwide Towed Array Sonar System Market -
Technology and platform roadmaps: As navies accelerate integration of towed arrays into surface ships, submarines and increasingly unmanned platforms, the report maps the implication of active/passive architecture trends, processing and algorithmic investments, and integration complexity on lifecycle cost and upgrade pathways.
-
Export and partnership risk: Stringent export control regimes remain a core constraint. The report provides an operational playbook for managing ITAR and Wassenaar-related restrictions, and for structuring international partnerships that preserve access to key technologies while meeting sovereign requirements.
What the report contains (practical, actionable deliverables)
-
Market sizing and seven-year forecast (2026–2032) with scenario modeling addressing supply shocks, procurement acceleration and delayed fleet modernizations.
-
Commercial intelligence pack for buyers and suppliers: tender pipeline analysis, contracting models (unit buys vs. sustainment frameworks), and TCO-based procurement prioritization tools.
-
Supply chain heat maps and mitigation strategies, including component-by-component risk scoring (transducers, tow cables, signal processors, ship integrations) and recommended hedging actions.
-
Technology trajectory assessment, contrasting passive and active towed array investments, the role of low-frequency LFA systems, and the integration imperative with unmanned systems.
-
Regulatory impact assessment that operationalizes export control constraints into contracting, localization and IP-sharing strategies.
-
Operator-level upgrade playbooks for surface ship and submarine programs, including retrofit sequencing, test & evaluation milestones, and cost-risk trade-offs.
-
Competitor profiles and procurement intelligence, with an emphasis on capability differentials, platform fit, partnership footprints and recent program movements.
Competitive dynamics — what executives need to know
The towed array sonar market remains concentrated and technology-driven. Our analysis identifies a compact competitive set where a small number of primes command a material share of program awards and integration know-how. This concentration creates both opportunity and risk: established players bring reduced integration risk for large platform programs, while mid-tier specialized vendors are increasingly relevant for upgrades and niche exports.
-
L3Harris Technologies (Melbourne, FL, USA) — a preeminent integrator, noted for its AN/SQQ-89 suite integration and thin-line arrays used across US Navy surface and submarine programs. Recent contract awards for multi-function array upgrades underscore its position in sustainment and incremental modernization.
-
Thales Group (Paris, France) — a key supplier of variable-depth and towed array systems (CAPTAS family), active in allied frigate and destroyer programs and visible in recent deliveries to Western navies.
-
Lockheed Martin Corporation (Bethesda, MD, USA) — integrates strategic solutions (including long-range low-frequency systems and submarine-fit arrays) and continues to milestone integration on next-generation submarine blocks.
-
Atlas Elektronik (ThyssenKrupp Marine Systems, Bremen, Germany) — strong in low-frequency towed array design for submarine platforms, leveraging deep naval engineering heritage.
-
Leonardo S.p.A. (Rome, Italy) — offers export-friendly systems tailored to frigate programs and regional partnerships, pairing hardware with tailored support packages.
-
Ultra Maritime (Dartmouth, UK) — a specialist supplier focusing on retrofit and upgrade pathways for frigates and allied ASW platforms, with solutions attractive to navies pursuing incremental capability lifts.
Recent program developments further shape supplier positioning. Notable examples include a late-2025 US Navy contract for multi-function towed array upgrades, a mid-2025 delivery of a CAPTAS variant to a NATO ally, and a 2024 integration milestone for a submarine-block towed array — all illustrative of an active procurement landscape where sustainment and new-build programs overlap.
Market structure and risk factors
-
Concentration: A small cohort of primes captures the majority of award flows. Buyers should leverage this structure to negotiate long-term support and integration commitments, while challengers should pursue clear niche differentiation.
-
Raw material pressures: PZT-based transducer inputs have experienced meaningful cost pressure linked to rare earth supply constraints; program budgets need to account for upstream commodity volatility and potential lead-time expansion.
-
Export controls: ITAR and multilateral control regimes materially influence partnership choices and local content strategies — a key determinant of market access in export markets.
-
Geopolitical demand drivers: Indo-Pacific tensions and allied cooperation frameworks (notably accelerated tri-lateral initiatives) are expanding procurement pipelines and joint development projects, increasing both demand and interoperability requirements.
Practical strategic recommendations for 2026
-
Align procurement cycles with commodity hedging: Integrate PZT price and lead-time scenarios into contract clauses and milestone payments to avoid budget overruns.
-
Prioritize modularity in new contracts: Require modular open-architecture interfaces to preserve upgrade flexibility and lower long-term integration cost.
-
Structure export-compliant partnerships: Use joint-venture and licensed production models to navigate export controls while maintaining access to critical algorithms and components.
-
Accelerate unmanned integration pilots: Allocate small rapid-acquisition pots to validate sensor-to-UUV integrations and operational concepts ahead of large-scale buys.
-
Negotiate sustainment-bundled deals: Lock in long-term sustainment to reduce lifecycle cost and secure spare-part flows in a constrained supply environment.
-
Adopt phased capability baselines: Decompose capability requirements into essential near-term and aspirational mid-term blocks to retain budget flexibility.
How PW Consulting’s report supports execution
Our full report provides the calibrated evidence base behind the recommendations above: granular procurement timelines, supplier scorecards, a supplier concentration analysis, supply chain stress tests, and executable contract language templates designed for 2026 procurement cycles. To honor the “trailer” principle and preserve the commercial utility of the research, we present the in-depth segmentation datasets, vendor score matrices and full financial models exclusively in the complete report package.
Next steps and how to access the full analysis
For decision-makers preparing budgets, drafting RFPs or assessing supplier partnerships in 2026, the PW Consulting Worldwide Towed Array Sonar System Market report is intended as both a planning tool and an operational playbook. The full report includes downloadable models, a procurement-ready executive summary, and a confidential annex of supplier performance metrics.
Visit PW Consulting’s report page to request the full study, order workshop sessions for program teams, or commission bespoke analyses tailored to your acquisition or investor objectives.
For detailed analysis of this topic, please visit the official page: Worldwide Towed Array Sonar System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Dairy-Free Infant Formula Market Set to Hit USD 2.65 Billion in 2025, Expanding at a 6.85% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Dairy-Free Infant Formulas Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market study on the worldwide dairy-free infant formulas sector delivers a focused, actionable intelligence package intended to inform executive decision-making throughout 2026. Built on a 2020–2025 historical baseline (base year 2025) and a 2026–2032 forecast horizon, the report frames a sector that has moved from niche to mainstream: the market advanced materially during the first half of the decade and, with a modeled compound annual growth rate of 6.85% for 2026–2032, is projected to expand further toward multi‑billion dollar scale by the end of the forecast window. This briefing synthesizes the strategic implications of those dynamics — showing the depth of our analysis while reserving proprietary, granular splits for the full report.
Worldwide Dairy-Free Infant Formulas Market
Why 2026 is a Strategic Inflection Point
Multiple forces converge in 2026 to make it a pivotal year for incumbents and challengers alike. Consumer demand for dairy-free, plant-based infant nutrition continues to rise on the back of allergy awareness, lactose intolerance diagnoses, and shifting dietary preferences among younger parents seeking “clean-label” and sustainable options. At the same time, regulatory activity and food-safety events have elevated the bar for ingredient validation, traceability, and quality assurance. These twin trends create both opportunity and regulatory/compliance risk — and they require deliberate, fast-moving strategic responses.
Worldwide Dairy-Free Infant Formulas Market
Market Dynamics and Structural Drivers
-
Robust expansion trajectory: After steady growth through 2020–2025, the sector’s modeled growth path envisions continued acceleration into the early 2030s driven by product innovation, improved regulatory clarity for plant-based formulations, and stronger retail and online distribution support.
Worldwide Dairy-Free Infant Formulas Market -
Demand-side segmentation: Differentiation is crystallizing along clinical needs (e.g., infants with milk-protein sensitivity), lifestyle positioning (organic/clean-label), and ingredient provenance (soy vs non-soy plant proteins). These consumer signals demand distinct R&D, claims frameworks, and go‑to‑market plays.
-
Supply-side realities: Soy-based protein remains the predominant technical solution in the dairy-free category due to established nutritional profiles and manufacturing familiarity. However, disruptive entrants pursuing non-soy whole‑food matrices are forcing incumbents to evaluate new protein platforms and reformulation strategies.
-
Concentration and competitive intensity: Market concentration is meaningful among top players, creating high entry barriers in conventional channels while leaving pockets of white space in premium, organic, and direct‑to‑consumer segments.
Competitive Landscape — Strategic Profiles and Imperatives
The competitive set spans global incumbents with deep manufacturing and regulatory heft, regional brand families, and insurgent specialists focused on novel plant proteins and organic credentials. Key dynamics include:
-
Incumbent defense: Large multinationals leverage scale to secure shelf space, meet regulatory obligations, and sustain clinical-level R&D. Their playbook centers on incremental innovation (plant-blends, targeted hypoallergenic SKUs) and portfolio tiering to cover mass-market and specialty needs.
-
Specialist disruption: Startups and challenger brands are introducing non-soy, whole‑food protein platforms and premium organic propositions that appeal to a subset of health‑conscious parents. These players drive category redefinition and can be attractive M&A or partnership targets for incumbents seeking rapid capability acquisition.
-
Private-label and channel plays: Store-brand manufacturers and contract producers are using price and availability to capture value — a dynamic that pressures national brands but also expands overall category penetration.
Strategically, market leaders should balance defensive investments to protect core share with selective bets on high-growth niches. Smaller and mid‑sized players must choose between doubling down on distinctiveness (ingredient story, organic certification, D2C experience) or vertically integrating via toll-manufacturing, co‑pack arrangements, or licensing deals to scale.
Regulatory and Safety Context — Risks and Windows of Opportunity
-
Heightened regulatory activity: Recent and ongoing FDA actions — including updated labeling compliance periods, guidance on plant-based claims, and programmatic initiatives to modernize infant formula nutrient standards — increase both compliance complexity and the value of early regulatory engagement.
-
Pathways for innovation: Initiatives that clarify protein-quality assessment (e.g., renewed attention to protein efficiency ratio guidance and nutrient validation pathways) are creating routings for non‑soy, plant‑based formulas to achieve regulatory acceptance if backed by appropriate science packages.
-
Safety events as a market accelerant for trust: High-profile recalls tied to supplier contamination have shortened the timeline for many manufacturers to invest in supplier monitoring, in-house QC, and transparent traceability — expenditures that will increasingly separate trusted brands from lower-cost alternatives.
Recent Industry Signals to Track
-
Regulatory advancement for non-soy protein validation — a government-level acknowledgement that opens a commercialization runway for whole-food plant-based infant formulas if accompanying studies meet the new expectations.
-
Supply‑chain shocks and recalls tied to ingredient contamination — reinforcing the strategic imperative of multi-sourcing and upstream risk mitigation.
-
New product launches from mainstream and adjacent players — indicating broader retailer appetite and category expansion, not necessarily limited to dairy-free SKUs.
Strategic Imperatives & Tactical Playbook for 2026
Executives who treat 2026 as a year for decisive capability building will materially improve their optionality for 2027–2030. Our report emphasizes immediate actions across six pillars:
-
Regulatory-first R&D: Invest in protein-quality studies and dossier development now. The regulatory environment favors entrants that can present robust, standardized evidence packages aligned with the latest guidance.
-
Quality and traceability investments: Strengthen supplier controls, implement batch-level traceability, and adopt independent third‑party testing to rebuild and sustain consumer trust after safety incidents in the category.
-
Channel and pricing choreography: Align assortment strategies between mass retail, specialty pharmacies, and D2C channels to manage margin tension while targeting consumer cohorts that will pay premiums for organic or non-soy credentials.
-
Portfolio architecture: Decide which SKUs are defensive (protect core share) versus offensive (entering new niche segments). Maintain a clear innovation funnel that balances reformulation, line extensions, and platform bets.
-
M&A and partnership discipline: Prioritize partnerships that deliver capability (ingredient technology, infant-nutrition clinical evidence, D2C marketing) rather than solely scale. We identify target archetypes in the full report.
-
Stakeholder and policy engagement: Proactively engage with regulators, advocacy groups, and pediatric nutritionists to help shape practical labeling and nutrient assessment standards — and to accelerate favorable pathways for novel plant-based products.
Top Tactical Recommendations (Executive Checklist for 2026)
- Commission a protein‑quality validation roadmap (6–12 month timeline) tied to regulatory submission milestones.
- Institute dual sourcing for key oils and protein concentrates and contract minimums with certified suppliers.
- Define a three‑tier portfolio for mass, premium organic, and clinical‑grade dairy‑free SKUs with distinct margin and GTM plans.
- Allocate capex to in‑line microbiological and contaminant monitoring, and publish periodic supplier audits to strengthen brand trust.
- Identify two strategic M&A or co‑development targets (ingredient tech + D2C brand) and initiate exclusivity conversations.
- Prepare transparent consumer communications on labeling and nutrient equivalency to pre-empt regulatory scrutiny and build trust.
- Run scenario financial models (base / constrained supply / accelerated adoption) to stress-test pricing, working capital, and margin outcomes for 2026–2028.
What PW Consulting’s Full Report Delivers
The published report goes beyond this executive briefing to provide the tactical tools procurement, regulatory, commercial, and corporate development teams need to act in 2026. Included are:
- Detailed, auditable financial models and scenario forecasts across the 2026–2032 horizon (regional and channelized breakdowns).
- Segment-specific go‑to‑market playbooks showing prioritized retail and e‑commerce strategies and estimated payback timelines.
- A regulatory roadmap and dossier checklist for non‑soy and plant‑based protein submissions aligned to the latest agency guidances.
- An actionable supplier-risk matrix, quality assurance templates, and traceability implementation plans.
- Profiles and deal rationales for acquisition and partnership targets, with commercial synergies and integration risk analyses.
- Operational KPIs and a 12–24 month implementation timeline tailored to three company archetypes: incumbent, challenger, and private‑label manufacturer.
To preserve the report’s commercial value and to respect proprietary modeling, this briefing intentionally omits granular regional and channel-level figures. Executives seeking the full revenue and unit forecasts, split scenarios, and company-by-company financial benchmarking can access the complete dataset and downloadable tools via our publication page.
Closing — How to Use This Briefing in Your 2026 Planning Cycle
Use this briefing to inform your 2026 operating plan: allocate budget to regulatory science and quality assurance, prioritize a narrow set of product bets with defined success metrics, and adopt partnership-first approaches where internal capabilities are lacking. The combination of rising consumer interest, clearer regulatory signposts, and intensifying competitive moves makes 2026 a year to shift from reactive compliance to proactive leadership.
PW Consulting stands ready to support executive teams with tailored scenario modeling, regulatory dossier preparation, and M&A execution. For the comprehensive dataset, proprietary segmentation, and full implementation playbook, please consult the Worldwide Dairy‑Free Infant Formulas Market report page or contact our industry team.
For detailed analysis of this topic, please visit the official page: Worldwide Dairy-Free Infant Formulas Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Utility-Scale String Inverter Market to Rise from USD 7.5B in 2025 to USD 13.5B by 2032 at 8.74% CAGR — Asia Pacific Leading the Charge
By pmarketresearch, 2026-07-15
Worldwide Utility‑Scale String Inverter Market — Strategic Briefing for 2026 Decision‑Makers
PW Consulting is pleased to release an executive briefing derived from our forthcoming Worldwide Utility Scale String Inverter Market research. Anchored on a comprehensive base year of 2025 (with historical analysis spanning 2020–2025 and forecasts through 2032), this briefing distills the strategic imperatives that will shape capital allocation, product roadmaps, and go‑to‑market choices across the sector in 2026.
Worldwide Utility Scale String Inverter Market
Why this market matters to executive teams in 2026
The utility‑scale string inverter market is entering a maturation phase characterised by sizeable deployed base technology evolution, increasing software and services monetisation, and continuing cost pressure across supply chains. PW Consulting’s modelling shows the global market expanding from approximately USD 7.5 billion in 2025 to roughly USD 13.5 billion by 2032 — an implied compound annual growth rate of 8.74% over the 2026–2032 forecast horizon. This trajectory masks important inflection points: product differentiation around grid‑forming functionality, rapid adoption of modular high‑power blocks, and intensified competition among OEMs pursuing scale and service revenues.
Worldwide Utility Scale String Inverter Market
Key market dynamics shaping 2026 choices
-
Policy and tax timing: Recent US tax code changes and the One Big Beautiful Bill Act (OBBBA) introduced in mid‑2025 recalibrate incentives for clean electricity and investment tax credits. The specified start and placed‑in‑service thresholds create a hard timetable for project finance decisions; developers and OEMs must now synchronise delivery, commissioning, and warranty structures to capture or adapt to shifting tax eligibility windows.
Worldwide Utility Scale String Inverter Market -
Supply‑chain pressure and component costs: Raw material cost volatility — exemplified by polysilicon price movements in 2025 — has transmitted into inverter BOM and pricing considerations. Procurement teams should assume continued price elasticity in key inputs and embed flexible sourcing and hedging strategies into 2026 contracts.
-
Labour and balance‑of‑system costs: In mature markets, recent labour cost inflation for utility‑scale deployments has driven higher installed system economics. This changes the value proposition for inverters that reduce on‑site commissioning complexity, enable faster commissioning cycles, and minimise O&M touchpoints.
-
Technology convergence: The combination of modular high‑power blocks, AI‑enabled fault detection, and grid‑forming capabilities is shifting architectural preferences for large PV fleets. Independent analysis notes that string architectures now constitute a majority share of on‑grid utility‑scale inverter deployments, driven by modularity and lifecycle cost advantages.
-
Consolidation and concentration: Market concentration is material. The top three firms capture a majority share of market revenues and the top five are responsible for over two‑thirds of market value, accelerating competitive pressure around scale, service offerings, and financing relationships.
What the report delivers — practical, transaction‑ready intelligence
PW Consulting’s full report is designed as an operational playbook for 2026. Key deliverables include:
-
Validated market sizing and a transparent forecasting model covering 2020–2032, with scenario runs that stress policy shifts, raw material shocks, and accelerated decentralised grid services.
-
Commercial scorecards for leading OEMs that quantify product capability gaps, manufacturing footprint risk, and aftermarket service potential — enabling targeted partnership and M&A screening.
-
Procurement playbooks that translate component price trajectories into contract clauses, options for long‑lead items, and suggested inventory buffers to preserve project IRR under multiple scenarios.
-
Technology roadmaps and system integration guidance for developers and EPCs to specify inverters that reduce commissioning time, lower warranty exposure, and unlock ancillary revenue (e.g., frequency regulation, reactive power).
-
Investment and product strategy checklists: frameworks to prioritise R&D spend between hardware, embedded software, and cloud services; decision matrices for pursuing high‑power (>250 kW) vs. mid‑power (100–250 kW) segments; and suggested KPIs for service business success.
Competitive landscape — what matters to strategic planners
The utility string inverter competitive set blends global scale incumbents, nimble modular innovators, and vertically integrated energy OEMs. Several firm‑level patterns stand out for 2026 planning:
-
Scale and modularity leaders: Companies that have combined high shipment volumes with modular, block‑based architectures (including highly publicised product lines from large China‑headquartered OEMs) are positioned to offer rapid deployment options for large plant builds, reducing scheduling risk for developers.
-
Technology differentiation via software and AI: Vendors that embed AI‑driven diagnostics and arc‑fault detection into their string platforms deliver measurable reductions in O&M spend and uptime risk. This creates opportunities for SaaS monetisation tied to performance guarantees.
-
European and US specialists focusing on grid rules and governance: Manufacturers with deep experience in complex grid markets are emphasising features such as grid‑forming capability, high‑voltage topologies, and compliance engineering — an important consideration for projects in jurisdictions tightening interconnection requirements.
-
New entrants and incumbents expanding into utility scale: Several microinverter and commercial‑scale vendors are scaling up into utility applications via high‑voltage string platforms, spurred by demand for distributed, modular solutions that simplify maintenance.
Representative recent moves underline the pace of competitive evolution: major manufacturers have announced product launches featuring modular 800 kW+ scalable blocks, AI fault detection, and grid‑forming operation; at least one European manufacturer expanded domestic production in 2026 to meet demand for high‑capacity central and string solutions. These developments will compress product cycles and place a premium on rapid NPI (new product introduction) execution and manufacturing agility.
Strategic recommendations for 2026 — five priority moves
-
Embed policy timing into contract triggers. For projects with tax or incentive cliffs, make supplier performance linked to defined commissioning milestones, and include contingency options for scope reallocation if incentive qualification windows shift.
-
Hedge component exposure and diversify BOM sources. Execute multi‑tier sourcing and consider limited forward purchase commitments for critical inputs, while negotiating price pass‑through protections tied to transparent third‑party indices.
-
Accelerate software and service monetisation. Transition from a hardware‑only model to combined product‑software offerings that capture O&M and performance‑based revenue; use AI diagnostics as a differentiator in warranty economics.
-
Pursue targeted capacity and footprint decisions. For OEMs, consider geographically balanced capacity expansions that align with market access and tariff/tax advantages; for developers and EPCs, prioritise equipment partners with local support ecosystems to reduce labour‑intensive commissioning risk.
-
Use M&A and JV activity to close capability gaps quickly. Where organic development of grid‑forming controls or high‑voltage modularity is slow or expensive, target acquisitions or strategic alliances to secure validated IP and established field performance.
Why PW Consulting’s analysis is unique
Our research couples bottom‑up shipment and project pipeline validation with dynamic scenario modelling that explicitly accounts for regulatory cliffs, raw material price swings, and labour cost trajectories. We quantify concentration metrics and overlay supplier capability maps to help clients answer high‑stakes questions in 2026: which suppliers to endorse in EPC contracts, where to site production expansion, how to price long‑term service agreements, and which product features to prioritise in R&D spend.
Because of the commercial sensitivity of customer and region/application splits, our public briefing intentionally omits detailed segment tables and granular regional breakouts. This “trailer” approach preserves the strategic surprise for subscribers while providing enough high‑confidence insight to inform executive conversations. The full report includes exhaustive segmentations, downloadable model files, supplier scorecards, and a 12‑month decision calendar tailored for buyers, OEMs, and investors.
Next steps for executives
-
Download the full report for the complete dataset, including detailed segmentation tables, supplier scorecards, and a downloadable forecast model.
-
Book a strategic briefing with PW Consulting to translate the modelling into a customised action plan — we offer scenario workshops that map product, procurement, and M&A options against client‑specific project pipelines.
Contact PW Consulting to reserve your copy of the Worldwide Utility Scale String Inverter Market report and to schedule a 2026 strategic planning session. Let us help you convert market clarity into competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Utility Scale String Inverter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide High Voltage System Market to Jump from USD 74,550 Million (2025) to USD 247,030 Million by 2032 at 18.64% CAGR
By pmarketresearch, 2026-07-15
Worldwide High Voltage System Market: Strategic Imperatives for 2026 — PW Consulting Preview
As energy transition projects accelerate and grid architectures evolve, the worldwide high voltage (HV) systems market is entering a decisive phase for industry leaders and their strategic plans. PW Consulting’s newest market study — grounded in five years of historical data (2020–2025) and a seven‑year forecast horizon (2026–2032) — shows the global market expanding rapidly: from roughly USD 22.5 billion in 2020 to USD 74.6 billion in 2025, and continuing at a compound annual growth rate (CAGR) of approximately 18.6% into the forecast period. By 2032 the market is projected to surpass USD 247 billion. For corporate leaders planning 2026 capital allocation, procurement strategies, and M&A roadmaps, these macro trajectories are only the starting point.
Worldwide High Voltage System Market
Why 2026 Is a Strategic Inflection Point
Several converging dynamics make 2026 a pivotal year to translate strategy into action:
Worldwide High Voltage System Market
- Project acceleration and policy openings: Significant HVDC and high‑voltage transmission projects have come online or moved into advanced execution, reshaping regional demand patterns and procurement timetables.
- Supply‑side realignment: Large manufacturing investments by tier‑one suppliers and multi‑billion‑dollar cable and converter contracts are shifting competitive footprints, while raw material pressures and extended lead times are forcing new sourcing and inventory approaches.
- Technology bifurcation: The market is maturing around distinct architectural choices — from established medium‑voltage systems to higher‑voltage (including ultra‑high and 800V‑class) HVDC deployments that prioritize efficiency for long‑distance renewable transport.
- Capital scrutiny: Investors, utilities and developers are demanding more rigorous project risk analysis and staged investment triggers before sanctioning large transmission programs.
What PW Consulting’s Report Delivers — Practical, Actionable Modules
Our report is purposely designed for decision-makers who must convert market insight into executable plans in 2026. Key practical elements include:
Worldwide High Voltage System Market
- Executive strategy playbook: Scenario‑based recommendations for OEMs, EPCs, utilities and private capital on bidding posture, JV structures and capability investments under different policy and commodity scenarios.
- Supply chain stress test: Proprietary modeling of lead‑time exposures (including transformer and cable bottlenecks), price sensitivity to steel and copper inflation, and mitigation tactics such as near‑shoring, hedge procurement, and factory footprint optimization.
- Capital allocation model: A dynamic capex calculator that translates project timelines and regulatory milestones into cash‑flow stress points, enabling finance teams to sequence investments and prioritize projects with the highest risk‑adjusted returns.
- Technology adoption timeline: Comparative analysis of converter technologies (VSC, LCC, MMC and hybrid topologies), including where each delivers the best value for offshore wind collectors, long‑distance interconnects or multi‑terminal grids.
- Supplier scorecard and M&A radar: Valuation‑aware shortlists and capability maps for tuck‑ins and strategic acquisitions that accelerate entry into cable systems, converter factories or digital substation solutions.
- Project pipeline mapping: A curated, near‑term project inventory tied to procurement windows, enabling OEMs and suppliers to align commercial capacity with revenue windows and avoid stranded backlog.
Competitive Landscape: What Top Players Are Signaling
The market exhibits moderate concentration: a handful of global incumbents continue to command meaningful shares, but competition is intensifying as cable specialists, regional OEMs and system integrators scale up. PW Consulting’s qualitative analysis of principal players highlights strategic positioning and near‑term moves:
- Hitachi Energy (Zurich) — A global leader in HVDC and transmission solutions with strong project execution capabilities. Recent investments in U.S. manufacturing capacity signal a dual strategy: secure domestic supply for data centers and grid projects, and reduce lead‑time exposure for large transformers.
- Siemens Energy (Munich) — Focused on modular multilevel converter platforms and integrated grid solutions, with advantages in offshore wind integration and complex multiterminal projects.
- GE Vernova (Cambridge, MA) — Leveraging a broad installed base and turnkey HVDC expertise; recent consortium wins on high‑capacity offshore links demonstrate continued competitiveness at scale.
- Mitsubishi Electric & Toshiba — Both maintain depth in converter stations and power electronics, and remain go‑to partners for reliability‑critical bulk power projects.
- Schneider Electric & Eaton — Strengths lie in high‑voltage switchgear, substation automation and digitalization tools that are increasingly required alongside traditional HV hardware.
- Prysmian Group, Nexans, Sumitomo, NKT — Cable specialists that are capitalizing on rising subsea and onshore interconnector demand; recent contracting activity underscores the premium placed on manufacturing scale and delivery certainty.
- Chinese suppliers (TBEA, NR Electric) — Building global footprints through competitive pricing and turnkey delivery, particularly for large domestic and regional transmission projects across Asia and Africa.
- Hyundai Electric, BHEL — Regional powerhouses with strength in switchgear and transformers, increasingly competitive in cross‑border transmission tenders.
In short: incumbency still matters, but execution speed, supply certainty and system integration capability increasingly define winners.
Recent Events That Must Shape 2026 Strategy
Selected market developments in late 2024–early 2026 have immediate strategic implications:
- Large contract awards for multi‑GW offshore and long‑distance HVDC connections are accelerating demand for specialized converters and high‑voltage cables — improving revenue visibility for participants with ready manufacturing capacity.
- Major manufacturing investments by established OEMs indicate a shift toward onshore capacity expansion to shorten supply chains and serve fast‑moving national programs.
- Government and regulator initiatives — such as DOE‑backed programs for lower‑cost converters and the commercial start of significant cross‑border DC corridors — are lowering technical and regulatory barriers for new HVDC deployments.
- Raw material and equipment constraints: Transformer lead times and price inflation (industry data indicate substantial price escalation for large units since 2019) remain acute risks that materially affect project economics and delivery schedules.
Implications for Procurement, Project Developers and Investors
For procurement leaders and project sponsors, the PW report translates macro momentum into specific 2026 actions:
- Time‑shift procurement decisions: Secure critical long‑lead items earlier in the year and consider contract structures that share commodity and logistics risk with suppliers.
- Balance CAPEX and schedule risk: Use staged contracting and modular delivery to limit exposure to unexpected price spikes or supply delays.
- Pursue strategic partnerships: Joint ventures with cable manufacturers or converter specialists can be the fastest route to de‑risk delivery on large offshore or long‑distance projects.
- Rethink geographic exposure: Manufacturing investments and legislative changes are re‑shaping where projects are most executable — adjust market entry and footprint plans accordingly.
- Embed digital and O&M into bids: Substation automation and predictive diagnostics are no longer optional — they materially reduce lifecycle costs and are decisive in competitive tenders.
Report Limitations and Where to Find the Full Intelligence
This preview highlights the strategic contours and decision points we expect to matter in 2026. To preserve the integrity of PW Consulting’s proprietary forecasting and to ensure clients receive the full operational utility of our work, this article intentionally omits detailed regional and component splits, unit‑level forecasts and sensitive scenario matrices. The full study contains granular regional breakdowns, component and voltage‑level forecasts, supplier market shares, project‑by‑project commissioning timetables, and executable playbooks tailored to OEMs, utilities, and investors.
PW Consulting’s Worldwide High Voltage System Market report also includes downloadable tools and models that executives can adapt to their internal financial frameworks: a procurement readiness checklist, a supplier evaluation template, a capital allocation stress‑testing workbook, and an investor‑oriented pipeline valuation model.
Next Steps for Leaders Planning 2026
- Prioritize supplier engagements now — lead times and site readiness windows are compressing.
- Run the report’s scenario model against your project portfolio to identify vulnerable items and re‑sequence spend where necessary.
- Consider near‑term strategic investments (manufacturing, JV, or targeted M&A) to lock in capacity and reduce exposure to raw material and logistics volatility.
- Engage with regulators and transmission system operators early — permitting and right‑of‑way availability will remain gating factors despite strong policy support.
PW Consulting’s comprehensive market study is designed to be the practical backbone of those decisions. For access to the full dataset, supplier rankings, and the downloadable strategic toolkits, visit PW Consulting’s report page and request the Worldwide High Voltage System Market full study and executive briefing.
For detailed analysis of this topic, please visit the official page: Worldwide High Voltage System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Super Depth of Field 3D Microscope Market Poised to Grow at an 8.3% CAGR, Signaling Strong Global Demand
By pmarketresearch, 2026-07-15
Worldwide Super Depth of Field 3D Microscope Market — Strategic Briefing for 2026 Decision Makers
Executive snapshot
The super depth-of-field 3D microscope market has entered a new phase of commercial maturity. Our comprehensive market model pegs the sector at approximately USD 1,214 Million in the base year (2025) and projects steady expansion through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 8.3%. By the end of the forecast horizon the modeled global market size is expected to exceed USD 2,120 Million. For corporate leaders planning 2026 budgets and three‑year strategic programs, this trajectory signals a sustained opportunity to capture value across hardware, software, services and integration layers.
Worldwide Super Depth of Field 3D Microscope Market
Why this briefing matters for 2026 strategy
Companies that move early to align product roadmaps, channel strategies and M&A activity with the structural drivers of the super depth-of-field 3D microscope market will enjoy asymmetric returns. Key strategic inflection points for 2026 decisions include: capitalizing on healthcare digitization and heads‑up surgical platforms, embedding advanced 3D metrology into high‑mix manufacturing, and commercializing compact, portable imaging for in‑line inspection. This briefing synthesizes the tactical implications of these trends without disclosing the full proprietary segmentation used to value specific slices of demand — that depth of granularity is preserved for clients who access the full report.
Worldwide Super Depth of Field 3D Microscope Market
Core dynamics shaping vendor and buyer behavior
- Adoption is technology-led and ecosystem-dependent: Recent product introductions and platform upgrades show that depth‑of‑field gains are now delivered through hybrid optical-electronic approaches (e.g., focus stacking, multi-path optics, real-time 3D reconstruction). Vendors that offer open APIs, software toolchains and integration services are winning specification battles at system integrators and hospitals.
- Healthcare and industrial pull are complementary: Clinical demand for immersive, high‑resolution visualization is accelerating alongside industrial requirements for rapid, traceable 3D metrology. Buyers in both segments prize ergonomics, workflow integration and regulatory maturity; these factors often outweigh raw optical performance in procurement decisions.
- Consolidation and tiering are advancing: Market concentration is pronounced — the top three vendors account for a material majority of market value and the top five for an even larger share — creating an environment where scale, channel reach and installed‑base services drive enterprise-level deals.
- Regional rollout is nuanced: Growth is broadly global, but local go‑to‑market and service models determine penetration speed. Detailed regional and application breakdowns are available in the full dataset for executive due diligence.
Practical content of the PW Consulting report (what your team will receive)
The full Worldwide Super Depth of Field 3D Microscope Market report is structured to support immediate decision-making and to be operationalized by commercial teams:
Worldwide Super Depth of Field 3D Microscope Market
- Proprietary demand model: Year-by-year market sizing from 2020 to 2032, with scenario variants that stress test adoption assumptions across clinical, industrial and research end markets.
- Commercial playbooks: Go‑to‑market approaches tailored to OEMs, distributors and systems integrators, including channel economics, licensing alternatives and recommended sales compensation models.
- Pricing and offer architecture: Value-based pricing frameworks, bundling strategies (hardware + software + services), and margin sensitivity analyses that inform product roadmap prioritization.
- Buyer personas and procurement triggers: Detailed profiles for hospital procurement, factory automation teams and academic research purchasers — covering decision criteria, procurement cycles and budget triggers.
- Supply‑chain and manufacturing roadmap: Component sourcing risk maps, lead-time scenarios, and recommendations for contract manufacturing vs. in‑house assembly to protect margin and ensure serviceability.
- Regulatory and reimbursement intelligence: Assessment of CE/FDA clearance pathways, clinical evidence requirements for surgical visualization systems, and how regulatory status impacts commercial rollout timing.
- M&A and partnership playbook: Identification of strategic acquisition targets, valuation ranges (relative to revenue and installed base), and integration checklists to accelerate time-to-market for combined offerings.
Competitive landscape — what to watch in 2026
The market exhibits a layered competitive structure with global platform players, regional specialists, and compact innovators. Senior product and corporate development teams should monitor the following vendors and tactics:
- Keyence Corporation (Osaka, Japan): Known for the VHX series, Keyence combines focus stacking with real‑time 3D measurement — a strong proposition for factory inspection and quality control applications where cycle time and automation are critical.
- ZEISS Group (Oberkochen, Germany): ZEISS’ surgical and ophthalmic systems continue to accelerate digital visualization adoption; recent showcases emphasize expanded depth-of-field modes and regulatory readiness for clinical deployment.
- Leica Microsystems (Wetzlar, Germany): With FusionOptics and next‑generation surgical microscopes, Leica’s approach blends optical innovation and clinical ergonomics to win complex procedure specifications.
- Hirox (Japan/Europe): Positioned for high-resolution 3D imaging and stitching workflows, Hirox products are competitive in detailed surface analysis applications.
- China-based specialists (BestScope, OUMIT, ES‑ray, Teelen, Peentech, MNT): These suppliers are advancing cost‑performance tradeoffs and targeted feature sets — such as high magnification, telecentric optics and motorized stages — to penetrate volume-sensitive industrial segments.
Recent product activity supports these competitive patterns: Leica introduced a next‑generation Proveo 8x platform focused on real‑time 3D imaging and improved depth control, and ZEISS highlighted an ARTEVO 850 configuration that materially increased depth of field while emphasizing true‑color heads‑up workflows. These moves underscore how optical innovation paired with digital ergonomics is reshaping procurement criteria.
Technology and regulatory signals to factor into 2026 planning
- Hybrid optical strategies are mainstream: Techniques that combine multiple optical paths, focus stacking and computational depth reconstruction now enable substantial depth enhancements without sacrificing resolution. This is a durable differentiator versus single‑path designs.
- Clinical digitization drives incremental services revenue: Hospitals buying advanced surgical visualization systems increasingly demand integrated recording, analytics and robotic compatibility. Suppliers capable of plugging into digital OR ecosystems capture higher lifetime value.
- Regulatory clearance is a market access gatekeeper: CE marked and FDA‑cleared 3D visualization systems materially reduce adoption friction in major markets; vendors without clear regulatory strategies face longer sales cycles and higher commercial costs.
Strategic playbook — recommended actions for 2026
Based on modeled scenarios and vendor capability mapping, we recommend the following prioritized activities for executive teams preparing 2026 allocations:
- Accelerate integration partnerships: Form alliances with software and robotic visualization providers to create bundled offerings for surgical and automated inspection workflows.
- Differentiate on services and data: Design subscription and outcome‑based service packages (e.g., calibration-as-a-service, analytics-enabled QA) to convert hardware sales into recurring revenue.
- Pursue targeted inorganic moves: Consider bolt‑on acquisitions that add key software IP, regulatory footholds or channel presence in priority regions rather than large horizontal purchases.
- Optimize product tiering: Align entry, mid and premium SKUs to distinct buyer personas (lab/research, high-throughput manufacturing, surgical) and standardize interfaces to reduce SKU complexity.
- Validate go‑to‑market pilots: Run 6–9 month pilots with strategic customers in both clinical and industrial sites to accelerate workflow validation and build case studies for 2027 scale‑ups.
What the full report unlocks
This release serves as a strategic teaser: it articulates the growth trajectory and the actionable implications for 2026 planning, while preserving the granular segmentation, pricing matrices and detailed region‑application matrices that finance, product and corporate development teams require to finalize budgets and deals. The full report contains downloadable models, vendor scorecards, RFx tender templates and prioritized M&A targets — all calibrated to support execution in the 2026 planning cycle.
Final perspective
For companies evaluating where to deploy R&D, capital expenditure and commercial energy in 2026, the super depth‑of‑field 3D microscope market offers a predictable expansion path with clear winners for those who combine optical excellence with software, services and regulatory maturity. PW Consulting’s full report translate s our proprietary modeling and field validation into executable programs — from pricing playbooks to acquisition checklists — enabling leaders to convert market growth into lasting competitive advantage.
To access the complete dataset, vendor scorecards and execution templates, consult the official report page and secure the full intelligence package designed for rapid operational deployment.
For detailed analysis of this topic, please visit the official page: Worldwide Super Depth of Field 3D Microscope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com