

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Rail Air Conditioning Market to Expand at a 6.55% CAGR During 2026–2032

Worldwide Rail Air Conditioning Market: 2026 Playbook — Strategic Imperatives from PW Consulting’s Latest Market Study
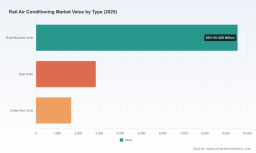
PW Consulting today releases a forward-looking briefing drawn from our comprehensive market study, Worldwide Rail Air Conditioning Market (base year 2025, forecast period 2026–2032). The global rail HVAC market has expanded from approximately USD 10.8 billion in 2020 to USD 14.05 billion in 2025, and is projected to reach roughly USD 21.9 billion by 2032, representing a 6.55% CAGR over the 2026–2032 forecast window. For rail operators, OEMs, tier‑1 suppliers and investors, 2026 represents a strategic inflection point where regulatory pressure, materials volatility and a rapid shift to energy‑efficient architectures converge to rewrite requirements for product design, sourcing and aftermarket service models.
Worldwide Rail Air Conditioning Market
Why 2026 is the decision year
-
Regulatory acceleration: European and global standards are tightening both performance and environmental thresholds. EN 14750 continues to set the bar for operational performance across extreme temperature ranges, while recent emission rules are pushing low‑GWP refrigerants and associated system redesigns into procurement checklists. These converging mandates mean equipment selected today must be validated across more severe operating envelopes and refrigerant lifecycles.
Worldwide Rail Air Conditioning Market -
Technology pivot to efficiency and electrification: System architectures are migrating toward inverter-driven compressors and brushless DC motor platforms that can cut in‑service energy use materially. Early adopters are already field‑validating these gains on high‑visibility projects, shifting evaluation criteria from initial CapEx to lifetime energy and integration cost.
Worldwide Rail Air Conditioning Market -
Supply‑chain and cost pressure: Raw material swings and labour tightness are forcing manufacturers to rework supply strategies and production footprints. The cumulative effect is higher unit production risk for suppliers that rely on commodity‑heavy designs or single‑source subassemblies.
-
Consolidation and concentrated supplier power: The market shows moderate concentration, with the top three suppliers accounting for just over 40% of value and the top five approaching 60%—a structure that magnifies the strategic importance of supplier selection, partnership models and aftermarket control.
What PW Consulting’s report delivers — practical intelligence for 2026
-
Market sizing and validated forecasts: A rigorous historical reconstruction (2020–2025) and scenario‑based projections across 2026–2032 to test upside and downside demand under policy, commodity and technology shocks.
-
Technology and product roadmaps: Comparative analyses of inverter systems, brushless DC compressors, refrigerant alternatives and modularization strategies — including lifecycle cost models that prioritize Opex sensitivity over headline CapEx.
-
Supply‑chain and cost diagnostics: Component‑level margin mapping, supplier concentration heatmaps and procurement risk matrices designed to support hedging, dual‑sourcing and near‑shoring decisions.
-
Competitive intelligence and go‑to‑market playbooks: Profiles of global incumbents and disruptive challengers, tender pipelines, and win‑loss case studies that reveal how leading suppliers are securing fleetwide contracts.
-
Aftermarket and service strategies: Opportunity sizing and commercial models for maintenance, parts, and remote diagnostics — a critical revenue pool often undervalued in RFP negotiations.
-
Decision tools: Interactive TCO calculators, certification roadmaps and project-level scenario models that translate technical choices into procurement outcomes.
Competitive landscape — who moves the market
The market remains anchored by several established global players and strong national champions. Leading firms combine system design expertise with global installation footprints, while a cohort of regional providers retains advantages on local content, service networks and price competitiveness. Recent corporate developments underscore where momentum is concentrating:
-
Knorr‑Bremse’s mid‑2025 launch of an energy‑saving HVAC platform exemplifies supplier strategies to win metro and urban transit tenders by reducing lifecycle energy consumption.
-
Alstom’s contract awards in 2025 highlight continued demand for integrated rolling‑stock HVAC packages tied to major fleet programmes.
-
Hitachi’s validation work on eco‑HVAC units for a major high‑speed project signals a rising focus on certifying next‑gen architectures for harsh operating regimes.
-
Wabtec’s supplier nominations in high‑growth markets illustrate how modular solutions are being positioned to scale rapidly in emerging fleet programmes.
-
Several Japanese OEMs and Chinese metro‑specialists continue to compete on lightweight, low‑power designs and cost competitiveness, respectively—intensifying price and spec competition across global tenders.
Supply‑chain realities and regulatory headwinds
-
Commodity exposure: Heat‑exchanger metals and electronic components remain the largest contributors to bill‑of‑materials volatility. Manufacturers that lock strategic alloy supplies and redesign for material efficiency can protect margins and delivery certainty.
-
Refrigerant transition: Regulatory moves toward very low‑GWP refrigerants necessitate system redesigns, compatibility tests and new service protocols. Product roadmaps must include refrigerant lifecycle management and training plans for depot maintenance crews.
-
Certification burden and time‑to‑market: Certification cycles for new HVAC platforms are lengthening as regulators tighten test regimes. Suppliers who invest early in modular validation and cross‑jurisdictional test campaigns gain measurable time‑to‑award advantages.
-
Labour and cost inflation: Skilled assembly and calibration remain bottlenecks in advanced markets. Manufacturers are responding with automation, standardization and targeted localization to contain build costs and lead times.
Strategic recommendations for 2026 — prioritized actions
-
Reframe procurement around TCO and integration risk, not just unit price. Include energy consumption under realistic duty cycles, refrigerant replacement scenarios, and servicing availability in all supplier scorecards.
-
Accelerate modular and scalable product strategies. Design approaches that separate core compressors, heat exchangers and control electronics reduce certification overhead and support faster customization for regional markets.
-
Lock strategic supplier partnerships for critical commodities and electronics. Hedging and framework agreements—coupled with co‑development clauses—reduce exposure to raw‑material spikes and ensure prioritized production slots.
-
Invest in retrofit and aftermarket service propositions. With fleets seeking to extend asset life while meeting new environmental rules, retrofit kits and remote monitoring packages offer higher margins and recurring revenue.
-
Prioritize certification lead indicators. Early engagement with certification bodies and targeted test campaigns shorten procurement cycles and create meaningful entry barriers for late movers.
-
Define a clear refrigerant transition roadmap. R&D programmes should model refrigerant availability, handling costs and end‑of‑life scenarios so product offerings remain compliant without disruptive redesigns.
-
Explore M&A and strategic JV opportunities focused on electronics, controls and aftermarket analytics—capabilities that are increasingly differentiating wins in competitive tenders.
How PW Consulting’s study supports executive action
Our report synthesizes quantitative market construction with qualitative, operational intelligence to produce executable recommendations. Through scenario stress‑testing, supplier heatmaps and a suite of financial tools, boardrooms can translate technical trends into procurement timelines, R&D budgets and partner selection criteria for 2026 and beyond. To maintain the market’s “trailer” principle: the public brief maps the strategic contours; the full report contains the granular segment matrices, regional buildouts, product‑type economics and supplier scorecards required to operationalize these recommendations.
Next steps
For executives preparing 2026 capital and procurement plans, the path forward is clear: act now to lock supplier relationships, prioritize energy‑efficient and low‑GWP designs, and monetize aftermarket services. PW Consulting’s Worldwide Rail Air Conditioning Market report offers the granular models and playbooks you need to convert these imperatives into measurable outcomes. Visit our report page or contact the PW Consulting advisory team to request the full dataset, interactive dashboards and a complementary strategy briefing tailored to your organisation’s role in the rail value chain.
For detailed analysis of this topic, please visit the official page: Worldwide Rail Air Conditioning Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com