

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 5.45% CAGR — Worldwide Industrial Cleaning Services Market to Reach USD 104,417.57 Million by 2032 (Base Year 2025)

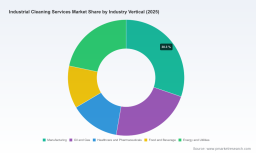
PW Consulting Launch: Strategic Preview — Worldwide Industrial Cleaning Services Market (2026 Readiness)
As industrial operators, service providers, and investors prepare to make material decisions in 2026, PW Consulting’s latest market study on Worldwide Industrial Cleaning Services delivers an evidence-based, decision-ready framework for competitive advantage. Built on an empirical baseline that covers 2020–2025 and forward-looking scenario modelling to 2032, the report identifies where capital and operational choices will create or erode value. The global market — estimated at USD 72,018.34 Million in our 2025 base year and projected to expand to approximately USD 104,417.57 Million by 2032 — is expected to grow at a compound annual growth rate (CAGR) of 5.45% during the 2026–2032 forecast window. These headline figures set the stage for the tactical and strategic recommendations that follow; the full report contains the granular tables, segmentation matrices, and vendor scorecards that underpin these conclusions.
Worldwide Industrial Cleaning Services Market
Why this report matters for 2026 decision-makers
- Bridge the planning gap between near-term operational pressures (labor, regulatory compliance, supply volatility) and medium-term investment choices (automation, M&A, service redesign).
- Translate market growth and margin dynamics into concrete procurement and contracting strategies that protect uptime and drive cost-to-clean improvements.
- Support capital allocation debates with scenario-tested forecasts that reflect plausible combinations of wage inflation, chemical price shocks, and regulatory tightening.
- Provide vendor differentiation and playbooks for service providers looking to defend price or expand into adjacent value pools without diluting profitability.
What the PW Consulting report contains — practical, operational, and strategic
This study is built for executive action. Beyond headline market sizing and demand forecasts (2020–2025 historical series and 2026–2032 projections), the deliverables include:
Worldwide Industrial Cleaning Services Market
- Operational playbooks: standardized cleaning-spec templates, risk-based cleaning frequency matrices, and safety checklists that align with updated OSHA and REACH requirements.
- Commercial toolkits: RFP templates, outcome-based contracting models, and a Total Cost of Ownership (TCO) calculator that quantifies labor, chemicals, downtime, and capital equipment trade-offs.
- Vendor and capability assessment: a heat-mapped supplier diagnostic that evaluates scale, technical capabilities, sustainability credentials, and contract performance (note: the public summary outlines major providers; full scorecards and interview transcripts are in the subscription package).
- Scenario planning models: three stress-tested futures (baseline growth, accelerated regulation, and high-automation adoption) that produce revenue, margin and workforce implications for each scenario.
- Implementation roadmaps: 90‑, 180-, and 360‑day plans tailored to owners/operators, outsourcing buyers, and service providers aimed at rapid realization of efficiency gains.
Market dynamics shaping strategies in 2026
Five structural forces should dictate choices this year:
Worldwide Industrial Cleaning Services Market
- Labor supply and wage inflation: Skilled industrial cleaning personnel remain a constraint. US wages for industrial cleaners averaged USD 18.50 per hour in 2024, rising amid stronger manufacturing demand (US Bureau of Labor Statistics). Global skilled-worker shortages are material — our referenced industry studies project a shortage near 15% by 2026 — forcing upward wage pressure and intensified investment in retention and training (IFMA).
- Regulatory tightening: Tighter chemical and safety controls (for example, EU REACH mandates on cleaning agents and recent OSHA updates requiring powered industrial truck cleaning protocols) increase compliance complexity and procurement risk. Non-compliance can be costly; clients will pay a premium for certified, auditable service partners (European Chemicals Agency; OSHA).
- Input cost volatility: Prices for industrial cleaning chemistries rose in 2025 (surfactant supply disruptions added nearly a 6% input cost impact per industry reporting). This acts as a margin lever for service providers and a cost-leak for buyers that do not engage in forward procurement or alternative-chemistry substitution (American Chemistry Council).
- Technology and automation: Advances in dry ice blasting, robotics for hazardous-zone cleaning, and data-driven scheduling offer real options to reduce labor intensity and increase quality consistency. The economics of automation shift materially when labor inflation and compliance requirements intersect.
- Service bundling and integrated facilities solutions: Demand is moving toward integrated vendor suites that combine cleaning, maintenance, and compliance reporting — but buyers remain price-sensitive, producing an opportunity for both scale players and high-quality specialists.
Competitive landscape — what incumbent and challenger moves signal for 2026
The market remains fragmented (the three-largest players account for single-digit market shares, and the top five collectively remain well below a quarter of the market), creating both consolidation opportunities and room for specialized, high-margin niches. PW Consulting tracks strategic moves among leading service providers and interprets their playbooks:
- ABM Industries (New York, USA): With a recent multi-year contract win for manufacturing facilities (Oct 2025), ABM continues to expand through volume contracts in core industrial geographies. Their play emphasizes deployment scale and integrated facility services to defend pricing power (ABM press release).
- ISS Facility Services (Copenhagen, Denmark): The September 2025 partnership with a major European automotive OEM signals ISS’s focus on tailored protocols for high-regulation manufacturing environments, leveraging integrated safety and quality assurance processes (ISS news).
- Sodexo (Issy-les-Moulineaux, France): Sodexo’s June 2025 rollout of a sustainability-focused industrial cleaning program in Asia-Pacific highlights a strategic bet on green chemistry and lifecycle cost positioning in food-processing segments (Sodexo update).
- Aramark (Philadelphia, USA): Aramark’s ISO 14001 recertification for North American industrial operations (April 2025) is a defensive credential that supports premium contracts where environmental compliance is a procurement filter (Aramark sustainability report).
- Other notable players: Compass Group, Dussmann, Kuehne+Nagel, GDI, OCS Group, and Atalian compete across complementary niches (logistics, chemical plants, energy sites). Their strategies range from vertical specialization to bundled logistics-cleaning propositions.
Collectively, these moves indicate three convergent trends: (1) scale-led bids for large multi-site contracts, (2) specialized service offerings to meet strict regulatory needs, and (3) public sustainability credentials used as commercial differentiators. For buyers, supplier selection is no longer just price-driven; it requires an assessment of compliance, continuity, and technological readiness.
Strategic implications — what to prioritize in 2026
For executive teams making budget and sourcing decisions this year, PW Consulting recommends six prioritized actions:
- Quantify true cost-to-clean: Move beyond day-rate comparisons. Use TCO models to capture downtime, incident risk, chemical and PPE spend, and long-term remediation liability.
- Invest in skill pipelines and retention: Given projected labor shortages and wage pressure, invest in certified training academies, retention incentives, and apprenticeship partnerships to secure operational continuity.
- Pursue selective automation: Pilot robotics and dry ice technologies in high-frequency or hazardous applications to de-risk labor cost inflation and improve throughput.
- Lean into compliance as a commercial lever: Require supplier certifications and audit trails in procurement RFPs; prioritize partners with demonstrable REACH- and ISO-compliant processes.
- Design flexible contracting: Use hybrid pricing (base + performance/uptime bonuses) to align incentives, sharing both productivity gains and downside risks from sudden input-cost shocks.
- Use M&A and partnerships tactically: For service providers, M&A remains a rapid path to capability acquisition (sustainability chemistries, hazardous cleaning expertise, regional footprints). For buyers, strategic partnerships can secure capacity and innovation without full vendor integration.
How to use this report in the boardroom (practical agenda)
PW Consulting designed the deliverables to be actionable in three time horizons:
- 5-minute brief: Snapshot of market size, CAGR (5.45% for 2026–2032), and top-three risks for immediate procurement decisions.
- 30-minute executive workshop: Review scenario outputs, validate risk tolerances, and prioritize pilot projects (automation, supplier consolidation, or green-chemistry adoption).
- 90-day implementation sprint: Deploy an RFP using our templates, run two vendor proof-of-concept pilots, and finalize a dynamic contract that includes compliance SLAs and cost-sharing clauses.
Final note — the strategic value of full-access intelligence
Our public summary is designed to orient senior leaders to the strategic choices before them in 2026. The full PW Consulting report contains the proprietary segmentation matrices, regional and service-type breakdowns, detailed vendor scorecards, and downloadable financial models that provide the exact inputs necessary for capital allocation and vendor negotiation. Key proprietary outputs — including the segment-level revenue forecasts, price elasticity tables, and supplier performance benchmarks — are intentionally reserved for report subscribers to preserve the analytical rigor and sourcing integrity of our work.
To access the complete dataset, vendor scorecards, and implementation toolkits that underpin the 5.45% CAGR projection and the USD 2025–2032 forecast series, visit the PW Consulting report portal or contact our industry practice leads. In an environment where labor dynamics, regulatory pressure, and input volatility intersect, the difference between reactive procurement and proactive strategic design will determine which organizations capture the upside of market growth and which will be left managing avoidable risk.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Cleaning Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com