

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Utility-Scale String Inverter Market to Rise from USD 7.5B in 2025 to USD 13.5B by 2032 at 8.74% CAGR — Asia Pacific Leading the Charge

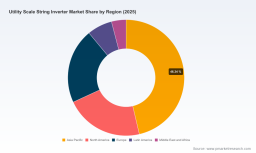
Worldwide Utility‑Scale String Inverter Market — Strategic Briefing for 2026 Decision‑Makers
PW Consulting is pleased to release an executive briefing derived from our forthcoming Worldwide Utility Scale String Inverter Market research. Anchored on a comprehensive base year of 2025 (with historical analysis spanning 2020–2025 and forecasts through 2032), this briefing distills the strategic imperatives that will shape capital allocation, product roadmaps, and go‑to‑market choices across the sector in 2026.
Worldwide Utility Scale String Inverter Market
Why this market matters to executive teams in 2026
The utility‑scale string inverter market is entering a maturation phase characterised by sizeable deployed base technology evolution, increasing software and services monetisation, and continuing cost pressure across supply chains. PW Consulting’s modelling shows the global market expanding from approximately USD 7.5 billion in 2025 to roughly USD 13.5 billion by 2032 — an implied compound annual growth rate of 8.74% over the 2026–2032 forecast horizon. This trajectory masks important inflection points: product differentiation around grid‑forming functionality, rapid adoption of modular high‑power blocks, and intensified competition among OEMs pursuing scale and service revenues.
Worldwide Utility Scale String Inverter Market
Key market dynamics shaping 2026 choices
-
Policy and tax timing: Recent US tax code changes and the One Big Beautiful Bill Act (OBBBA) introduced in mid‑2025 recalibrate incentives for clean electricity and investment tax credits. The specified start and placed‑in‑service thresholds create a hard timetable for project finance decisions; developers and OEMs must now synchronise delivery, commissioning, and warranty structures to capture or adapt to shifting tax eligibility windows.
Worldwide Utility Scale String Inverter Market -
Supply‑chain pressure and component costs: Raw material cost volatility — exemplified by polysilicon price movements in 2025 — has transmitted into inverter BOM and pricing considerations. Procurement teams should assume continued price elasticity in key inputs and embed flexible sourcing and hedging strategies into 2026 contracts.
-
Labour and balance‑of‑system costs: In mature markets, recent labour cost inflation for utility‑scale deployments has driven higher installed system economics. This changes the value proposition for inverters that reduce on‑site commissioning complexity, enable faster commissioning cycles, and minimise O&M touchpoints.
-
Technology convergence: The combination of modular high‑power blocks, AI‑enabled fault detection, and grid‑forming capabilities is shifting architectural preferences for large PV fleets. Independent analysis notes that string architectures now constitute a majority share of on‑grid utility‑scale inverter deployments, driven by modularity and lifecycle cost advantages.
-
Consolidation and concentration: Market concentration is material. The top three firms capture a majority share of market revenues and the top five are responsible for over two‑thirds of market value, accelerating competitive pressure around scale, service offerings, and financing relationships.
What the report delivers — practical, transaction‑ready intelligence
PW Consulting’s full report is designed as an operational playbook for 2026. Key deliverables include:
-
Validated market sizing and a transparent forecasting model covering 2020–2032, with scenario runs that stress policy shifts, raw material shocks, and accelerated decentralised grid services.
-
Commercial scorecards for leading OEMs that quantify product capability gaps, manufacturing footprint risk, and aftermarket service potential — enabling targeted partnership and M&A screening.
-
Procurement playbooks that translate component price trajectories into contract clauses, options for long‑lead items, and suggested inventory buffers to preserve project IRR under multiple scenarios.
-
Technology roadmaps and system integration guidance for developers and EPCs to specify inverters that reduce commissioning time, lower warranty exposure, and unlock ancillary revenue (e.g., frequency regulation, reactive power).
-
Investment and product strategy checklists: frameworks to prioritise R&D spend between hardware, embedded software, and cloud services; decision matrices for pursuing high‑power (>250 kW) vs. mid‑power (100–250 kW) segments; and suggested KPIs for service business success.
Competitive landscape — what matters to strategic planners
The utility string inverter competitive set blends global scale incumbents, nimble modular innovators, and vertically integrated energy OEMs. Several firm‑level patterns stand out for 2026 planning:
-
Scale and modularity leaders: Companies that have combined high shipment volumes with modular, block‑based architectures (including highly publicised product lines from large China‑headquartered OEMs) are positioned to offer rapid deployment options for large plant builds, reducing scheduling risk for developers.
-
Technology differentiation via software and AI: Vendors that embed AI‑driven diagnostics and arc‑fault detection into their string platforms deliver measurable reductions in O&M spend and uptime risk. This creates opportunities for SaaS monetisation tied to performance guarantees.
-
European and US specialists focusing on grid rules and governance: Manufacturers with deep experience in complex grid markets are emphasising features such as grid‑forming capability, high‑voltage topologies, and compliance engineering — an important consideration for projects in jurisdictions tightening interconnection requirements.
-
New entrants and incumbents expanding into utility scale: Several microinverter and commercial‑scale vendors are scaling up into utility applications via high‑voltage string platforms, spurred by demand for distributed, modular solutions that simplify maintenance.
Representative recent moves underline the pace of competitive evolution: major manufacturers have announced product launches featuring modular 800 kW+ scalable blocks, AI fault detection, and grid‑forming operation; at least one European manufacturer expanded domestic production in 2026 to meet demand for high‑capacity central and string solutions. These developments will compress product cycles and place a premium on rapid NPI (new product introduction) execution and manufacturing agility.
Strategic recommendations for 2026 — five priority moves
-
Embed policy timing into contract triggers. For projects with tax or incentive cliffs, make supplier performance linked to defined commissioning milestones, and include contingency options for scope reallocation if incentive qualification windows shift.
-
Hedge component exposure and diversify BOM sources. Execute multi‑tier sourcing and consider limited forward purchase commitments for critical inputs, while negotiating price pass‑through protections tied to transparent third‑party indices.
-
Accelerate software and service monetisation. Transition from a hardware‑only model to combined product‑software offerings that capture O&M and performance‑based revenue; use AI diagnostics as a differentiator in warranty economics.
-
Pursue targeted capacity and footprint decisions. For OEMs, consider geographically balanced capacity expansions that align with market access and tariff/tax advantages; for developers and EPCs, prioritise equipment partners with local support ecosystems to reduce labour‑intensive commissioning risk.
-
Use M&A and JV activity to close capability gaps quickly. Where organic development of grid‑forming controls or high‑voltage modularity is slow or expensive, target acquisitions or strategic alliances to secure validated IP and established field performance.
Why PW Consulting’s analysis is unique
Our research couples bottom‑up shipment and project pipeline validation with dynamic scenario modelling that explicitly accounts for regulatory cliffs, raw material price swings, and labour cost trajectories. We quantify concentration metrics and overlay supplier capability maps to help clients answer high‑stakes questions in 2026: which suppliers to endorse in EPC contracts, where to site production expansion, how to price long‑term service agreements, and which product features to prioritise in R&D spend.
Because of the commercial sensitivity of customer and region/application splits, our public briefing intentionally omits detailed segment tables and granular regional breakouts. This “trailer” approach preserves the strategic surprise for subscribers while providing enough high‑confidence insight to inform executive conversations. The full report includes exhaustive segmentations, downloadable model files, supplier scorecards, and a 12‑month decision calendar tailored for buyers, OEMs, and investors.
Next steps for executives
-
Download the full report for the complete dataset, including detailed segmentation tables, supplier scorecards, and a downloadable forecast model.
-
Book a strategic briefing with PW Consulting to translate the modelling into a customised action plan — we offer scenario workshops that map product, procurement, and M&A options against client‑specific project pipelines.
Contact PW Consulting to reserve your copy of the Worldwide Utility Scale String Inverter Market report and to schedule a 2026 strategic planning session. Let us help you convert market clarity into competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Utility Scale String Inverter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com