

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Dairy-Free Infant Formula Market Set to Hit USD 2.65 Billion in 2025, Expanding at a 6.85% CAGR Through 2032

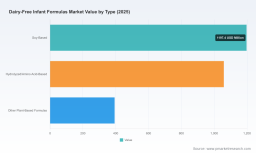
Worldwide Dairy-Free Infant Formulas Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market study on the worldwide dairy-free infant formulas sector delivers a focused, actionable intelligence package intended to inform executive decision-making throughout 2026. Built on a 2020–2025 historical baseline (base year 2025) and a 2026–2032 forecast horizon, the report frames a sector that has moved from niche to mainstream: the market advanced materially during the first half of the decade and, with a modeled compound annual growth rate of 6.85% for 2026–2032, is projected to expand further toward multi‑billion dollar scale by the end of the forecast window. This briefing synthesizes the strategic implications of those dynamics — showing the depth of our analysis while reserving proprietary, granular splits for the full report.
Worldwide Dairy-Free Infant Formulas Market
Why 2026 is a Strategic Inflection Point
Multiple forces converge in 2026 to make it a pivotal year for incumbents and challengers alike. Consumer demand for dairy-free, plant-based infant nutrition continues to rise on the back of allergy awareness, lactose intolerance diagnoses, and shifting dietary preferences among younger parents seeking “clean-label” and sustainable options. At the same time, regulatory activity and food-safety events have elevated the bar for ingredient validation, traceability, and quality assurance. These twin trends create both opportunity and regulatory/compliance risk — and they require deliberate, fast-moving strategic responses.
Worldwide Dairy-Free Infant Formulas Market
Market Dynamics and Structural Drivers
-
Robust expansion trajectory: After steady growth through 2020–2025, the sector’s modeled growth path envisions continued acceleration into the early 2030s driven by product innovation, improved regulatory clarity for plant-based formulations, and stronger retail and online distribution support.
Worldwide Dairy-Free Infant Formulas Market -
Demand-side segmentation: Differentiation is crystallizing along clinical needs (e.g., infants with milk-protein sensitivity), lifestyle positioning (organic/clean-label), and ingredient provenance (soy vs non-soy plant proteins). These consumer signals demand distinct R&D, claims frameworks, and go‑to‑market plays.
-
Supply-side realities: Soy-based protein remains the predominant technical solution in the dairy-free category due to established nutritional profiles and manufacturing familiarity. However, disruptive entrants pursuing non-soy whole‑food matrices are forcing incumbents to evaluate new protein platforms and reformulation strategies.
-
Concentration and competitive intensity: Market concentration is meaningful among top players, creating high entry barriers in conventional channels while leaving pockets of white space in premium, organic, and direct‑to‑consumer segments.
Competitive Landscape — Strategic Profiles and Imperatives
The competitive set spans global incumbents with deep manufacturing and regulatory heft, regional brand families, and insurgent specialists focused on novel plant proteins and organic credentials. Key dynamics include:
-
Incumbent defense: Large multinationals leverage scale to secure shelf space, meet regulatory obligations, and sustain clinical-level R&D. Their playbook centers on incremental innovation (plant-blends, targeted hypoallergenic SKUs) and portfolio tiering to cover mass-market and specialty needs.
-
Specialist disruption: Startups and challenger brands are introducing non-soy, whole‑food protein platforms and premium organic propositions that appeal to a subset of health‑conscious parents. These players drive category redefinition and can be attractive M&A or partnership targets for incumbents seeking rapid capability acquisition.
-
Private-label and channel plays: Store-brand manufacturers and contract producers are using price and availability to capture value — a dynamic that pressures national brands but also expands overall category penetration.
Strategically, market leaders should balance defensive investments to protect core share with selective bets on high-growth niches. Smaller and mid‑sized players must choose between doubling down on distinctiveness (ingredient story, organic certification, D2C experience) or vertically integrating via toll-manufacturing, co‑pack arrangements, or licensing deals to scale.
Regulatory and Safety Context — Risks and Windows of Opportunity
-
Heightened regulatory activity: Recent and ongoing FDA actions — including updated labeling compliance periods, guidance on plant-based claims, and programmatic initiatives to modernize infant formula nutrient standards — increase both compliance complexity and the value of early regulatory engagement.
-
Pathways for innovation: Initiatives that clarify protein-quality assessment (e.g., renewed attention to protein efficiency ratio guidance and nutrient validation pathways) are creating routings for non‑soy, plant‑based formulas to achieve regulatory acceptance if backed by appropriate science packages.
-
Safety events as a market accelerant for trust: High-profile recalls tied to supplier contamination have shortened the timeline for many manufacturers to invest in supplier monitoring, in-house QC, and transparent traceability — expenditures that will increasingly separate trusted brands from lower-cost alternatives.
Recent Industry Signals to Track
-
Regulatory advancement for non-soy protein validation — a government-level acknowledgement that opens a commercialization runway for whole-food plant-based infant formulas if accompanying studies meet the new expectations.
-
Supply‑chain shocks and recalls tied to ingredient contamination — reinforcing the strategic imperative of multi-sourcing and upstream risk mitigation.
-
New product launches from mainstream and adjacent players — indicating broader retailer appetite and category expansion, not necessarily limited to dairy-free SKUs.
Strategic Imperatives & Tactical Playbook for 2026
Executives who treat 2026 as a year for decisive capability building will materially improve their optionality for 2027–2030. Our report emphasizes immediate actions across six pillars:
-
Regulatory-first R&D: Invest in protein-quality studies and dossier development now. The regulatory environment favors entrants that can present robust, standardized evidence packages aligned with the latest guidance.
-
Quality and traceability investments: Strengthen supplier controls, implement batch-level traceability, and adopt independent third‑party testing to rebuild and sustain consumer trust after safety incidents in the category.
-
Channel and pricing choreography: Align assortment strategies between mass retail, specialty pharmacies, and D2C channels to manage margin tension while targeting consumer cohorts that will pay premiums for organic or non-soy credentials.
-
Portfolio architecture: Decide which SKUs are defensive (protect core share) versus offensive (entering new niche segments). Maintain a clear innovation funnel that balances reformulation, line extensions, and platform bets.
-
M&A and partnership discipline: Prioritize partnerships that deliver capability (ingredient technology, infant-nutrition clinical evidence, D2C marketing) rather than solely scale. We identify target archetypes in the full report.
-
Stakeholder and policy engagement: Proactively engage with regulators, advocacy groups, and pediatric nutritionists to help shape practical labeling and nutrient assessment standards — and to accelerate favorable pathways for novel plant-based products.
Top Tactical Recommendations (Executive Checklist for 2026)
- Commission a protein‑quality validation roadmap (6–12 month timeline) tied to regulatory submission milestones.
- Institute dual sourcing for key oils and protein concentrates and contract minimums with certified suppliers.
- Define a three‑tier portfolio for mass, premium organic, and clinical‑grade dairy‑free SKUs with distinct margin and GTM plans.
- Allocate capex to in‑line microbiological and contaminant monitoring, and publish periodic supplier audits to strengthen brand trust.
- Identify two strategic M&A or co‑development targets (ingredient tech + D2C brand) and initiate exclusivity conversations.
- Prepare transparent consumer communications on labeling and nutrient equivalency to pre-empt regulatory scrutiny and build trust.
- Run scenario financial models (base / constrained supply / accelerated adoption) to stress-test pricing, working capital, and margin outcomes for 2026–2028.
What PW Consulting’s Full Report Delivers
The published report goes beyond this executive briefing to provide the tactical tools procurement, regulatory, commercial, and corporate development teams need to act in 2026. Included are:
- Detailed, auditable financial models and scenario forecasts across the 2026–2032 horizon (regional and channelized breakdowns).
- Segment-specific go‑to‑market playbooks showing prioritized retail and e‑commerce strategies and estimated payback timelines.
- A regulatory roadmap and dossier checklist for non‑soy and plant‑based protein submissions aligned to the latest agency guidances.
- An actionable supplier-risk matrix, quality assurance templates, and traceability implementation plans.
- Profiles and deal rationales for acquisition and partnership targets, with commercial synergies and integration risk analyses.
- Operational KPIs and a 12–24 month implementation timeline tailored to three company archetypes: incumbent, challenger, and private‑label manufacturer.
To preserve the report’s commercial value and to respect proprietary modeling, this briefing intentionally omits granular regional and channel-level figures. Executives seeking the full revenue and unit forecasts, split scenarios, and company-by-company financial benchmarking can access the complete dataset and downloadable tools via our publication page.
Closing — How to Use This Briefing in Your 2026 Planning Cycle
Use this briefing to inform your 2026 operating plan: allocate budget to regulatory science and quality assurance, prioritize a narrow set of product bets with defined success metrics, and adopt partnership-first approaches where internal capabilities are lacking. The combination of rising consumer interest, clearer regulatory signposts, and intensifying competitive moves makes 2026 a year to shift from reactive compliance to proactive leadership.
PW Consulting stands ready to support executive teams with tailored scenario modeling, regulatory dossier preparation, and M&A execution. For the comprehensive dataset, proprietary segmentation, and full implementation playbook, please consult the Worldwide Dairy‑Free Infant Formulas Market report page or contact our industry team.
For detailed analysis of this topic, please visit the official page: Worldwide Dairy-Free Infant Formulas Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com