

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide High Voltage System Market to Jump from USD 74,550 Million (2025) to USD 247,030 Million by 2032 at 18.64% CAGR

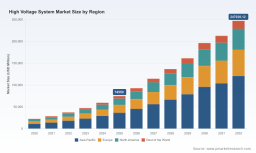
Worldwide High Voltage System Market: Strategic Imperatives for 2026 — PW Consulting Preview
As energy transition projects accelerate and grid architectures evolve, the worldwide high voltage (HV) systems market is entering a decisive phase for industry leaders and their strategic plans. PW Consulting’s newest market study — grounded in five years of historical data (2020–2025) and a seven‑year forecast horizon (2026–2032) — shows the global market expanding rapidly: from roughly USD 22.5 billion in 2020 to USD 74.6 billion in 2025, and continuing at a compound annual growth rate (CAGR) of approximately 18.6% into the forecast period. By 2032 the market is projected to surpass USD 247 billion. For corporate leaders planning 2026 capital allocation, procurement strategies, and M&A roadmaps, these macro trajectories are only the starting point.
Worldwide High Voltage System Market
Why 2026 Is a Strategic Inflection Point
Several converging dynamics make 2026 a pivotal year to translate strategy into action:
Worldwide High Voltage System Market
- Project acceleration and policy openings: Significant HVDC and high‑voltage transmission projects have come online or moved into advanced execution, reshaping regional demand patterns and procurement timetables.
- Supply‑side realignment: Large manufacturing investments by tier‑one suppliers and multi‑billion‑dollar cable and converter contracts are shifting competitive footprints, while raw material pressures and extended lead times are forcing new sourcing and inventory approaches.
- Technology bifurcation: The market is maturing around distinct architectural choices — from established medium‑voltage systems to higher‑voltage (including ultra‑high and 800V‑class) HVDC deployments that prioritize efficiency for long‑distance renewable transport.
- Capital scrutiny: Investors, utilities and developers are demanding more rigorous project risk analysis and staged investment triggers before sanctioning large transmission programs.
What PW Consulting’s Report Delivers — Practical, Actionable Modules
Our report is purposely designed for decision-makers who must convert market insight into executable plans in 2026. Key practical elements include:
Worldwide High Voltage System Market
- Executive strategy playbook: Scenario‑based recommendations for OEMs, EPCs, utilities and private capital on bidding posture, JV structures and capability investments under different policy and commodity scenarios.
- Supply chain stress test: Proprietary modeling of lead‑time exposures (including transformer and cable bottlenecks), price sensitivity to steel and copper inflation, and mitigation tactics such as near‑shoring, hedge procurement, and factory footprint optimization.
- Capital allocation model: A dynamic capex calculator that translates project timelines and regulatory milestones into cash‑flow stress points, enabling finance teams to sequence investments and prioritize projects with the highest risk‑adjusted returns.
- Technology adoption timeline: Comparative analysis of converter technologies (VSC, LCC, MMC and hybrid topologies), including where each delivers the best value for offshore wind collectors, long‑distance interconnects or multi‑terminal grids.
- Supplier scorecard and M&A radar: Valuation‑aware shortlists and capability maps for tuck‑ins and strategic acquisitions that accelerate entry into cable systems, converter factories or digital substation solutions.
- Project pipeline mapping: A curated, near‑term project inventory tied to procurement windows, enabling OEMs and suppliers to align commercial capacity with revenue windows and avoid stranded backlog.
Competitive Landscape: What Top Players Are Signaling
The market exhibits moderate concentration: a handful of global incumbents continue to command meaningful shares, but competition is intensifying as cable specialists, regional OEMs and system integrators scale up. PW Consulting’s qualitative analysis of principal players highlights strategic positioning and near‑term moves:
- Hitachi Energy (Zurich) — A global leader in HVDC and transmission solutions with strong project execution capabilities. Recent investments in U.S. manufacturing capacity signal a dual strategy: secure domestic supply for data centers and grid projects, and reduce lead‑time exposure for large transformers.
- Siemens Energy (Munich) — Focused on modular multilevel converter platforms and integrated grid solutions, with advantages in offshore wind integration and complex multiterminal projects.
- GE Vernova (Cambridge, MA) — Leveraging a broad installed base and turnkey HVDC expertise; recent consortium wins on high‑capacity offshore links demonstrate continued competitiveness at scale.
- Mitsubishi Electric & Toshiba — Both maintain depth in converter stations and power electronics, and remain go‑to partners for reliability‑critical bulk power projects.
- Schneider Electric & Eaton — Strengths lie in high‑voltage switchgear, substation automation and digitalization tools that are increasingly required alongside traditional HV hardware.
- Prysmian Group, Nexans, Sumitomo, NKT — Cable specialists that are capitalizing on rising subsea and onshore interconnector demand; recent contracting activity underscores the premium placed on manufacturing scale and delivery certainty.
- Chinese suppliers (TBEA, NR Electric) — Building global footprints through competitive pricing and turnkey delivery, particularly for large domestic and regional transmission projects across Asia and Africa.
- Hyundai Electric, BHEL — Regional powerhouses with strength in switchgear and transformers, increasingly competitive in cross‑border transmission tenders.
In short: incumbency still matters, but execution speed, supply certainty and system integration capability increasingly define winners.
Recent Events That Must Shape 2026 Strategy
Selected market developments in late 2024–early 2026 have immediate strategic implications:
- Large contract awards for multi‑GW offshore and long‑distance HVDC connections are accelerating demand for specialized converters and high‑voltage cables — improving revenue visibility for participants with ready manufacturing capacity.
- Major manufacturing investments by established OEMs indicate a shift toward onshore capacity expansion to shorten supply chains and serve fast‑moving national programs.
- Government and regulator initiatives — such as DOE‑backed programs for lower‑cost converters and the commercial start of significant cross‑border DC corridors — are lowering technical and regulatory barriers for new HVDC deployments.
- Raw material and equipment constraints: Transformer lead times and price inflation (industry data indicate substantial price escalation for large units since 2019) remain acute risks that materially affect project economics and delivery schedules.
Implications for Procurement, Project Developers and Investors
For procurement leaders and project sponsors, the PW report translates macro momentum into specific 2026 actions:
- Time‑shift procurement decisions: Secure critical long‑lead items earlier in the year and consider contract structures that share commodity and logistics risk with suppliers.
- Balance CAPEX and schedule risk: Use staged contracting and modular delivery to limit exposure to unexpected price spikes or supply delays.
- Pursue strategic partnerships: Joint ventures with cable manufacturers or converter specialists can be the fastest route to de‑risk delivery on large offshore or long‑distance projects.
- Rethink geographic exposure: Manufacturing investments and legislative changes are re‑shaping where projects are most executable — adjust market entry and footprint plans accordingly.
- Embed digital and O&M into bids: Substation automation and predictive diagnostics are no longer optional — they materially reduce lifecycle costs and are decisive in competitive tenders.
Report Limitations and Where to Find the Full Intelligence
This preview highlights the strategic contours and decision points we expect to matter in 2026. To preserve the integrity of PW Consulting’s proprietary forecasting and to ensure clients receive the full operational utility of our work, this article intentionally omits detailed regional and component splits, unit‑level forecasts and sensitive scenario matrices. The full study contains granular regional breakdowns, component and voltage‑level forecasts, supplier market shares, project‑by‑project commissioning timetables, and executable playbooks tailored to OEMs, utilities, and investors.
PW Consulting’s Worldwide High Voltage System Market report also includes downloadable tools and models that executives can adapt to their internal financial frameworks: a procurement readiness checklist, a supplier evaluation template, a capital allocation stress‑testing workbook, and an investor‑oriented pipeline valuation model.
Next Steps for Leaders Planning 2026
- Prioritize supplier engagements now — lead times and site readiness windows are compressing.
- Run the report’s scenario model against your project portfolio to identify vulnerable items and re‑sequence spend where necessary.
- Consider near‑term strategic investments (manufacturing, JV, or targeted M&A) to lock in capacity and reduce exposure to raw material and logistics volatility.
- Engage with regulators and transmission system operators early — permitting and right‑of‑way availability will remain gating factors despite strong policy support.
PW Consulting’s comprehensive market study is designed to be the practical backbone of those decisions. For access to the full dataset, supplier rankings, and the downloadable strategic toolkits, visit PW Consulting’s report page and request the Worldwide High Voltage System Market full study and executive briefing.
For detailed analysis of this topic, please visit the official page: Worldwide High Voltage System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com