

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Towed Array Sonar Market to Reach USD 1,825.23 Million by 2032, Expanding at a 5.2% CAGR (2026–2032)

Worldwide Towed Array Sonar System Market: Strategic Outlook for 2026 Decision Makers
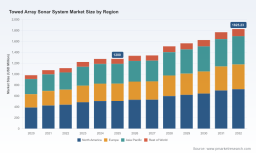
PW Consulting today releases an executive briefing drawn from our forthcoming Worldwide Towed Array Sonar System Market report, designed to equip defense planners, procurement leads, investors and industry strategists with the forward-looking commercial and operational context they need as 2026 spending cycles begin. The global market has evolved from roughly USD 980 Million in 2020 to about USD 1,280 Million in 2025, and our forecast anticipates continued expansion through 2032 — reaching approximately USD 1,825 Million by the end of the period, at a compound annual growth rate (CAGR) of 5.2% across 2026–2032.
Worldwide Towed Array Sonar System Market
Why this report matters for 2026 decisions
-
Timing and visibility: Ministries of Defence and prime contractors face conflicting priorities between near-term fleet upgrades and mid-term capability investments (platform integration, unmanned systems and variable-depth solutions). The report ties demand signals to procurement windows, helping teams align CapEx allocations and contract strategies with market momentum.
Worldwide Towed Array Sonar System Market -
Supply chain resilience: With transducer-grade piezoelectric ceramics (PZT) under pressure following raw material constraints — a documented price uptick tied to rare earth export dynamics — procurement teams must structure multi-year sourcing and strategic stockholding. The analysis quantifies exposure across component tiers and models cost sensitivity under different commodity and logistics scenarios.
Worldwide Towed Array Sonar System Market -
Technology and platform roadmaps: As navies accelerate integration of towed arrays into surface ships, submarines and increasingly unmanned platforms, the report maps the implication of active/passive architecture trends, processing and algorithmic investments, and integration complexity on lifecycle cost and upgrade pathways.
-
Export and partnership risk: Stringent export control regimes remain a core constraint. The report provides an operational playbook for managing ITAR and Wassenaar-related restrictions, and for structuring international partnerships that preserve access to key technologies while meeting sovereign requirements.
What the report contains (practical, actionable deliverables)
-
Market sizing and seven-year forecast (2026–2032) with scenario modeling addressing supply shocks, procurement acceleration and delayed fleet modernizations.
-
Commercial intelligence pack for buyers and suppliers: tender pipeline analysis, contracting models (unit buys vs. sustainment frameworks), and TCO-based procurement prioritization tools.
-
Supply chain heat maps and mitigation strategies, including component-by-component risk scoring (transducers, tow cables, signal processors, ship integrations) and recommended hedging actions.
-
Technology trajectory assessment, contrasting passive and active towed array investments, the role of low-frequency LFA systems, and the integration imperative with unmanned systems.
-
Regulatory impact assessment that operationalizes export control constraints into contracting, localization and IP-sharing strategies.
-
Operator-level upgrade playbooks for surface ship and submarine programs, including retrofit sequencing, test & evaluation milestones, and cost-risk trade-offs.
-
Competitor profiles and procurement intelligence, with an emphasis on capability differentials, platform fit, partnership footprints and recent program movements.
Competitive dynamics — what executives need to know
The towed array sonar market remains concentrated and technology-driven. Our analysis identifies a compact competitive set where a small number of primes command a material share of program awards and integration know-how. This concentration creates both opportunity and risk: established players bring reduced integration risk for large platform programs, while mid-tier specialized vendors are increasingly relevant for upgrades and niche exports.
-
L3Harris Technologies (Melbourne, FL, USA) — a preeminent integrator, noted for its AN/SQQ-89 suite integration and thin-line arrays used across US Navy surface and submarine programs. Recent contract awards for multi-function array upgrades underscore its position in sustainment and incremental modernization.
-
Thales Group (Paris, France) — a key supplier of variable-depth and towed array systems (CAPTAS family), active in allied frigate and destroyer programs and visible in recent deliveries to Western navies.
-
Lockheed Martin Corporation (Bethesda, MD, USA) — integrates strategic solutions (including long-range low-frequency systems and submarine-fit arrays) and continues to milestone integration on next-generation submarine blocks.
-
Atlas Elektronik (ThyssenKrupp Marine Systems, Bremen, Germany) — strong in low-frequency towed array design for submarine platforms, leveraging deep naval engineering heritage.
-
Leonardo S.p.A. (Rome, Italy) — offers export-friendly systems tailored to frigate programs and regional partnerships, pairing hardware with tailored support packages.
-
Ultra Maritime (Dartmouth, UK) — a specialist supplier focusing on retrofit and upgrade pathways for frigates and allied ASW platforms, with solutions attractive to navies pursuing incremental capability lifts.
Recent program developments further shape supplier positioning. Notable examples include a late-2025 US Navy contract for multi-function towed array upgrades, a mid-2025 delivery of a CAPTAS variant to a NATO ally, and a 2024 integration milestone for a submarine-block towed array — all illustrative of an active procurement landscape where sustainment and new-build programs overlap.
Market structure and risk factors
-
Concentration: A small cohort of primes captures the majority of award flows. Buyers should leverage this structure to negotiate long-term support and integration commitments, while challengers should pursue clear niche differentiation.
-
Raw material pressures: PZT-based transducer inputs have experienced meaningful cost pressure linked to rare earth supply constraints; program budgets need to account for upstream commodity volatility and potential lead-time expansion.
-
Export controls: ITAR and multilateral control regimes materially influence partnership choices and local content strategies — a key determinant of market access in export markets.
-
Geopolitical demand drivers: Indo-Pacific tensions and allied cooperation frameworks (notably accelerated tri-lateral initiatives) are expanding procurement pipelines and joint development projects, increasing both demand and interoperability requirements.
Practical strategic recommendations for 2026
-
Align procurement cycles with commodity hedging: Integrate PZT price and lead-time scenarios into contract clauses and milestone payments to avoid budget overruns.
-
Prioritize modularity in new contracts: Require modular open-architecture interfaces to preserve upgrade flexibility and lower long-term integration cost.
-
Structure export-compliant partnerships: Use joint-venture and licensed production models to navigate export controls while maintaining access to critical algorithms and components.
-
Accelerate unmanned integration pilots: Allocate small rapid-acquisition pots to validate sensor-to-UUV integrations and operational concepts ahead of large-scale buys.
-
Negotiate sustainment-bundled deals: Lock in long-term sustainment to reduce lifecycle cost and secure spare-part flows in a constrained supply environment.
-
Adopt phased capability baselines: Decompose capability requirements into essential near-term and aspirational mid-term blocks to retain budget flexibility.
How PW Consulting’s report supports execution
Our full report provides the calibrated evidence base behind the recommendations above: granular procurement timelines, supplier scorecards, a supplier concentration analysis, supply chain stress tests, and executable contract language templates designed for 2026 procurement cycles. To honor the “trailer” principle and preserve the commercial utility of the research, we present the in-depth segmentation datasets, vendor score matrices and full financial models exclusively in the complete report package.
Next steps and how to access the full analysis
For decision-makers preparing budgets, drafting RFPs or assessing supplier partnerships in 2026, the PW Consulting Worldwide Towed Array Sonar System Market report is intended as both a planning tool and an operational playbook. The full report includes downloadable models, a procurement-ready executive summary, and a confidential annex of supplier performance metrics.
Visit PW Consulting’s report page to request the full study, order workshop sessions for program teams, or commission bespoke analyses tailored to your acquisition or investor objectives.
For detailed analysis of this topic, please visit the official page: Worldwide Towed Array Sonar System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com