

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Cosmetic-Grade Retinol Market Poised to Expand at a 6.92% CAGR Through 2032

PW Consulting — Strategic Outlook: Worldwide Cosmetic Grade Retinol Market (Official Release)
Executive summary
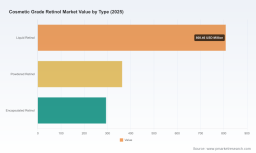
Cosmetic grade retinol remains one of the most strategically significant actives in personal care formulations, straddling premium anti‑aging propositions and broad mass‑market usage. Our latest Worldwide Cosmetic Grade Retinol Market report establishes a clear picture of that strategic value: the market reached approximately USD 1,465.5 Million in the base year 2025 and is forecast to expand at a compound annual growth rate (CAGR) of 6.92% across the 2026–2032 horizon, reaching roughly USD 2,341.0 Million by 2032 under the central case. For 2026 specifically, the market trajectory and regulatory inflection points make this report a practical roadmap for commercial, regulatory and R&D decisions.
Worldwide Cosmetic Grade Retinol Market
Why this report matters for 2026 decision‑making
- Regulatory inflection will redraw addressable formulations: New concentration caps and labeling mandates in key markets are driving reformulation and portfolio reclassification. Companies that preemptively align product specifications, dosages and labeling with the incoming regime will avoid costly recalls and speed time‑to‑market for reformulated SKUs.
- Margin pressure vs. premiumization tension: Supply dynamics favor both scale providers and specialist delivery platforms. Players must balance cost efficiency with differential delivery technologies (stabilized and encapsulated forms) to defend price realization while protecting clinical claims.
- Supply chain due diligence becomes a strategic lever: The raw material base for cosmetic retinol is concentrated among synthetic routes (and a subset of extraction pathways). Securing validated suppliers with traceable quality systems and contingency capacity is now a boardroom priority.
- M&A and partnership windows are narrowing: With mid‑single‑digit CAGR and pockets of high strategic value (stabilized grades, encapsulation technologies, regulatory‑compliant formulations), 2026 is likely to see accelerated bolt‑on activity and JV discussions—especially where incumbents seek to internalize specialty delivery capabilities or geographic downstream access.
What the report delivers — practical, operational modules
Our research team structured the report to be directly usable in strategy workshops, procurement negotiations and R&D prioritization. Key deliverables include:
Worldwide Cosmetic Grade Retinol Market
- Market sizing and forward scenarios: Base‑year 2025 market sizing, historical trends (2020–2025) and three forecast scenarios to 2032. These scenarios isolate demand drivers such as premium anti‑aging adoption, mass‑market acne/brightening reformulation cycles, and regulatory impact pathways.
- Regulatory impact matrix and compliance playbook: A jurisdiction‑by‑jurisdiction analysis that translates concentration limits, labeling obligations and timelines into product‑level actions and compliance milestones—allowing product teams to prioritize SKU updates by risk exposure and commercial upside.
- Supply chain and sourcing toolkit: Supplier risk heatmaps, capacity shock simulations, and a validated shortlist of global and regional raw material providers with suggested contractual clauses (quality audits, force majeure, IP protections) to reduce continuity risk.
- Formulation & innovation briefing: Comparative evaluation of stabilization and delivery technologies, clinical endpoints commonly pursued with retinol actives, and a prioritization framework for internal R&D investments versus external technology partnerships.
- Commercial segmentation playbooks: Go‑to‑market templates for premium, masstige and mass channels that align formulation attributes, price architecture and communication strategies—designed to accelerate cross‑functional implementation.
- M&A and partnership screening: Financial and strategic screening criteria, sample term sheet considerations and integration checklists tailored to acquisitions of specialty ingredient providers, encapsulation technology firms or downstream private labels.
Regulatory and market dynamics shaping 2026
Two regulatory themes dominate near‑term strategy:
Worldwide Cosmetic Grade Retinol Market
- Harmonized concentration limits and mandatory consumer messaging in Europe: Recent measures set explicit maxima for retinol equivalents in topical products and mandate on‑pack language signaling the presence of Vitamin A and guidance on cumulative intake. These rules include staged implementation dates for new versus existing stock, creating an interim window for controlled rollouts and label updates.
- U.S. market governance and facility oversight: Continued implementation of modernized cosmetic regulatory frameworks increases the administrative burden on manufacturers and contract formulators. Facility registrations, product listings and upcoming GMP requirements raise the bar for supplier qualification and audit readiness.
These regulatory shifts are not merely compliance items; they change product economics and consumer communication strategy. Brands that replatform formulas to maintain efficacy at lower permitted concentrations, or that invest in delivery systems that demonstrate superior bioavailability or reduced irritation, will preserve premium positioning and claim substantiation.
Supply base and raw material realities
Cosmetic grade retinol continues to be produced primarily via controlled synthetic routes from established precursors, with high‑purity powder forms standard for bulk supply. The market features a mix of global specialty suppliers and larger chemical conglomerates, as well as regional manufacturers that provide scale and cost advantages. The report includes a supply concentration assessment and contingency playbooks for managing quality, lead times and import risk across primary sourcing corridors.
Competitive landscape — where incumbents and challengers create advantage
Market concentration metrics indicate a moderately consolidated supplier landscape, with the top three and top five players holding meaningful but not dominant combined shares. This structure yields strategic choices for brands and CPG firms:
- BASF SE (Ludwigshafen, Germany): A global leader noted for stabilized retinol grades and “clean” formulations. Recent product introductions that omit legacy stabilizers align with retailer and consumer demand for cleaner ingredient panels. Their scale and formulation expertise make them a default partner for large CPG clients seeking low‑risk reformulation pathways.
- DSM‑Firmenich (Heerlen, Netherlands): Positions innovation around derivative and stabilized vitamin A chemistries with a strong sustainability narrative. Their strength is in differentiated dosage forms and corporate sustainability frameworks attractive to brands targeting eco‑conscious consumers.
- Evonik Industries AG (Essen, Germany): Specialist in encapsulated delivery technologies; their platforms aim to reduce irritation while increasing retinol stability—attributes that directly support premium claim differentiation and regulatory compliance at constrained concentrations.
- Croda International Plc (Snaith, UK): Brings bio‑based ingredient credentials and formulation support, enabling brand stories that combine efficacy with sustainability—an increasingly important axis for market segmentation.
- Regional producers and high‑purity suppliers (selected European and Chinese manufacturers): Several manufacturers provide high‑purity bulk retinol and derivative forms at competitive cost and scale. They are strategic partners for price‑sensitive product lines, but require robust quality assurance and supply continuity oversight to meet the standards of premium buyers.
Strategically, buyers should segment supplier relationships: centralized, long‑term contracts with global majors for stabilized, compliance‑ready grades; tactical spot or regional contracts with volume producers to manage cost; and innovation partnerships with encapsulation specialists to maintain product differentiation.
Using this report in your 2026 playbook
Senior teams can apply the report directly in four areas:
- Portfolio triage: Map SKUs to regulatory risk and margin contribution to prioritize reformulation or phase‑out timelines.
- Procurement optimization: Re‑design sourcing strategies using the supplier risk matrix and contract templates to reduce unit cost volatility and secure capacity through 2032 scenarios.
- R&D and claims strategy: Use the formulation briefing to choose between higher‑potency stabilized grades and encapsulated delivery depending on tolerated irritation profiles and intended claims.
- M&A and alliance planning: Apply the M&A screening tool to identify bolt‑on targets that accelerate entry into encapsulation, sustainability credentials, or regional manufacturing footprints.
Methodology & what we intentionally withhold
The analysis rests on a combination of primary interviews with ingredient suppliers, brand formulators and trade channel experts; proprietary shipment and pricing datasets; synthesis of public regulatory texts; and bottom‑up capacity modeling. The report’s base year is 2025 with historical coverage from 2020–2025 and forecasts to 2032, all presented in USD (Million).
In line with our “teaser” approach for this release, we present robust macro sizing, scenario outcomes and supplier concentration metrics to support strategic planning, but detailed segment and regional breakouts—including exact regional market shares and application‑level revenue splits—are reserved for the full report and interactive data portal. This ensures you receive the granular intelligence required for direct commercial execution and negotiation.
Next steps — how to engage
For leadership teams preparing 2026 budgets and strategic initiatives, the report functions as both a short‑term playbook and a long‑range market map. PW Consulting can support bespoke deliverables: supplier due diligence packages, expedited formulation workshops, and M&A target screening based on criteria aligned to your strategic intent. Access to the full dataset and appendices (including the granular segmentation and supplier scorecards) is available through PW Consulting’s report portal and advisory services.
For detailed analysis of this topic, please visit the official page: Worldwide Cosmetic Grade Retinol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com