

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Aluminium Sulfate Market to Grow at a 3.8% CAGR (2026–2032) as Water Treatment Drives Demand

Worldwide Aluminium Sulfate Market — Strategic Outlook for 2026 Decision-Making
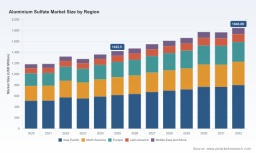
PW Consulting’s latest market study on the Worldwide Aluminium Sulfate market synthesizes multi-year historical data (2020–2025), forward-looking scenario models (2026–2032), and practical playbooks for executives making near-term investment, procurement, and commercial decisions. At a glance, the global market is positioned to expand from USD 1,422.5 Million in the base year (2025) to approximately USD 1,846.9 Million by 2032, representing a compound annual growth rate (CAGR) of 3.8% over the forecast period. These headline figures mask important volatility drivers and structural shifts — our report decodes those forces and translates them into executable options for 2026.
Worldwide Aluminium Sulfate Market
What this report delivers — actionable intelligence, not academic summary
- Robust demand and supply modelling calibrated to 2020–2025 actuals and stress-tested across three macroeconomic scenarios for 2026–2032. Each scenario includes demand elasticity, price sensitivities, and feedstock-price transmission matrices.
- Practical procurement and hedging playbooks tied to raw-material dynamics (alumina hydrate and sulfuric acid), with contract templates, cost-pass-through thresholds, and tipping points for spot vs. long-term sourcing.
- A capital-allocation toolkit: CAPEX/OPEX benchmarks, plant-scale break-evens, and an investment prioritization matrix to support brownfield expansion, debottlenecking, or new-build projects.
- Competitive landscape diagnostics with capability maps and an M&A target shortlist—scored by strategic fit, geographic access, and asset quality—plus integration risk templates.
- Regulatory and trade-risk assessments, including import-duty scenarios and product classification implications, with compliance checklists tailored to major markets.
- Commercial playbooks for price segmentation, channel optimization, and value-added product development (including technical grades for water treatment, paper & pulp, textiles, and specialty applications).
Key market dynamics shaping 2026 choices
Three structural themes should govern executive planning in 2026:
Worldwide Aluminium Sulfate Market
- Feedstock and input-cost transmission: Alumina hydrate and sulfuric acid constitute the primary upstream cost base. Recent market intelligence shows alumina hydrate averaged near USD 385/metric ton in 2023, while sulfuric acid experienced an elevated band in Q4 2023 driven by fertilizer demand. These inputs create asymmetrical cost pass-through across regions and product grades. Procurement strategies that combine indexed contracts, regional supply diversification, and limited-term hedging will outperform static sourcing approaches.
- Trade policy and market access: Trade measures remain a material commercial constraint. For example, the US maintains anti-dumping duties on certain imports, reshaping global flows and pricing differentials. Companies that map tariff exposure to route-to-market strategies (local production, tolling, or bonded distribution) will retain margin control while protecting market share.
- Regulatory and sustainability pressures: Classification and environmental rules influence formulation choices and water-treatment acceptance. Notably, aluminium sulfate remains classified as non-hazardous for recognized water-treatment uses under relevant EU frameworks — a certainty that reduces compliance cost for municipal contracts but does not eliminate scrutiny related to lifecycle carbon and effluent management. Integrating low-carbon feedstock paths and transparent LCA data into bids will become a differentiator in procurement tenders.
Competitive landscape: fragmentation and strategic positions
The market exhibits moderate concentration: the top three players account for approximately 32.4% of industry sales, and the top five for around 46.8%. This structure creates pockets of competitive intensity and frequent regional leadership changes. Key incumbents and strategic considerations include:
Worldwide Aluminium Sulfate Market
- USALCO, LLC (Baltimore, MD, USA) — Strengths in liquid and dry grades for municipal and industrial water treatment. Plays to watch: leveraging solution-chemistry expertise to extend service contracts and move from commodity sales toward lifecycle water-treatment partnerships.
- Chemtrade Logistics Income Fund (Toronto, Canada) — High-purity alum producer with integrated logistics capabilities. Competitive advantage arises from combining chemical manufacturing with distribution optimization; a logical acquirer or partner for firms seeking North American market access or logistics resilience.
- GEO Specialty Chemicals, Inc. (Ambler, PA, USA) — Technical-grade supplier with multiple domestic sites. Strategic focus: specialty formulations for textiles and leather tanneries; growth lever is cross-selling technical coagulants into adjacent municipal accounts.
- GFS Chemicals, Inc. (Columbus, OH, USA) — Laboratory and industrial focus creates a high-margin niche. Opportunity: expand reagent lines into standardized bulk grades for municipal clients to stabilize volatility in specialty volumes.
- Kemira Oyj (Helsinki, Finland) — Global reach and aluminum-based coagulation expertise. Strategic strengths include integrated R&D and global sales channels; key decision is where to invest for capacity versus service-led differentiation.
- Ataman Kimya A.S. (Izmir, Turkey) and major Chinese and Indian producers — Several regional producers export granular and liquid grades. Their strategic advantage is cost-competitive capacity, but trade measures and freight volatility alter competitiveness. Near-term moves include deploying regional tolling hubs or entering distribution alliances to circumnavigate tariff barriers.
Implications for 2026 strategy — prioritized moves
Executives should prioritize a concise set of actions in 2026 to capture upside while containing downside risk:
- Revise procurement architecture: Adopt a layered sourcing model mixing (a) multi-year indexed contracts with select low-cost producers, (b) shorter spot windows to capture downward cycles, and (c) regional buffer inventories. Embed sulfuric-acid and alumina hydrate price triggers into supply contracts to enable pass-through or shared-risk clauses.
- Reassess capacity strategy: Before committing to greenfield plants, deploy brownfield debottlenecking and modular expansions. Our CAPEX calculator identifies scale thresholds where greenfield becomes advantaged — use it to vet projects against a 3.8% CAGR baseline and downside demand shocks.
- Value-over-volume commercial moves: Shift select accounts from commodity supply to service contracts (e.g., dosing expertise, performance SLAs) to protect margins, particularly in municipal water-treatment segments where long-term contracts are common.
- Trade and tax engineering: Model duty-impact scenarios and prepare alternative routing (third-country transshipment, local finishing) to mitigate punitive tariffs. Where legal, structure tolling or JV arrangements to preserve market access.
- M&A and partnerships: Target acquisitions should be prioritized for capability (technical grades), geographic access (distribution footprints), or feedstock integration. Our M&A scorecard ranks targets across commercial fit, asset quality, and regulatory exposure to accelerate screening.
- ESG and product stewardship: Build LCA-backed product claims for low-carbon alum lines and establish transparent effluent monitoring for major municipal contracts. This is both a procurement differentiator and a medium-term compliance hedge.
Risk matrix and contingency planning
Principal risks for 2026 include input-price spikes, abrupt trade-policy shifts, and localized demand shocks tied to municipal capex cycles. Our report maps these risks into probability-impact quadrants and provides pre-scripted contingency responses — from temporary margin-sharing contracts to rerouting supply chains and accelerated product substitution campaigns for exposed customer cohorts.
How PW Consulting’s analysis helps you act in 2026
Beyond headline forecasts, PW Consulting delivers models and templates designed for immediate operational use: procurement negotiation playbooks, a CAPEX prioritization toolset, regional tariff-impact simulators, and a proprietary margin-sensitivity dashboard that translates input-price moves into customer-level P&L outcomes. We intentionally present high-level findings here to demonstrate methodological rigor while reserving granular segmentation tables, company-level volume/price splits, and interactive scenario files for the full report package.
Next steps — use the intelligence, not just the numbers
For executives planning capital deployment, contract renegotiations, or market-entry strategies in 2026, the operative advantage will come from combining macro-forecast awareness with executional templates. PW Consulting’s Worldwide Aluminium Sulfate report is structured to convert market insight into operational action: detailed datasets, supplier scorecards, and negotiation-ready clauses are available in the full deliverable.
To access the full analysis, proprietary datasets, and the interactive decision-support tools referenced above, please visit the PW Consulting report page for the Worldwide Aluminium Sulfate Market. The full package contains the segment-level tables, regional and application breakdowns, and company-level metrics that informed the strategic recommendations summarized here.
For detailed analysis of this topic, please visit the official page: Worldwide Aluminium Sulfate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com