

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
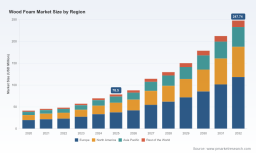
PW Consulting: Worldwide Wood Foam Market to Grow from USD 78.5 Million in 2025 to USD 247.74 Million by 2032 at a 17.84% CAGR — Europe Holds 37.5% Share

Worldwide Wood Foam Market: Strategic Imperatives for 2026
As global manufacturers and brand owners accelerate substitution of fossil-derived materials, wood-based foams have moved from niche experiment to boardroom priority. PW Consulting’s new Worldwide Wood Foam Market report frames why 2026 will be a decisive year for strategic decisions — not only for materials teams, but for C-suite leaders setting procurement, sustainability, and capital allocation agendas. Our analysis marries granular engineering realities with commercial go-to-market playbooks, delivering the kind of decision-grade intelligence that senior executives need to act with confidence.
Worldwide Wood Foam Market
Market trajectory: scale, speed, and what it unlocks
The wood foam sector is maturing rapidly. After a period of steady growth during 2020–2025, the market reached an estimated USD 78.5 million in 2025 and is projected to expand at a compound annual growth rate of 17.84% through our 2026–2032 forecast window. By the end of that horizon the market is expected to be approaching USD 248 million. That pace of expansion represents both a demand shock and a supply-chain stress test: investors, converters and OEMs must weigh the timing and scale of investments required to capture share and to meet regulatory and customer-driven decarbonization targets.
Worldwide Wood Foam Market
Why 2026 is a strategic inflection point
- Regulatory acceleration: Policy developments — most notably packaging regulations in major markets — are shifting procurement mandates toward fiber-based, recyclable alternatives. Materials engineered for kerbside recyclability in existing paper and cardboard streams reap near-term adoption advantages.
- Sustainability as a commercial lever: High-value customers are demanding documented circularity and low-carbon feedstocks. Wood foams produced from sustainably managed forest fibers can deliver credible life-cycle advantages when substitution pathways are correctly validated.
- Scale economics on the horizon: Pilot-scale validations and early commercial agreements have proven technical viability for several product lines. The question for many players in 2026 will be whether to build, partner, license or buy capacity as cost curves evolve.
Demand dynamics and application opportunities (what to prioritise)
Wood foam is not a single-market play: it spans protective packaging, building and construction, acoustic and thermal insulation, and selected transportation components. Each application presents a distinct value equation — from regulatory-driven replacement in single-use packaging to performance-led adoption in insulation and niche transport components where weight and end-of-life are priorities. Our assessment identifies “low-friction” adoption corridors where wood foam’s mechanical and circularity attributes align directly to buyer procurement drivers; these corridors should be the immediate focus of product teams entering or scaling in this market.
Worldwide Wood Foam Market
Technology and feedstock realities
Material science advances and process engineering are central to commercial success. There are two dominant process archetypes in play: industrialized, cellulose/wood-fiber-based foams designed for cushioning and packaging; and rigid, board-style foams optimized for insulation and structural lightweighting. Research institutions and industrial developers have converged on approaches that use sustainably sourced wood fibers as primary feedstock and avoid petrochemical foaming agents — a structural difference that enables both end-of-life compatibility with paper recycling streams and a compelling carbon story when feedstock certification is secured.
From a manufacturing perspective, scaling these technologies requires attention to water management, drying energy, density control, and post-processing for dimensional stability. The players who master low-energy drying and modular production cell designs will unlock the fastest route to competitive unit economics.
Supply chain structure and market concentration
The market is already showing meaningful concentration among early industrial-scale participants. The top-tier companies control a substantial share of commercialized supply and route-to-market relationships, creating both opportunities for fast followers and barriers for late entrants. Our concentration metrics indicate that a small set of players account for the majority of today’s available commercial capacity — a dynamic that has implications for pricing power, co-manufacturing arrangements, and M&A strategies.
Competitive landscape — capabilities that matter
- Stora Enso (Helsinki): As the primary industrial supplier of Fibrease® and Papira® product lines, Stora Enso has migrated wood-foam materials from lab validation to commercial supply. Their focus on delivering recyclable, fibre-based cushioning positions them as the benchmark for packaging-oriented applications.
- Fraunhofer WKI (Braunschweig): The research institute’s process innovations for 100% wood-based foams — engineered without petrochemical additives — are critical to the insulation and lightweight construction use-cases. Fraunhofer’s work accelerates process scalability and feedstock optimization for rigid board formats.
- Sourcing & distribution partners (NOVAPOR, Nature‑Pack, Nefab): Commercialization is being enabled through sheet and finishing suppliers, exclusive distributors and packaging system integrators. These partnerships shorten time-to-market for brand owners switching from polymer foams to fibre-based alternatives.
- Regional manufacturers (Reilly Foam, JB Polymers and others): A cohort of foam manufacturers is active in adapting existing production skills to wood-fiber systems. Their success will depend on process retrofits, access to certified fiber, and strategic alliances with technology licensors or IP owners.
Recent industry developments reinforce the shift from experimentation to industrialisation: lead suppliers have announced pilot-scale commercial supply and validated production runs, while converters in adjacent foam markets are expanding capacity to capture emergent demand. These moves presage a near-term period of strategic alignment and consolidation.
What PW Consulting’s report delivers — practical, transactional, and prescriptive
Our Worldwide Wood Foam Market report is designed as an executable toolkit for decision-makers in 2026. Highlights include:
- Market sizing and forward-looking scenarios with sensitivity analyses tied to feedstock price, energy cost, and policy adoption rates.
- Supplier benchmarking and a readiness matrix that maps technical capability to commercial routes (licensing, tolling, captive manufacture).
- Go-to-market playbooks for OEMs and packagers: procurement scorecards, pilot-to-scale timelines, and contract templates for offtake and co-development.
- Capex and Opex modelling templates, including modular plant layouts and break-even analyses at multiple throughput bands.
- Regulatory compliance checklists and pathway mapping for circularity claims, with specific attention to kerbside recyclability and packaging regulation alignment.
- Case studies and vendor negotiation playbooks focused on securing sustainable wood fiber supply and forest certification.
Importantly, the report intentionally refrains from publishing granular regional or application-level splits in public summaries — we treat those as premium decision-support artifacts available through the full dataset to preserve commercial confidentiality and to enable tailored licensing of the underlying models.
Strategic recommendations for executives — six immediate actions
- Prioritize pilot projects in use-cases where regulatory tailwinds and customer willingness-to-pay converge. Shortlist those corridors for rapid scale testing.
- Secure feedstock credentials early. Long-term contracts with certified suppliers or joint-venture forest management can be decisive in delivering credible scope-3 improvements.
- Design modular investments. Opt for phased-capex plants that can switch between flexible and rigid formats or that can be replicated geographically to reduce logistic cost exposure.
- Form distribution or co-packaging partnerships rather than building end-to-end stack where time-to-market matters most.
- Embed recyclability in product specifications and validate claims with third-party assays to avoid downstream rejection in recycling streams.
- Monitor consolidation windows for opportunistic acquisitions of converters or technology assets — early consolidation is likely to reshape pricing and route-to-market dynamics.
How to use this analysis in your 2026 planning cycle
Senior leaders should treat the wood foam opportunity as a cross-functional agenda item: sustainability, operations, procurement and corporate development must coordinate around pilots, supplier commitments and capex gating. PW Consulting’s playbooks convert market projections into executable project plans, enabling teams to transition from exploratory POCs to production contracts within a 12–24 month window.
For companies evaluating market entry or competitive response, the most valuable next step is access to the full quantitative dataset, supplier scorecards and our modular financial models. The public summary intentionally signals where the opportunity is concentrated while reserving the core segmentation and granular unit-economics for clients who require bespoke scenario modelling and implementation support.
Conclusion
Wood foam represents a meaningful, fast-growing segment within the broader transition away from petrochemical-based foams. The market’s trajectory — underpinned by robust policy momentum and tangible commercial progress from leading suppliers — creates attractive windows for both first movers and disciplined fast followers. In 2026, the decisions you make about partnerships, pilot scale-ups, and capital deployment will determine whether your organization captures strategic advantage or plays catch-up in an increasingly crowded field.
PW Consulting’s Worldwide Wood Foam Market report synthesizes technical, commercial and regulatory intelligence into a single, actionable roadmap. For teams ready to turn insight into implementation, the full report provides the proprietary segmentation, supplier benchmarking, and financial models necessary to execute with precision.
Contact PW Consulting to access the full report and the downloadable decision-support toolkit that underpins our 2026 recommendations.
For detailed analysis of this topic, please visit the official page: Worldwide Wood Foam Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com