

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Topical Dispenser Market Set to Expand at 6.92% CAGR as Pharmaceuticals and Skincare Drive Demand

Worldwide Topical Dispenser Market — Strategic Implications for 2026
PW Consulting’s newest market study on the Worldwide Topical Dispenser Market provides a focused, actionable intelligence brief for senior executives planning product, commercial, and M&A strategies in 2026. The report synthesizes proprietary modelling, supplier-level diligence, regulatory mapping, and practical scenario playbooks to translate market momentum into boardroom decisions. Below we outline the high-level takeaways and the specific ways leaders should use this research to sharpen 2026 execution — while reserving the detailed segment-level tables and supplier metrics for the full report.
Worldwide Topical Dispenser Market
Executive summary: a market in predictable acceleration
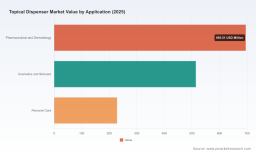
The topical dispenser market has moved from a niche medical-dermal accessory arena into a strategic component of therapeutic delivery and patient experience. PW Consulting’s base-year analysis (2025) captures robust expansion from 2020–2025 and a continuation of that trajectory into our forecast window. On a macro basis, the market grows at a compound annual growth rate (CAGR) of 6.92% through our forecast period, reflecting durable demand from pharmaceutical compounding, dermatology therapeutics, and premium cosmetic and personal-care applications. Total market value rises from roughly USD 1.04 billion in 2020 to approximately USD 1.44 billion in 2025, and our model projects steady growth to a multi-billion-dollar market by the conclusion of the forecast horizon.
Worldwide Topical Dispenser Market
Why 2026 is a decision inflection point
- Commercial channel transitions accelerate. Pharmacy compounding practices, specialty dermatology clinics, and contract manufacturers are standardizing dispenser formats — creating winners for scale-focused producers and opening tactical windows for niche innovators.
- Regulatory and reimbursement clarity crystallizes. Recent device clearances and evolving Medicare guidance have materially changed adoption economics for certain topical therapies and their applicators; companies that align product design with regulatory expectations in 2026 can shorten time-to-market and raise uptake.
- Consolidation dynamics offer optionality. Market concentration is moderate: a handful of suppliers capture a meaningful share without forming a tightly closed oligopoly. In practice, this creates opportunities for both bolt-on acquisitions and premium valuations for differentiated technology owners.
- Product differentiation matters more than ever. Metered-dose accuracy, preservative protection, patient ergonomics, and scalable manufacturing are the axes on which 2026 competitive battles will be fought.
What the report delivers (practical content for 2026 planners)
PW Consulting’s report is structured to support fast, evidence-based decisions. The deliverables include:
Worldwide Topical Dispenser Market
- Overarching market sizing and a calibrated growth model with scenario sensitivity for input variables (regulation, compounding adoption rates, end-market therapeutic cycles).
- Supplier dossier pack: strategic profiles, product roadmaps, manufacturing footprints, quality certifications, and commercial strengths/weaknesses for the meaningful incumbent and challenger set.
- Regulatory & reimbursement playbook: device classification mapping, 510(k) precedents, ISO 13485 implications for outsourcing, and payer guidance that can influence product design and go-to-market timing.
- Buy-side decision tools: acquisition target screeners, technology valuation heuristics, and integration checklists for manufacturing and quality systems.
- Commercial tactics & pilots: channel segmentation frameworks, recommended clinical evaluation designs to demonstrate dose uniformity or patient preference, and pricing strategies aligned to payer dynamics.
Key market dynamics and strategic risks
- Regulatory segmentation increases product value. Recent device clearances highlight that topical applicators can be regulated pathways into therapeutic markets. Conformity to 21 CFR device classifications and adherence to ISO 13485 for design/production are preconditions for scaling into regulated therapeutic workflows.
- Clinical performance differentiates procurements. Independent evaluations have demonstrated measurable differences in dose uniformity between metered-dose mechanisms and alternative airless designs for certain formulations; suppliers that can provide robust performance data gain procurement leverage.
- Reimbursement nuances constrain some adjacencies. Not all topical agents used with dispensers qualify for surgical-dressing benefits under public payers; understanding payer categorizations affects commercial models for therapeutic versus cosmetic applications.
- Supply chain and quality systems are entry hurdles. ISO- and FDA-compliant manufacturing, validated molding and assembly, and managed supply of critical components are determinants of partner selection, especially for pharmaceutical customers.
Competitive landscape — who to watch and why
The competitive field comprises specialized device innovators, global dispensing platforms, and contract manufacturers that provide end-to-end solutions. Several companies merit attention for distinct strategic reasons:
- DoseLogix (Cordica Medical / TEAM Technologies) — A focused innovator in metered dosing applicators for compounding pharmacies. DoseLogix’s recent product introductions underscore a strategy of improving pharmacist and patient experience through device ergonomics and container-compatibility; ideal partners for compounding-centric rollouts.
- Aptar Pharma — A global dispensing platform with strong capabilities in airless and semi-solid metering systems. Aptar’s emphasis on product protection, hygiene, and validated dosing positions it well for pharmaceutical-grade collaborations and large-scale supply agreements.
- Medisca — A compounding-focused supplier bridging sterile and non-sterile preparation use-cases. Their positioning favors clinical pharmacy channels where breadth of compounding-compatible formats is a procurement criterion.
- SpecializedRx Products, Health Care Logistics (HCL), Lucas Packaging Group — These suppliers address metered-dose needs across compounding and clinical settings; they are often selected for configurable dosing solutions and service-level responsiveness.
- Porex Corporation — A components play — porous plastics and reservoir technologies — that can be a differentiation lever for drug-device designs requiring controlled flow or breathable membranes.
- Silgan Dispensing and HTI Plastics — Manufacturers with precision healthcare dispensing expertise and quality certifications. HTI’s ISO 13485 registration highlights the strategic value of certified contract manufacturing when pharmaceutical customers demand device-level controls.
Recent industry developments reinforce these dynamics: targeted product launches optimized for machine compounding workflows and regulatory clearances for adjacent topical devices demonstrate the twin forces of product innovation and formal medical-device paths shaping adoption. Firms that combine repeatable dosing performance with regulatory readiness will gain privileged access to pharmaceutical channels in 2026.
Strategic playbook for 2026
Executives should consider the following prioritized actions:
- Accelerate regulatory alignment. If your product is intended for therapeutic delivery, allocate engineering and regulatory resources in H1 2026 to map device classification and prepare predicates or design dossiers. Early alignment shortens sales cycles with institutional purchasers.
- Demonstrate performance with real-world evidence. Invest in comparative dose-uniformity trials and user-experience studies. Data wins procurement decisions with pharmacists and clinicians; a demonstrable advantage allows premium positioning.
- Lock in quality-certified manufacturing. Whether through contract manufacturing partnerships or in-house upgrades, ensuring ISO 13485-compliant processes will be a deciding factor for pharmaceutical customers and increases enterprise valuation for exit scenarios.
- Calibrate go-to-market by end-use economics. Differentiate channels (pharmacy compounding vs. dermatology clinics vs. premium cosmetics) with distinct pricing, packaging, and clinical messaging aligned to payer and buyer incentive structures.
- Be opportunistic on M&A. Use the moderate concentration environment to pursue bolt-ons that add proprietary metering mechanisms, critical component technologies, or regulatory-ready manufacturing capacity rather than broad geographic scale alone.
How to use PW Consulting’s report in 90, 180, and 365 days
- 90 days: Run a supplier gap analysis using our supplier dossiers; prioritize short-list partners for clinical validation pilots.
- 180 days: Execute a regulated pilot (or 510(k)-aligned design refinement) and initiate procurement conversations with pharmaceutical customers using our performance benchmarks as negotiation anchors.
- 365 days: Close an M&A or strategic partnership that secures manufacturing capacity or a differentiated dispensing technology, and roll out a commercial program informed by our channel-specific guidance.
What we are intentionally withholding in this summary
In keeping with PW Consulting’s “trailer” approach, this public summary surfaces strategy, risk, and supplier direction while intentionally withholding the granular segment splits, region-by-region financial tables, and the full supplier scorecards that form the core operational intelligence. These datasets are essential for transaction-level or launch planning and are provided only with the full report and accompanying data licence.
Concluding recommendation
The topical dispenser market offers a clear, data-backed growth path for strategic entrants and incumbents who can combine clinical-grade performance, regulatory preparedness, and manufacturing quality. For executives setting resource allocation in 2026, our guidance is straightforward: prioritize validated metering performance, secure quality-certified production, and use targeted M&A to acquire missing technology or capacity rather than chasing broad geographic expansion. Those moves convert the sector’s steady CAGR into defensible, near-term commercial wins.
Next steps
Executives who require the complete analytical model, supplier scorecards, and tailored M&A/partnership recommendations should request PW Consulting’s full Worldwide Topical Dispenser Market report and data package. The full report contains the segment-level breakouts, scenario tables, and deal-level diligence tools needed to operationalize the strategies summarized here.
For detailed analysis of this topic, please visit the official page: Worldwide Topical Dispenser Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com